Health insurance wellness rewards: Should you share your fitness tracker data with your insurer? Know the privacy risks
Health insurance is no longer limited to paying claims when you fall ill. Insurers are increasingly using wellness programmes to encourage policyholders to exercise, stay active and adopt healthier habits, with rewards linked to activities such as walking, swimming or cycling.
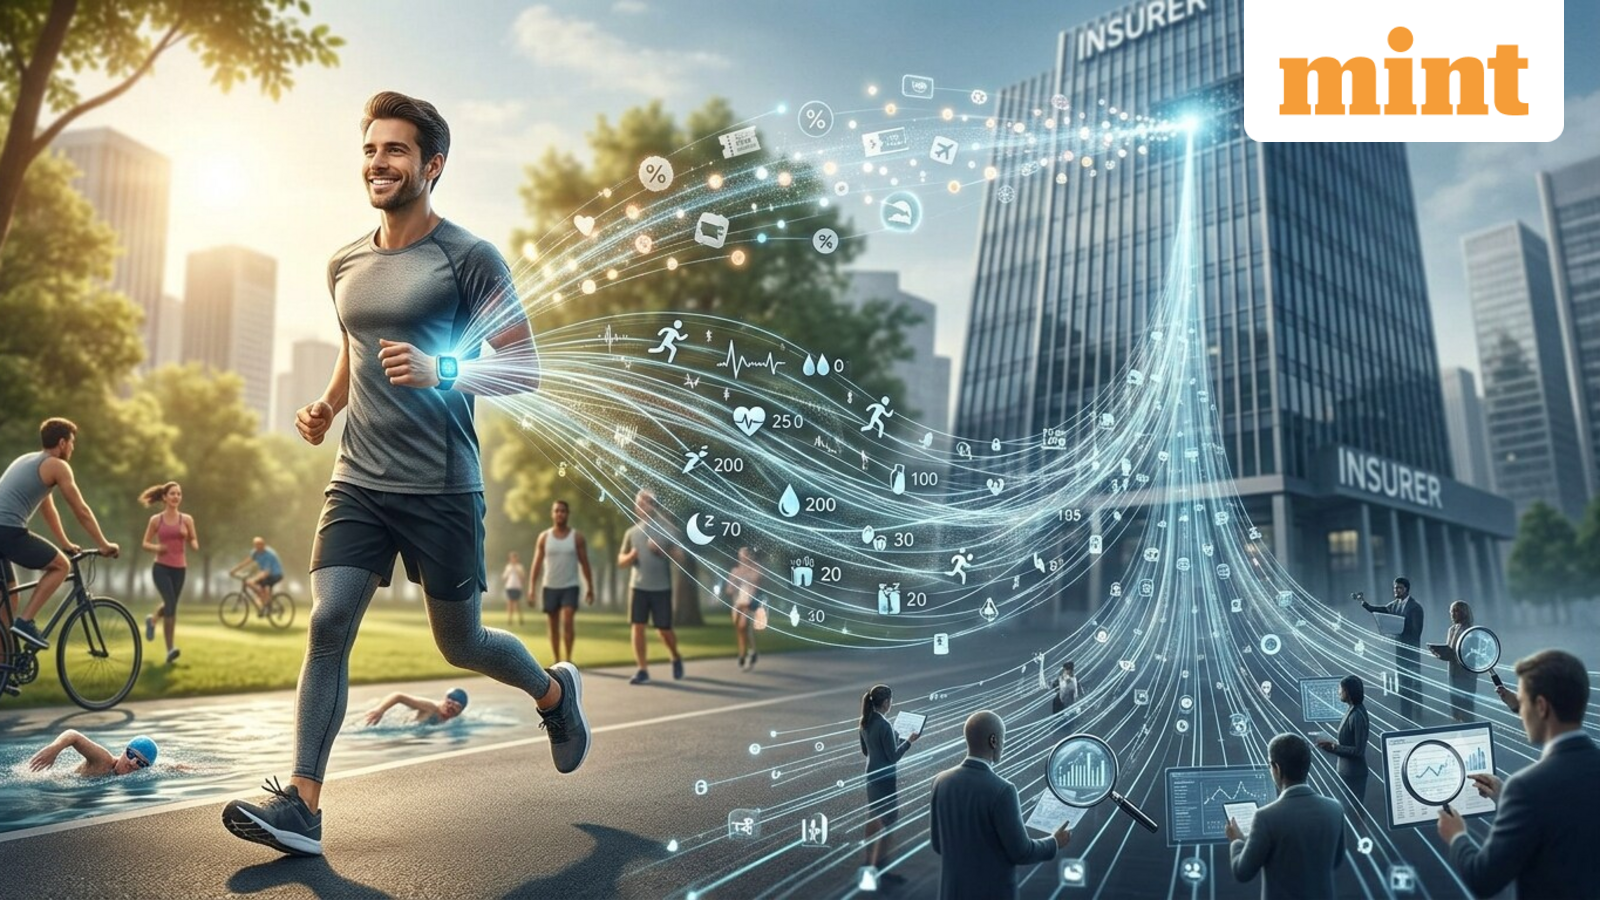
But these benefits can come with a trade-off that consumers may overlook. To participate in some wellness programmes, policyholders may have to share personal health and fitness information through apps, wearables or connected devices. That can include step counts, exercise patterns, sleep cycles and even diet or water-intake logs.
For consumers, the key question is not just what they can earn from a wellness programme, but also what happens to the health data they share.
What health data can insurers collect?
Wellness programmes can track a range of information depending on how the programme is designed and what benefits it offers.
“Insurers collect data like step count, healthy activities like spending time exercising in the gym or doing activities like swimming, cycling etc.,” said Arti Mulik, chief technical officer at Universal Sompo General Insurance.
She added that data from wearable devices can also include sleep cycles, water intake and diet intake logs.
Gurmeet Singh, vice president and head of health underwriting at IFFCO-TOKIO General Insurance, said the information collected depends on the programme and benefits offered. This may include physical activity, step count, exercise patterns, sleep and other health-related indicators, where customers permit such data to be shared.
The exact information consumers are required to provide can therefore vary from one insurer or programme to another.
What are the privacy risks?
Health information is personal data, making it important for consumers to understand exactly what they are agreeing to before connecting a wearable or health app to an insurance programme.
“Health data is personal data and consumers should understand what information is shared and what is it used for,” Mulik said. She recommended that customers carefully review the consent terms and privacy conditions before signing up.
Singh said consumers should look beyond what information is collected and check who can access it, how long it will be retained and whether it can be used for purposes beyond the wellness benefit.
This makes the consent screen and privacy terms particularly important. Consumers should check what data is being collected, why it is required, who may receive or process it and what happens to the information after they stop participating.
Can your health data affect your insurance?
The benefits of wellness programmes are generally structured around rewards for eligible activities. These can include points that are later redeemed for benefits such as discounts on renewal premiums or certain preventive healthcare services, depending on the product.
Mulik said wellness programmes are intended to reward healthy behaviour rather than penalise customers for not participating. She said the rewards and activities are specified in the policy wording and that such programmes do not affect claim settlement.
Singh, however, said consumers should look at the terms of the particular insurance product because the design of wellness programmes can differ. Any impact on premiums, renewal, coverage or claims would need to be considered according to the applicable policy terms and regulatory framework.
For consumers, this means a wellness reward should not be viewed simply as a discount for sharing data. The policyholder should first understand the conditions attached to earning and redeeming the reward.
What if your health indicators are poor?
Another concern is whether sharing health information could hurt a policyholder if the data shows poor health.
Mulik said wellness programmes are designed to reward good behaviour rather than penalise policyholders for poor health indicators. She added that some chronic-care programmes may specifically aim to help customers improve their health indicators, but such information does not affect claim settlement.
Singh said consumers should distinguish between information voluntarily shared as part of a wellness programme and information collected during the normal underwriting or claims process.
For policyholders, this distinction matters because the consent given for a wellness programme should be understood separately from the information an insurer may require for underwriting or processing a claim.
What should consumers check before opting in?
Before connecting a smartwatch, fitness tracker or health app to an insurance wellness programme, consumers should check:
- What data is being collected, such as steps, exercise, sleep or diet information.
- Why the data is required and what the wellness programme uses it for.
- Who can access the information, including any technology partners.
- How long the data will be retained and what happens if the policyholder leaves the programme.
- What rewards are actually available and the conditions for earning them.
- Whether the data can affect premiums, renewal, coverage or claims, based on the policy and programme terms.
- What consent is being provided before linking a wearable or health application.
The attraction of wellness programmes is straightforward: healthier behaviour can earn policyholders additional benefits. But consumers should also treat access to their health data as part of the bargain. Understanding the privacy terms before opting in can help them assess the benefit they receive against the information they are being asked to share.