₹85.30 lakh cash gifts from relatives: ITAT says donors’ low income alone isn’t enough to reject genuine gifts
Receiving a large cash gift from relatives does not by itself settle the tax treatment. When such a transaction is questioned, the recipient may have to establish who gave the money, whether the gifts were genuine and whether the donors had the financial capacity to make them.
A recent Chennai Income Tax Appellate Tribunal (ITAT) ruling has highlighted the importance of the evidence available with the recipient and the donors. The tribunal deleted a ₹85.30 lakh addition made under section 68 of the Income-tax Act after finding that the taxpayer had produced gift deeds, income-tax returns and financial statements of the donors, while the donors themselves had confirmed the gifts before the tax department.
The ruling came in Selvaraj Amirtharaj vs Income Tax Officer, Corporate Ward 5(4), Chennai, ITA No. 372/Chny/2026 for assessment year 2017-18. The order was pronounced on 18 September 2026.
What happened in the ₹85.30 lakh cash gift case
The taxpayer had received cash gifts totalling ₹85.30 lakh from five relatives during the financial year 2016-17. The amounts included ₹8.70 lakh from his maternal uncle, ₹29 lakh from his wife, ₹9.30 lakh each from two paternal uncles and ₹29 lakh from his sister’s husband.
During scrutiny, the tax officer questioned the source of the cash deposits in the taxpayer’s bank account. The taxpayer explained that the deposits included these family gifts, along with his own earnings and other receipts.
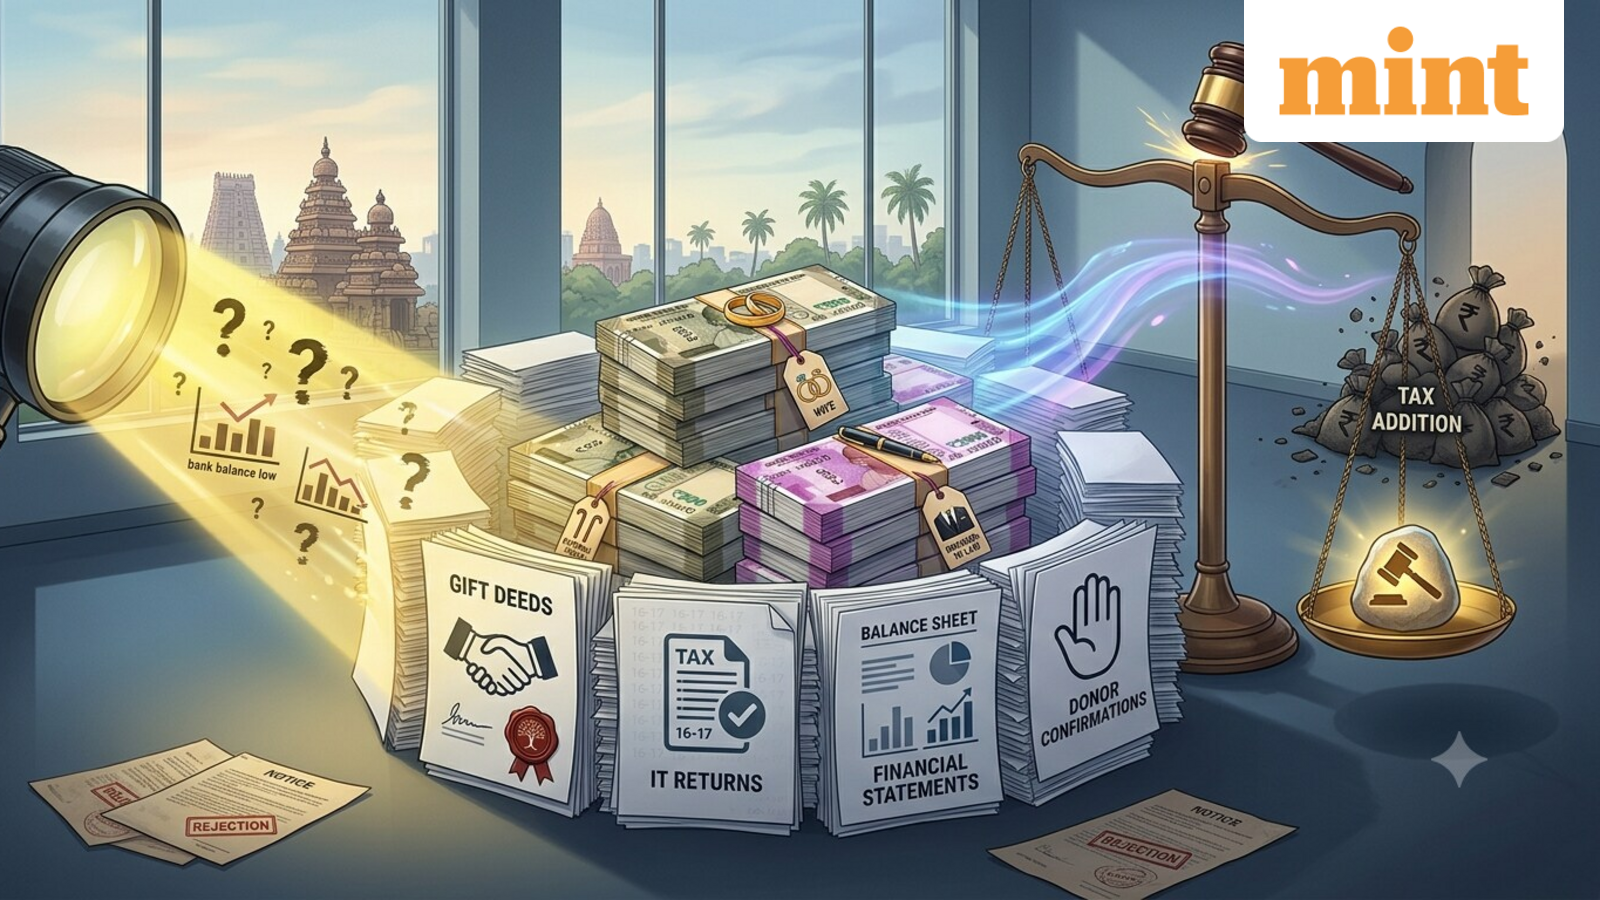
For the gifts, he submitted gift deeds, income-tax returns and statements of accounts of the donors. The five relatives also responded to notices issued under section 133(6), confirming that they had made the gifts.
The tax officer, however, was not satisfied with the explanation and treated the ₹85.30 lakh as unexplained cash credits under section 68. The addition was subsequently upheld by the Commissioner of Income Tax (Appeals).
Why the tax department questioned the gifts
The dispute was primarily about the creditworthiness or financial capacity of the donors.
For example, the CIT(A) questioned the ₹29 lakh gift from the taxpayer’s brother-in-law because his reported gross receipts were ₹7.38 lakh and his balance sheet did not, in the authority’s view, show enough capital or other funds to support the gift.
The financial capacity of the other donors was also questioned. In the case of two paternal uncles, the authorities referred to adverse findings in their earlier assessments. The CIT(A) concluded that the donors did not have sufficient capacity to make the cash gifts.
The taxpayer challenged this before the ITAT and submitted a 212-page paper book containing, among other documents, the gift deeds, income-tax returns, statements of income and financial statements of the donors.
The taxpayer also pointed out that all five donors had regularly been assessed to income tax and had filed returns for the relevant assessment year. Their declared incomes were ₹9.79 lakh, ₹25.39 lakh, ₹22.42 lakh, ₹21.29 lakh and ₹5.25 lakh respectively.
What the ITAT said about proving a cash gift
The Chennai ITAT distinguished between establishing the identity and genuineness of the transaction and investigating the source of the source.
It noted that there was no dispute over the identity of the five donors. They were the taxpayer’s wife, paternal uncles, maternal uncle and sister’s husband, and they had all confirmed the gifts in response to notices under section 133(6). The taxpayer had also submitted gift deeds, income-tax returns, statements of income and financial statements.
The tribunal held that once this evidence had been produced and the donors themselves had confirmed the gifts, the initial burden on the taxpayer under section 68 had been discharged.
If the assessing officer had doubts about the actual source of funds available with the donors, the appropriate course was to make enquiries in the donors’ own assessments, the tribunal said. The addition in the recipient’s hands could not be sustained merely because the officer suspected that the donors did not have enough funds, particularly when the identity of the donors and genuineness of the transactions had not been disputed.
The tribunal also said that the authorities had compared the donors’ reported income with the amount gifted without adequately examining their overall financial position, including accumulated capital, withdrawals, cash balances and other available resources.
Importantly, the ITAT said the Revenue had not brought any material showing that the cash deposited by the taxpayer had actually originated from the taxpayer himself. It therefore found that the addition was based on presumptions about the donors’ financial capacity rather than evidence establishing that the money belonged to the taxpayer.
What taxpayers should take from the ruling
The ruling does not mean that a large cash gift will automatically be accepted merely because it comes from a relative. The taxpayer in this case had documentary evidence, including gift deeds, tax returns and financial statements, and the donors themselves confirmed the transactions to the tax department.
For taxpayers receiving substantial gifts, maintaining documentation showing the relationship with the donor, gift transaction, donor’s tax records and financial position, along with evidence that the donor has acknowledged the gift, can therefore become important if the transaction is later questioned.