ITR filed under old regime, tax calculated under new regime; Delhi ITAT gives taxpayer relief
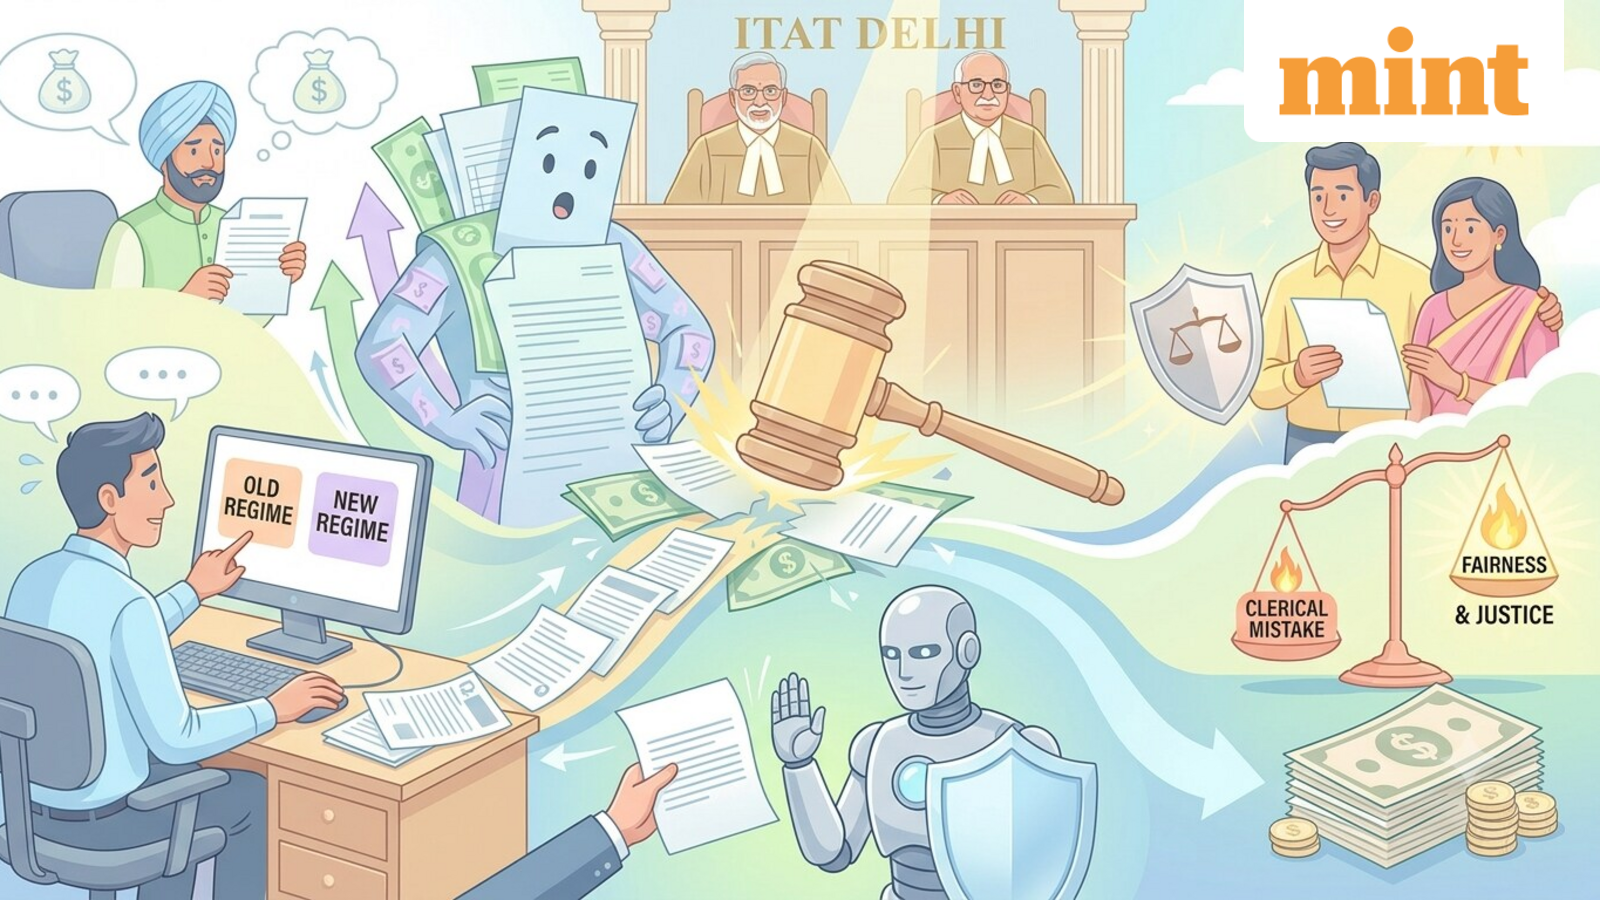
A taxpayer cannot be made to pay higher tax merely because an accountant made a clerical error while filing the income tax return, the Delhi bench of the Income Tax Appellate Tribunal (ITAT) has held.
In a recent ruling for assessment year 2024-25, the tribunal allowed the appeal of Sanjay Sharma, legal heir of late Divya Kala Sharma, after her accountant incorrectly stated in the ITR that she had filed her return under the old tax regime. The tax computation in the return, however, had been made under the new tax regime under section 115BAC of the Income Tax Act.
The error resulted in the Centralised Processing Centre (CPC), Bengaluru, processing the return under the old tax regime and raising a tax demand. The taxpayer subsequently approached the CPC seeking rectification, but the request was rejected. The matter then went before the National Faceless Assessment Centre (NFAC), before ultimately reaching the Delhi ITAT.
Accountant selected the wrong tax regime while filing ITR
The case concerns the return filed for AY 2024-25. According to the tribunal order, the accountant had indicated in the return that the taxpayer had filed it under the old tax regime, even though the tax liability had actually been computed under the new regime.
The tribunal noted that the discrepancy was specifically brought before the NFAC. The records showed that the tax computation in the return was made under the new tax regime, while the accountant had erroneously stated in ITR-1 that the taxpayer had chosen the old regime.
The CPC nevertheless processed the return using the old tax regime. Since that resulted in a higher tax liability, a demand was raised against the taxpayer. The taxpayer filed a rectification application with the CPC, but it was rejected.
The taxpayer then challenged the matter before the NFAC and subsequently the ITAT Delhi.
ITAT says taxpayer cannot be penalised for accountant’s clerical error
The Delhi ITAT examined whether the taxpayer could claim taxation under the new regime despite the incorrect selection reflected in the ITR.
The tribunal found that the taxpayer had in fact computed the tax liability under section 115BAC in the return. It also recorded that the incorrect statement about the tax regime was the result of a mistake by the accountant while uploading the return.
The bench of M. Balaganesh, Accountant Member, and Sudhir Kumar, Judicial Member, said the taxpayer could not be made liable for the higher tax merely because of the accountant’s clerical mistake.
“In our considered opinion, the assessee cannot be fastened with the tax liability for mere clerical error committed by her accountant,” the tribunal said.
Considering the facts and in the interest of justice and fair play, the ITAT directed the Assessing Officer to compute the taxpayer’s liability for the relevant year under the new tax regime. The appeal was accordingly allowed.
What taxpayers should check after filing ITR
The ruling highlights the importance of checking the tax regime selected in the filed ITR rather than relying entirely on the person who prepares the return.
In this case, the tax computation itself reflected the new tax regime, but the regime selection in ITR-1 was different. That mismatch led to CPC processing the return under the old regime and resulted in a demand. The taxpayer first had to pursue rectification and then appeal through the tax authorities before receiving relief from the tribunal.
The Delhi ITAT order, ITA No. 5309/Del/2026, was heard on 4 August 2026 and pronounced on 15 September 2026.
The ruling does not mean every incorrect tax-regime selection will automatically be reversed. The tribunal’s decision was based on the facts and material on record in this particular case, including the fact that the tax computation in the return itself had been made under the new regime.