Chime puts out the welcome mat for external AI agents

- Key insights: Chime will allow its customers to bring their own AI into its ecosystem, and work in tandem with its own AI assistant, Jade.
- What’s at stake: Financial institutions have been split on whether to allow external AI agents into their digital systems.
As financial institutions decide whether to
Processing Content
Chime is building secure connections to general-purpose AI agents, which will allow Chime members to use their preferred agent while staying in control of who can access their accounts and what actions agents can take with their money,
Those agents will work in tandem with Jade, Chime’s personal AI assistant that provides financial coaching and spending insights.
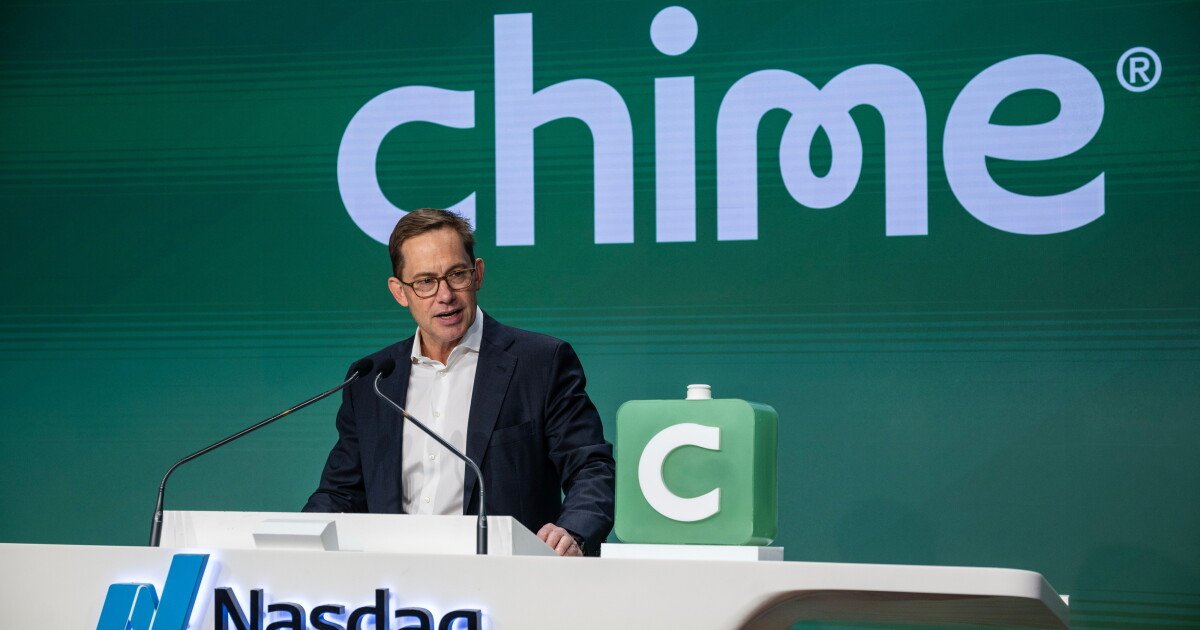
“We don’t believe that a single agent will be best suited to manage every area of your life. Researching a major purchase or planning a trip is one thing. In more complex, regulated categories like healthcare and finance, we believe that trusted specialist agents will win,” Britt said.
“When asking an agent to move money, pay bills, or manage investments, you need more than intelligence. You need financial expertise, safeguards you can trust, and accountability for every action. And that’s why our biggest bet is Jade, our personal finance agent for Chime members and ultimately all consumers,” Britt said.
Chime’s product development can also benefit from the AI boom, Britt said, noting that AI agents will make it easier for “consumers to find better-value financial products and
AI was one of four key growth areas, including Chime Prime, its lending businesses and its
Revenue for the third quarter ended Sept. 30 grew 32% from the prior year to $718 million, up from a 27% growth rate
Purchase volume increased 19% compared to the prior year to $38.5 billion, and 22% to $40 billion when including outbound instant transfers. And active members increased 20% year over year to 10.9 million, with 500,000 new customers added since the second quarter and approximately 1.8 million members over the last year.
Average revenue per active member, one of Chime’s most important key performance indicators, increased 10% from the prior year to $270. Notably, members that are part of Chime premium membership tier called
Chime also said its lifetime-value-to-customer-acquisition-cost ratio, which the company uses to evaluate the success of its massive marketing budget, was nearly 10x, up from about 8x when the company
“Chime sits in the digital banking sweet spot … having cracked the code on new member acquisition at compelling 10x LTV/CAC unit economics with strong interchange and short-term liquidity monetization,” Andrew Jeffrey, an analyst at William Blair, said in a research note. “Accelerating [monthly active user] growth, better [average revenue per active member], stable credit quality, a strong product pipeline, and ample operating leverage are a potent recipe for multiple expansion.”
Momentum in Chime Prime and the company’s lending businesses — which include its earned wage access product MyPay, its overdraft protection product SpotMe and its short duration installment loans called Instant Loans — and growth in Chime Prime helped underscore strong results for the quarter, according to Keefe Bruyette & Woods analyst Sanjay Sakhrani.
Originations across its three lending products hit $50 billion in annualized volume, with an average duration of two weeks and a loss ready around 1%. MyPay originations hit $5.3 billion, generating more than $500 million in annualized revenue during the quarter, Britt said. Chime doubled the maximum MyPay limit to $1,000 during the quarter.
Instant Loans grew at a faster rate, with origination volume during the quarter growing to $381 million. More than 20% of active members use the product, Britt said.
“Our lending products deepen our primary account relationships, and they’re becoming a bigger driver of RPAM and transaction profit,” Britt said. “We’re now taking the same disciplined playbook to new products, including our unsecured line of credit currently in beta, and an unsecured credit card in employee testing that we expect to roll out next year.”
Chime’s acquisition of Stride Bank is also expected to be an approximately $100 billion windfall for the payments fintech that will lower the company’s cost of funds, Troughton said. The bank charter will also allow Chime to offer its lending products in all 50 states and stop paying sponsor bank fees.
Chime would have had about $6.5 billion in total assets, which includes about $1.6 billion in commercial loans, as of the end of September across both its banking partners. The company also reiterated that Chime intends to stay asset light and below the $10 billion threshold for the “foreseeable future,” and that if it were to cross that threshold, it would be “because the economic benefits of crossing it are greater than the costs of crossing it,” Troughton said.
“If we ever do get close to that level — and we hope we will — there are active capital markets for us,” Troughton said. “Our assets here are very attractive. They’re short duration, they’re low risk, underwritten by direct deposit with unique underwriting signals. There’s a very active market for us to be able to get some assistance with those assets.”