3 Reasons to Own McDonald’s Stock by Dec. 1 to Qualify for Its First Payout as a Dividend King
McDonald’s (MCD -0.12%) is set to join fewer than 60 U.S. public companies as the newest Dividend King, a designation for companies that have paid and raised their dividends for at least 50 consecutive years. The fast food giant’s latest quarterly payout of $1.93 per share marks a 4% increase over its prior payout. And at $7.72 per share — McDonald’s now has a forward dividend yield of 3.2% — which is higher than most Dividend Kings and roughly triple the yield of the S&P 500 (^GSPC +0.41%).
Investors who own the stock by Dec. 1 will be eligible to receive the $1.93 per share payout on Dec. 15. Here’s why McDonald’s is one of the best restaurant stocks to buy now.
Image source: The Motley Fool.
1. A franchise model executed to perfection
As of Dec. 31, 2025, 96% of McDonald’s global store count of 45,356 were franchised — including a 95% franchise rate in the U.S., 89% of international operated markets (mainly in Europe), and 100% of stores in China, Japan, Brazil, the Philippines, and South Korea.
McDonald’s is nothing short of a global sensation. U.S. restaurants now make up just 30.2% of systemwide revenues — making McDonald’s primarily reliant on international markets.
The company’s franchise strategy, paired with its global diversification, makes it increasingly resistant to recessions, especially if they are concentrated in a particular geography. Franchisees pay McDonald’s a down payment for opening a restaurant, along with licensing fees, rent, royalties, and other expenses. And in exchange, the franchisee keeps the majority of store sales, unlocks McDonald’s instantly recognizable global brand, benefits from its supply chain and marketing, and connects with its app, which has become an integral way to increase customer engagement through mobile ordering and rewards.
2. McDonald’s FCF yield has soared to 4.5%
The franchise model generates predictable free cash flow (FCF) for McDonald’s, helping it manage expenses and providing visibility into its dividend payments.
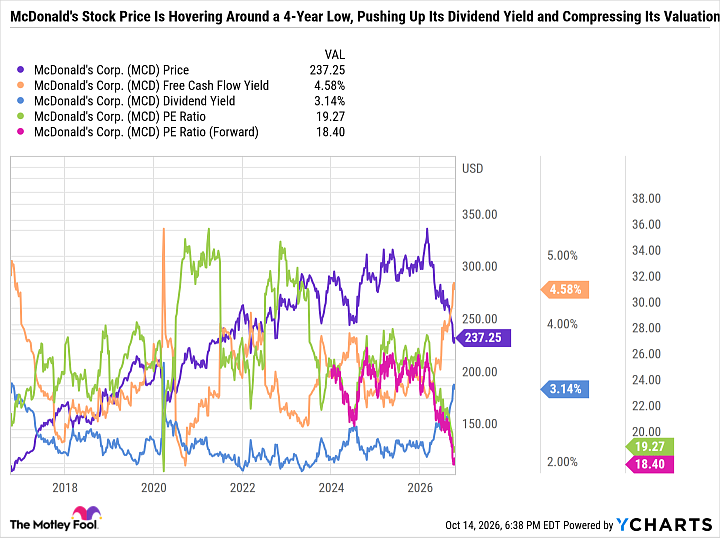
As you can see in the chart, McDonald’s FCF yield of 4.5% is higher than its trailing dividend yield of 3.1%. Meaning that if McDonald’s were to theoretically pass along all of its FCF to shareholders, it could afford a 4.5% dividend.
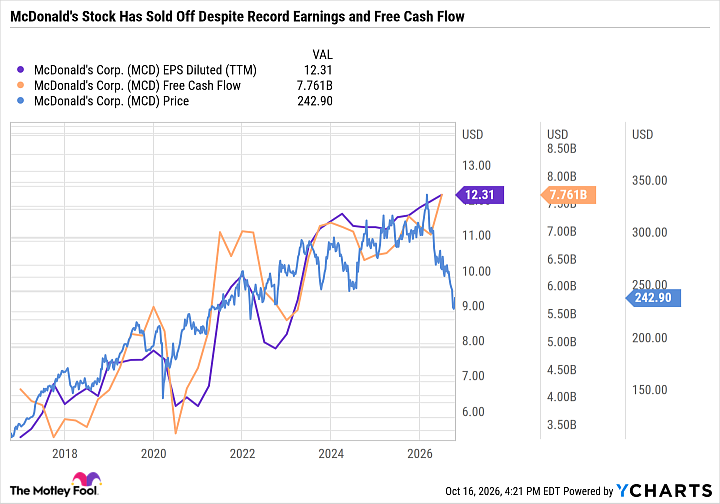
MCD EPS Diluted (TTM) data by YCharts
Earnings and FCF are at all-time highs, but its stock price has fallen dramatically — down 20.5% year-to-date and 28.9% from its all-time high of $341.75 (achieved on March 2).
MCD McDonald’s
$242.67-$0.30 (-0.12%)
NYSE · As of 4:00 PM ET 10/19/26
The sell-off has pushed McDonald’s dividend yield to multi-year highs and compressed its valuation. McDonald’s now has a price-to-earnings (P/E) ratio of just 19.7 and a forward P/E of 18.9. That’s dirt cheap for a stock that has traditionally commanded a premium over the S&P 500 — as its 10-year median P/E is 25.8.
3. McDonald’s is investing $8.5 billion in long-term growth
McDonald’s is a cash cow with a high yield and an inexpensive valuation. But there are valid reasons the stock is selling off.
The biggest factor is weak same-store sales. In McDonald’s second quarter 2026, same-store sales in the U.S. were up just 0.8%, and global same-store sales increased 1.3%. Global systemwide sales were up 5%, but that’s mainly from new store openings. This has been a common theme in the quick-service restaurant industry, where many companies are relying heavily on new store openings to drive growth. Same-store-sales growth is the crown jewel for restaurants and retail because it indicates pricing power and strong demand for products and services.
Inflationary pressures are affecting consumer spending. An emphasis on health and wellness is another factor that fast-food restaurants, chip and snack brands, soda companies, and packaged-goods companies are contending with.
Despite these headwinds, McDonald’s remains confident in its long-term growth plan. On Sept. 23, it released an $8.5 billion, 10-year roadmap to invest in its franchises and drive consumer demand. The costs are front-loaded, with $5 billion in expected added costs through 2030, which could impact margins and FCF. But again, McDonald’s high margins, thanks to its franchise model, allow it to afford this mammoth investment when some of its peers are treading water.
The 10-year strategy centers around investing in the McDonald’s menu, its customers, restaurants, and people. McDonald’s expects roughly $100,000 in annual cash flow benefits for the average U.S. restaurant. In addition to efficiency improvements, McDonald’s expects to take market share in the chicken and beverage categories while maintaining its leadership in beef.
A high conviction value stock to buy now
One of my favorite investment setups is when a top company in an industrywide downturn decides to invest in long-term growth rather than over-altering its strategy just to boost its near-term numbers. McDonald’s can’t control inflation or consumer spending, so it’s putting the pieces in place to boost efficiency and market share over the long term.
Throw in an ultra-reliable dividend and an inexpensive valuation, and it’s easy to see why McDonald’s stands out as one of the best high-yield value stocks for long-term investors to buy now.