Flat sold 10 days after registration: How an allotment letter helped an NRI claim long-term capital gains tax benefits
A flat sold just 10 days after registration may appear to qualify as a short-term capital asset for income tax purposes. However, the date of registration is not necessarily the date on which a buyer acquired the property for calculating capital gains tax. An allotment letter issued years earlier can establish an earlier holding period, provided it conferred enforceable rights over the property.
The Income Tax Appellate Tribunal (ITAT), Surat, addressed this issue in Jagdishkumar Chhotubhai Gandhi v. ITO (International Taxation), Surat, ITA No. 245/SRT/2024, in an order dated 29 September 2026. The tribunal held that the holding period should be counted from the date of the allotment letter rather than the subsequent registration of the flat.
The ruling offers an important lesson for homebuyers who purchase under-construction properties and register them much later. The date on the sale deed may not, by itself, settle whether gains from a subsequent sale qualify as long-term capital gains (LTCG).
Why the tax department treated the gain as short-term
According to the tribunal order, the taxpayer, a non-resident Indian (NRI), had purchased an under-construction flat in Annora, Rodas Enclave, Hiranandani Estate, Thane, from Roma Builders Pvt. Ltd.
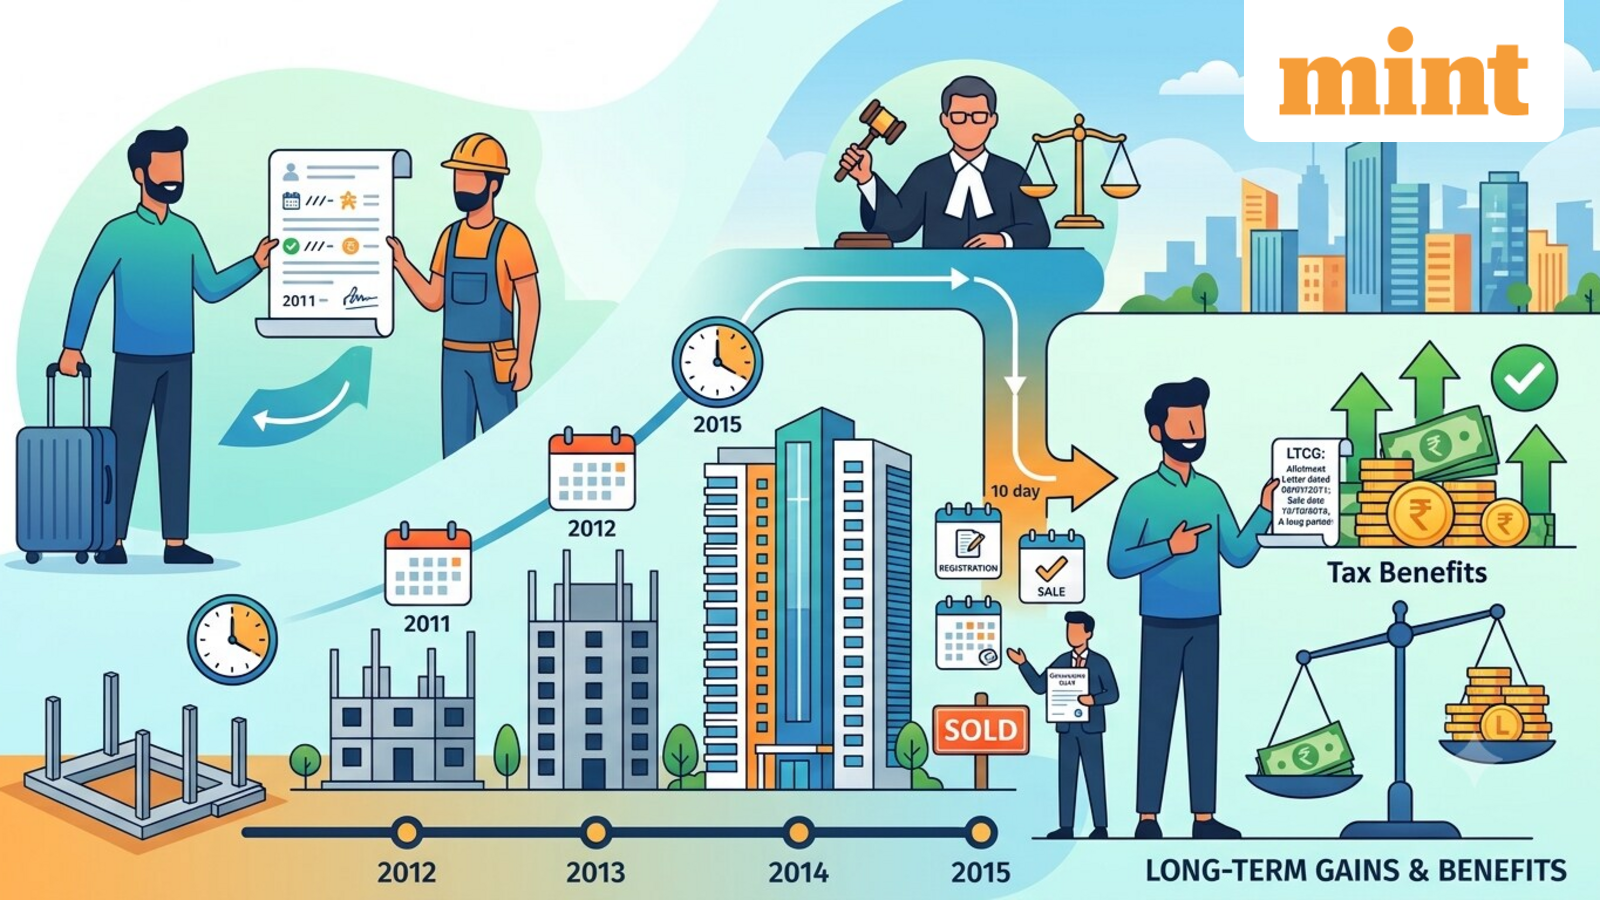
The allotment letter was issued on 8 January 2011 for a consideration of ₹1.43 crore, excluding service tax, value-added tax and other expenses. The taxpayer’s total cost, including these expenses, was ₹1.57 crore.
The conveyance deed was executed and registered on 30 September 2016. The taxpayer then sold the property on 10 October 2016 for ₹2.78 crore, just 10 days after registration.
The tax dispute arose because the assessing officer treated ₹68.12 lakh as short-term capital gains. The taxpayer challenged this treatment, arguing that his holding period began when the builder issued the allotment letter in January 2011.
The distinction mattered because the property had been allotted more than five years before its sale. Counting the holding period from the allotment date, rather than registration, changed the classification of the gains.
Why the allotment date mattered
The tribunal examined earlier judicial decisions on when a buyer can be considered to have acquired a property for capital gains purposes. These decisions recognise that a buyer may acquire enforceable rights over a specific property before the conveyance deed is formally registered.
The tribunal referred to rulings including CIT v. A. Suresh Rao, Madhu Kaul v. CIT and CIT v. Ramakrishnan, which dealt with the significance of allotment letters and the date from which an asset is considered to be held.
It also considered Central Board of Direct Taxes (CBDT) Circular Nos. 471 and 672, which address the treatment of allotments under certain housing schemes.
Following these precedents, the tribunal concluded that the holding period should be computed from the date of the allotment letter. Since the period from 8 January 2011 to the sale on 10 October 2016 exceeded 36 months, the property qualified as a long-term capital asset under the law applicable to the relevant assessment year. The tribunal directed that the gains be treated as LTCG.
This distinction is important because the relevant date may depend on the rights created by the allotment, the terms of the agreement and the supporting documents. A booking receipt alone may not establish the same rights in every transaction.
What the ruling means for homebuyers
For buyers of under-construction homes, the ruling highlights why property documents should be retained even after registration is completed.
An allotment letter identifying the property, the builder-buyer agreement, payment records and the conveyance deed can help establish the sequence of events. These documents may become particularly important when registration takes place several years after allotment and the property is sold soon afterwards.
However, the ruling should not be read as a blanket exemption for every property sold shortly after registration. Whether the allotment date can be used depends on the facts and the legal rights created by the documents. Taxpayers should also distinguish between selling rights in an under-construction property and selling a completed property after taking possession, as the nature of the asset and the applicable judicial precedents can affect the analysis.
The holding-period threshold has also changed since the transaction in this case. For transfers of immovable property on or after 23 July 2024, the general holding period for classification as long-term is more than 24 months, rather than the 36-month threshold applicable to this 2016 sale. The applicable tax rate and indexation rules must be assessed separately under the law governing the particular transaction.
For homebuyers, the broader lesson is to retain the allotment letter and the complete payment and registration trail, and to assess capital gains using the applicable holding-period rules and the specific facts of the sale.