Health insurance claim: 5 things to prepare before hospitalisation to avoid last-minute hassles
A serious medical emergency can occur suddenly due to an unexplained health problem, accident or any similar unforeseen event. Such a situation can throw difficult-to-manage challenges for an individual and their immediate family members.
Such a situation can be stressful and emotionally draining, making it daunting to search for insurance documents, policy terms, network coverage, hospital details, and other essentials to support a medical claim.
That is why preparing a few essential details in advance can help families navigate the health insurance claims process with greater clarity and peace of mind.
Keeping these basics in mind, this article is dedicated towards outlining 5 things families should prepare before hospitalisation to reduce last-minute confusion and keep important information accessible.
5 ways to prepare for a smoother health insurance claim process
1. Share health insurance policy details with family members
The health insurance policy should not remain only on the mobile device or in the email inbox of the individual who purchased it. Other immediate family members, such as parents, brothers and sisters, should know where to find the complete policy document, insurance card details, policy number, purchase acknowledgement slip (if needed), and the insurer’s updated contact details.
Given the unforeseen nature of medical emergencies, it is wise to maintain digital copies of the health insurance policy. Along with the digital copy, keep a printed one in an accessible place. Also note that the key policy terms, sum insured details, and essential policy conditions must be clearly known and available to all family members so that such details can be quickly and easily accessed, especially during medical emergencies.
This becomes extremely important, especially when the policyholder requires hospitalisation and is not in a position to manage the paperwork effectively.
2. Identify network hospitals in advance
Once you have the main policy document, it is wise for the individual and their family to carefully review its basics. Families should hence identify hospitals near their homes and workplaces that are part of their insurer’s network. If parents live in a different city, network hospitals should also be checked in that area.
A network hospital may offer cashless treatment, subject to the policy’s terms and the insurer’s authorisation. However, network lists can change, so verify the hospital’s current status through the insurer’s website or helpline before admission, wherever possible.
Having a clear understanding of the available options and opportunities for securing quick, seamless hospital admission in an emergency can save invaluable time when a sudden medical emergency arises.
3. Prepare a one-page medical history for every insured member
Focus on maintaining a crisp, concise medical history for each insured family member. This history should cover previous surgeries, hospitalisations, ongoing medicines and treatments (if any), and other relevant diagnoses and any resistance to particular medicines or drugs. Ensure that you keep prescriptions, consultation records and discharge summaries in the same folder for quick reference. These documents should be kept in a way that they can be easily shared with a doctor within minutes if needed.
Accurate, timely sharing of medical information can help doctors understand the patient’s medical history and support seamless treatment. Not only that, but it can also help with the documentation required during claims processing. Once a policy is purchased, policyholders should also preserve records of past medical conditions, along with discharge and admission dates, for future reference.
Furthermore, when completing claim forms, disclose medical information accurately and consistently with available records. Missed information or incorrect disclosures can lead to questions later on. If escalated, such a situation can also result in delays and disputes, depending on the circumstances.
4. Understand the important conditions and limitations of your policy
Just paying the premium is not enough on the part of the health insurance policyholder. It is important for the policyholder not to just wait until hospitalisation to find out what their health insurance covers. You should review the policy documentation and prepare a concise summary of its key benefits and limitations.
Check the following details carefully:
- Sum insured and bonus: Understand the base cover on a conceptual level and any applicable cumulative bonus for clarity.
- Room-rent limits: Check whether the policy restricts or otherwise limits the room category or rent. If yes, understand the details clearly to avoid exceptional expenses or surprises later on.
- Co-payment and sub-limits: Find out whether you must pay a specified share of eligible expenses or whether limits apply to particular treatments. Co-payment can come in various forms in a health insurance policy; clarity on the same is indispensable to enjoy the policy meaningfully.
- Exclusions and waiting periods: Check which treatments are excluded from your policy (if any) and whether any waiting periods for pre-existing conditions or specified illnesses have been met.
- Restoration benefits: You should also have a clear understanding of when the cover can be restored and the conditions governing its use.
This thorough review of the health insurance policy terms can help families anticipate potential out-of-pocket expenses they might have to pay if such a situation arises. The actual amount payable by the insurer will eventually depend on the policy terms, admissible expenses and applicable authorisation requirements.
5. Create a dedicated health insurance claims folder
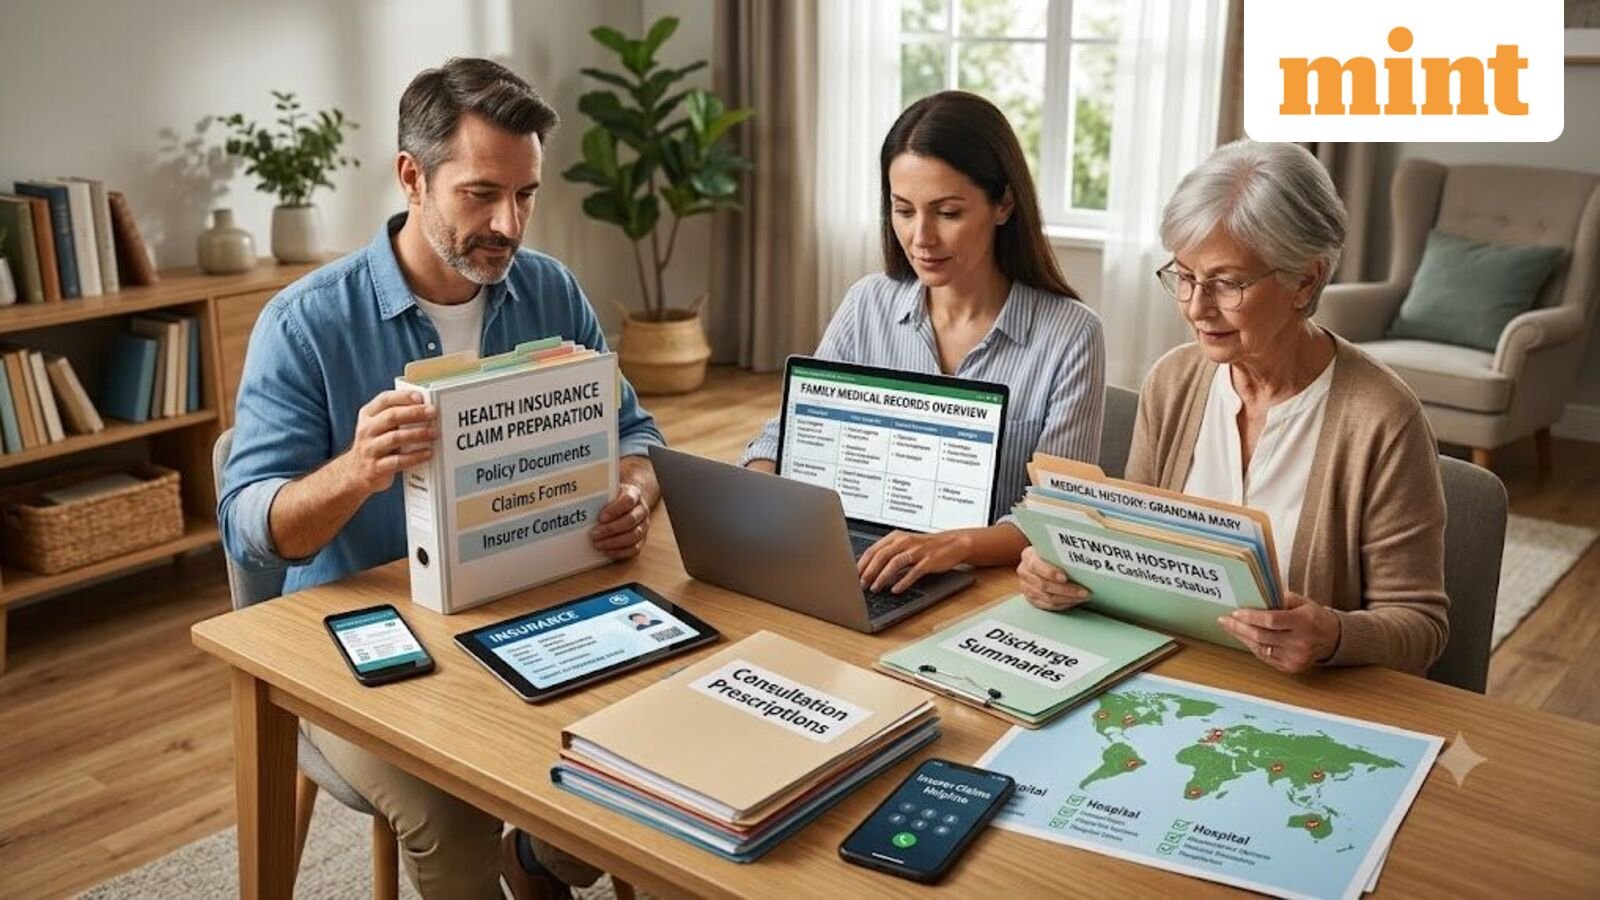
Make sure that you keep a physical/ digital claims folder ready. This can be immensely helpful during a medical emergency. It should contain all the essential policy documents, insurance cards, relevant identification documentation and details, medical history, current prescriptions and previous discharge summaries. Basically, this is a medical database for an individual health insurance policyholder.
Once any particular hospital stay is complete, the policyholder should ensure that they preserve the discharge summaries, investigation reports, prescriptions (if any), itemised bill details, and payment receipts. These documents may be essential for reimbursement claims and eligible pre- and post-hospitalisation expenses, subject to policy conditions.
It is also prudent to save the insurer’s official claims helpline number, customer support number and insurance advisor’s contact details. Family members should know how to apply for and request cashless authorisation (if needed) or initiate a reimbursement claim.
Preparing for a health insurance claim is not just about keeping a policy document handy. It is about knowing the complete process step by step, and making sure that the entire process is also known to immediate family members.
These simple and straightforward five steps can help make the entire process of claims management more manageable and seamless. However, it is essential to keep in mind that these steps cannot guarantee approval of claims at all times.
Going through these basic steps and details before a medical emergency gives families a better chance of handling the paperwork efficiently, when their priority should be the patient’s treatment, a seamless policy-usage experience, and meaningful recovery.
Disclaimer: This article is for general information only and not insurance advice. Coverage and claim approvals depend on policy terms, exclusions and insurer authorisation. Policyholders should review their policy documents and consult a qualified insurance adviser for guidance.