UK construction faces mixed outlook as contract awards rise but project starts fall – Mortgage Strategy

UK construction activity remains under pressure, with new data from Glenigan showing declines across planning approvals, contract awards and project starts over the three months to the end of September 2026.
The October edition of the Construction Review, published by Glenigan, found that detailed planning approvals fell 16% against the preceding three months and 28% year-on-year.
Main contract awards declined 19% quarter-on-quarter, while project starts recorded the steepest fall, down 26% against the previous three months and 21% compared with the same period last year.
Despite the downturn, main contract awards provided a notable exception to the wider weakness, rising 25% year-on-year as major schemes progressed towards construction.
The figures reflect wider economic challenges facing the sector. While the UK economy has continued to grow, official data recorded a 0.5% decline in construction output, underlining the difficulties facing the industry.
Glenigan’s analysis points to a combination of subdued private investment, pressure on household finances and persistent constraints on the public sector planning system.
Budget cuts and staff shortages continue to affect planning departments, while uncertainty over government spending and borrowing costs is influencing investment decisions.
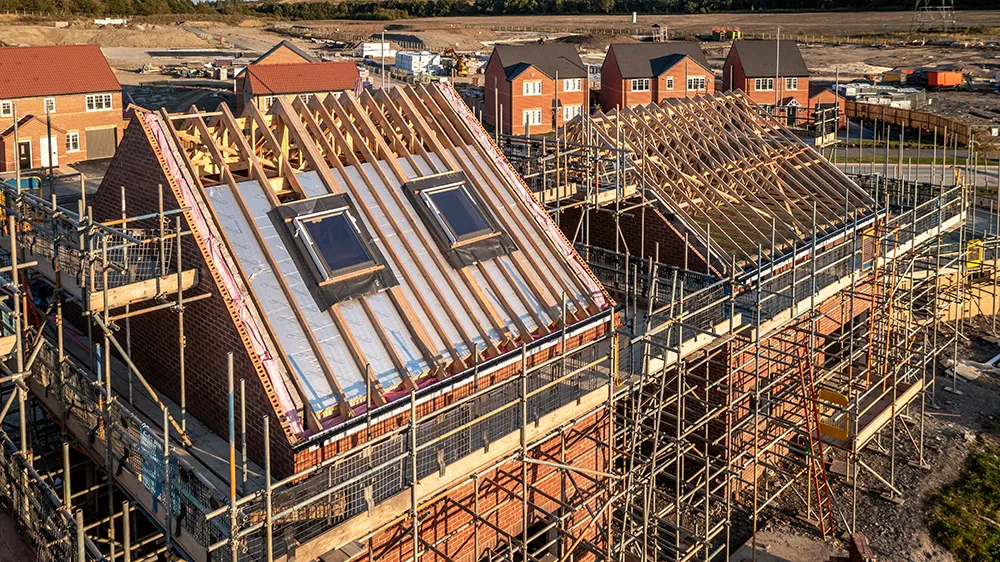
Residential construction remains under pressure, with social housing providing a significant counterbalance to falling private sector activity.
Social housing starts surged 165% year-on-year to £5bn, accounting for 47% of residential starts. In contrast, private housing starts fell 34% to £3.2bn, while private apartment starts dropped 52% to £1.235bn.
Higher mortgage costs, falling house prices and squeezed household budgets continue to weigh on private demand, limiting developers’ appetite to bring forward new schemes.
Across the wider residential sector, project starts were down 3% year-on-year, although they improved against the previous quarter, supported by major projects.
Main contract awards increased 22% annually, driven by growth in underlying schemes, while detailed planning approvals rose 2%, suggesting modest improvement in the medium-term pipeline.
Yorkshire and the Humber recorded the highest value of residential starts, at £4.427bn, largely driven by the £4bn Leeds City Centre Heat Network project. London ranked second at £1.2bn, despite a 42% decline.
The North West recorded 27% growth to £1.1bn, while Northern Ireland more than doubled its residential starts to £296m. Most other regions experienced declines.
While private sector performance remains subdued, selected public sector markets have shown greater resilience.
Education planning approvals rose 60% year-on-year, while approvals for community and amenity projects surged 200%.
The increases suggest that government spending commitments are beginning to translate into activity across areas of public infrastructure and community provision.
However, the picture elsewhere remains mixed. Office and industrial project starts both fell 55%, reversing the stronger performance seen in the first half of 2026.
Civil engineering approvals also plunged 70%, raising concerns about the strength of the pipeline in the months ahead.
The divergence between public and private sector performance highlights the uneven nature of the current market, with some publicly supported projects progressing while private developers remain cautious.
Allan Wilen, economics director at Glenigan, said the rise in contract awards offered some encouragement but warned that it did not yet signal a broad-based recovery.
“Rising contract awards show intent and suggest confidence is returning to parts of the market, telling us schemes are being planned and funded, but the work has not reached the ground yet,” he said.
“Too much of the market still rests on a small number of large projects. If one of them slips, the whole sector feels it and a market that relies on a handful of big schemes is fragile. A genuine recovery needs to be seen across smaller, underlying schemes, valued under £100m, too few of these are currently moving forward.”
Wilen said both public and private markets were facing significant challenges, with private developers contending with tariffs, taxes and higher interest rates, while uncertainty remained over public spending commitments.
“Developers and contractors are waiting to see what the Budget means for households and businesses and promised government investment,” he added.
“The Budget could be the most significant since Osborne’s austerity Budget and we will be watching it closely to assess how it could impact our recovery predictions for 2027.”