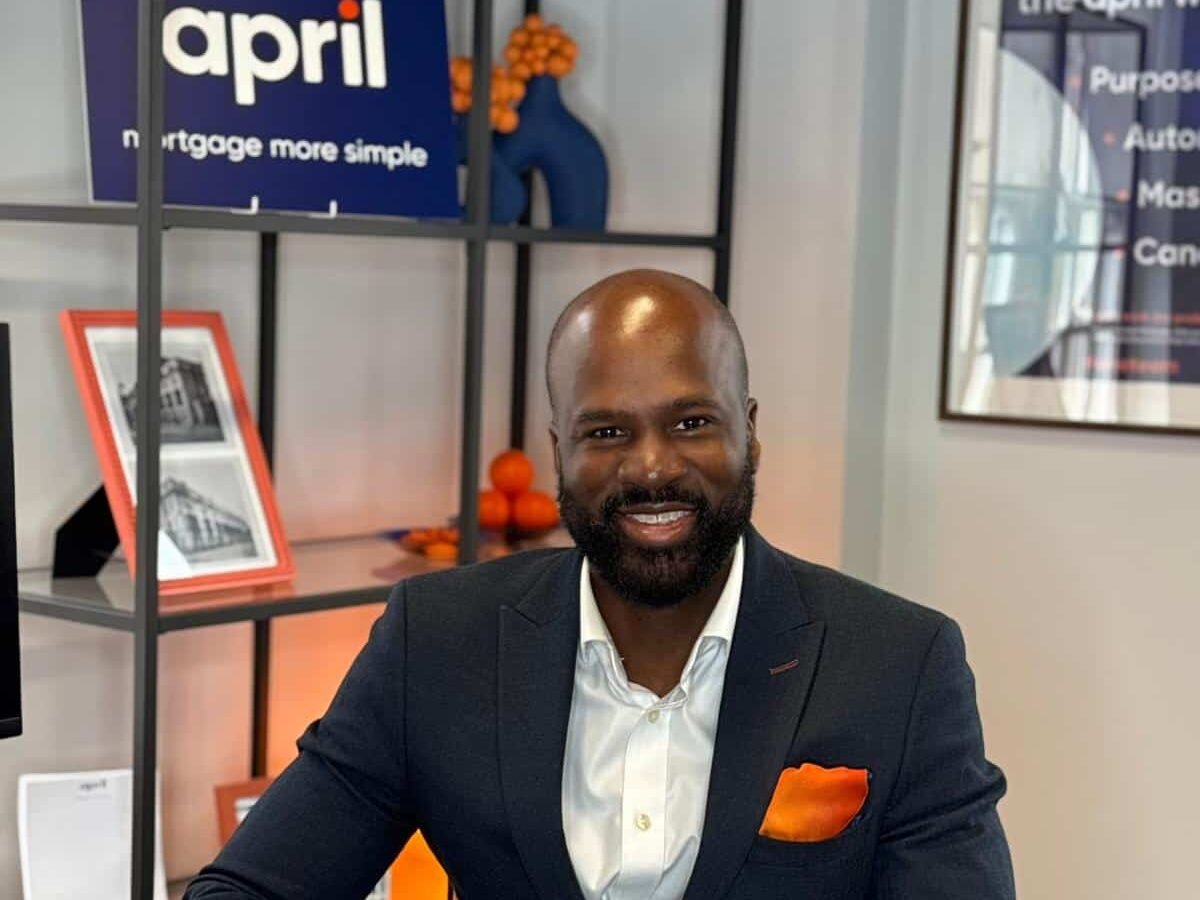
Brown: April Mortgages is a ‘modern lender’ built for modern-day problems
April Mortgages’ repositioning of its proposition for the over-50s illustrates its plan to be a lender that resolves challenges faced by today’s borrowers, its head of intermediary relationships said.
Speaking to Mortgage Solutions, Michael Brown said his role had broadened and the sales function had “tightened up” to make operations more efficient.
He will work closely with April Mortgages’ COO Mark Eaton to align its distribution, “deepen our relationship with our intermediary partners”, while building consistency and trust.
“The first two years have really been around brand recognition, and that was an important strategy to have. However, when I was out on the road, I asked people: ‘Are you aware of April?’ Overwhelmingly, the answer has been yes.
“However, when I asked, ‘Do you know what we do?’, the answer was less certain,” Brown said.
Now, he will be responsible for April Mortgages’ brand awareness so people understand its proposition better.
Industry, not regulation, must lead later life lending change
Sponsored by Suffolk Building Society Intermediaries
This will involve an intimate insight into the needs of the lender’s distribution partners and the challenges they face, as well as how the lender can contribute toward their business success.
“For us, it’s a two-way street. Having worked in distribution myself and understanding the challenges and goals and objectives, I think that really gives me a huge advantage and gives me really good insight into supporting our distributor partners,” Brown added.
April Mortgages’ recent hire, Lewis Chinyou-Robinson, will support this function, providing a smooth adviser onboarding process by removing upfront friction and changes to its due diligence process.
The lender’s business development managers (BDMs) will be committed to meeting with intermediary partners as often as possible; “we don’t want to just rattle out criteria to brokers. We want to personalise every meeting. Our BDMs work diligently to understand what they will speak about with each business and match the opportunities we offer that should support their potential needs.
“For example, if a business deals with a lot of first-time buyers, their clients will have the affordability or deposit challenge. So, we’ll educate the broker or brokerage about the potential solution we offer.”
It is also key to be sourced correctly, so April Mortgages will work with external sourcing partners to make their criteria findable.
The lender aims for its onboarding process to be seamless, giving advisers access to its telephony team, who will “identify opportunities”, a BDM team that will hold meetings “specifically tailored” to each firm’s needs, and accurate sourcing. The underwriting team will also be on hand to spot cases that may fall just outside policy, which the lender may still consider in its aim to be known as “flexible while still keeping responsible lending as part of our ethos”.
Having just come from the distribution side of the mortgage market, Brown said he had a “huge respect for brokers and their business”, as well as their desire to do what is right for clients in the face of various challenges.
He said it was important that April Mortgages “continues to listen” to advisers and mirror the different parts of their job, so the lender is not “just a transaction partner, but a partner that deals with relationships and finds solutions”.
Brown said April Mortgages was “evolving” by deepening its relationships with intermediaries, which would become more evident as its proposition changed and it continued its “huge drive in building connections”.
Being known as a modern lender
April Mortgages recently bolstered its proposition for borrowers over 50 to highlight solutions for homeowners across all stages of life.
Brown said it was an “evolution” of April Mortgages’ strategy: “We were always focused on being a modern lender, and that’s the really critical piece.
“We want to champion people getting onto the housing ladder for the first time, and equally, ensure they stay in their property.”
He added: “We can be that lender who will take a look at all these different scenarios across the lifecycle of the mortgage, and we want to be in a position to have a solution for everyone.”
“We know that life events happen, and therefore our flexibility as a modern lender is really important,” Brown said.
April Mortgages offers fixed rates on terms between five and 15 years, with no early repayment charges for borrowers who move home. There is also no penalty for borrowers who overpay using their own savings or on the sale of their home, and the mortgage rate automatically reduces as the loan is paid down and borrowers move into lower loan to value (LTV) tiers.
It has a 100% No Deposit mortgage and lends up to seven times income, with interest-only and part and part repayment options available.
This is open to first- and next-time buyers, such as people going through a divorce who may have a good income but not enough of a deposit.
Brown said such a proposition should not just be for renters, like other options on the market, as broad access mattered.
Eligibility for its interest-only proposition has also widened, with the minimum income required now £24,000, and no minimum equity is required for 50-plus borrowers.
Brown said many borrowers over 50 came to the end of an existing interest-only mortgage and found they had limited options, adding that this was where the “modern lending” concept came into play, as April Mortgages sets out to be a “lender that will solve problems for the modern day market, whilst also having the vision to look at the future and listen to intermediary partners who have the foresight and knowledge of the market”.
He said the lender’s focus was to get as many people owning homes as possible, staying in them and not “be forced to either sell or go onto a more expensive scheme”.
People are living longer, buying their first home in their 30s and taking on mortgage debt later into life, Brown noted, adding: “15 years ago, people were automatically put onto 25-year terms, which I assume was just based on their retirement age. Now, affordability challenges play a part, and accessibility plays a part. People are looking at terms up to 40 years, which we offer because we understand that there needs to be capacity to support people.
“Looking at all the trends, we know that the later life lending market will continue to grow and needs to be serviced. We want to be at the forefront to support borrowers over 50.”
April Mortgages is currently “working on something really big”, which will align with its ethos of identifying modern day problems and finding modern day solutions.
This would fill a gap in the lender’s existing offering, Brown said, which currently serves borrowers living in the UK permanently and with a clean credit file.
Championing the whole mortgage sector
Brown said he was “passionate” about many causes, such as the work carried out by the Black Mortgage Professionals and Allies Network (BMPAN), Working in Mortgages, and generally educating brokers who are new to the sector.
He said entrants were less likely to be encumbered by old practices, and a modern lender like April Mortgages could show them the novel ways clients could be supported.
“There are great lenders out there that do specific things; we want to be known as the lender that doesn’t focus on just one area but one that has a range of solutions,” he added.
Brown wants to ensure he “pays it forward” and give homage to the mentors who have supported him throughout his career, making it possible to be in his current position.
He “sees everyone as peers, not rivals” and said his career experience combined with what he learned from others was helping him “shape that April Mortgages experience”.
The lender’s executive team is equally as passionate about modern lending as Brown, he said, and were supporting him in making sure the distribution function was accessible to as many advisers as possible.
Its flat hierarchical approach means all employees contribute to the strategy and success of the business, which Brown said was important as he did not want to be an inflexible leader.