IRDAI commission caps: Insurance brokers write to PM, FM — say proposed rules may not benefit policyholders
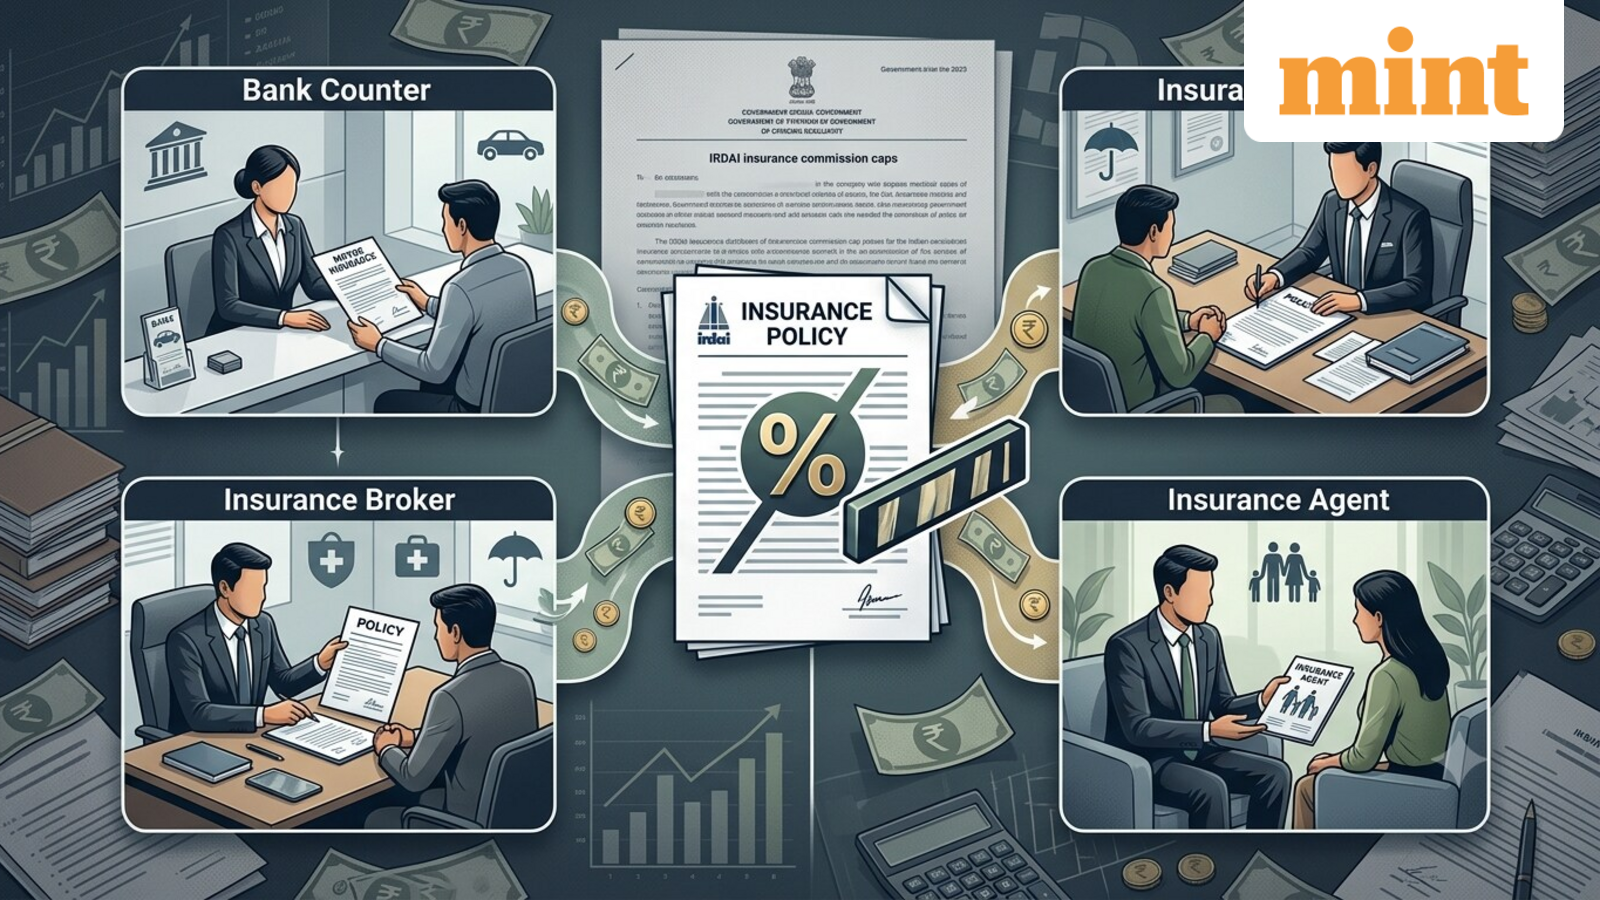
Indian insurance brokers are opposing proposed reforms by the Insurance Regulatory and Development Authority of India (IRDAI) that could cap commissions paid to banks, brokers and agents, Reuters reported on Tuesday, citing letters sent by the Insurance Brokers Association of India (IBAI) to the finance minister and prime minister.
IRDAI proposed the changes in its “Recalibrating Economics of Insurance Distribution” discussion paper released on 23 September and invited stakeholders to submit feedback by 25 October. The proposed framework seeks to link commissions to the complexity of insurance products and the effort required to sell them.
What has IRDAI proposed on insurance commissions?
Under the proposed rules, commission levels would be linked to the nature and complexity of insurance products and the work required to distribute them. Mandatory insurance covers, such as third-party motor insurance, could attract little or no commission.
The broader objective is to reduce insurance distribution costs and, ultimately, make policies more affordable for policyholders, Reuters reported.
It proposes lower commissions for products sold through “open architecture” channels, including brokers and banks, which are major distribution channels for health, motor and life insurance.
For banks and lenders selling insurance alongside loans, commissions could be capped at 2% to 5%, depending on the product, while bundling insurance compulsorily with credit would be prohibited.
For health insurance, distributor commissions at the time of purchase are proposed to be capped at 15% to 20%, with lower caps of 5% to 10% for renewals and policy portability. For motor insurance, commissions on personal accident cover could be capped at 5% to 10%.
For life insurance, first-year distributor commissions are proposed to range between 5% and 20%, depending on the policy tenure.
Why are insurance brokers opposing the proposals?
IBAI has argued that the proposed framework could shift money away from distributors and employees of insurance companies towards the owners of insurance companies, without requiring insurers to pass on any resulting savings to policyholders, as reported.
The association believes the changes could have significant consequences for the insurance distribution industry and employment.
IBAI estimates that at least 1 million jobs could be at risk over a five-year period as a result of the proposed changes. This estimate does not include salaried employees of insurance companies.
Could the changes encourage unethical practices?
IBAI has also raised concerns that tighter commission limits could encourage insurers to find alternative ways to compensate distributors.
The association warned that insurers could potentially disguise excess commissions as “marketing fees”, which it said could lead to a resurgence of unethical practices in insurance distribution.
The proposed overhaul could also create uncertainty for the sector, particularly after India allowed 100% foreign direct investment in the insurance sector, IBAI said in its letters, according to Reuters.
What is IBAI asking the government and regulator to do?
IBAI has urged IRDAI not to introduce hard caps on commissions without first publishing an impact assessment covering policyholders, employment, public sector insurers and foreign investment.
The association has also sought meetings with the finance minister and prime minister. It has asked that the existing commission framework remain in place until its scheduled review in 2028, rather than being replaced within months.
The proposals are still at the consultation stage, with stakeholders allowed to submit feedback until 25 October.
Disclaimer: This is for informational purposes only. Please check the official website for the latest updates, rules and regulatory changes.