How much debt should you hold? More debt can cushion market falls, but there is a trade-off
For investors building a long-term portfolio, the question is not just how much return they can earn, but also how much loss they can tolerate when markets fall. A portfolio with a higher allocation to debt can reduce the impact of an equity market correction, but the protection comes at a cost. Over the long term, a larger debt allocation can also lower the portfolio’s return.
A FundsIndia analysis of historical rolling returns illustrates this trade-off by comparing portfolios with different combinations of equity, debt and gold. The analysis uses Nifty 50 TRI for Indian equity, S&P 500 total returns for US equity, gold returns and a basket of low-duration and corporate bond funds for debt. The portfolios were rebalanced annually when the allocation moved beyond a 5% band.
More debt can reduce how much your portfolio falls
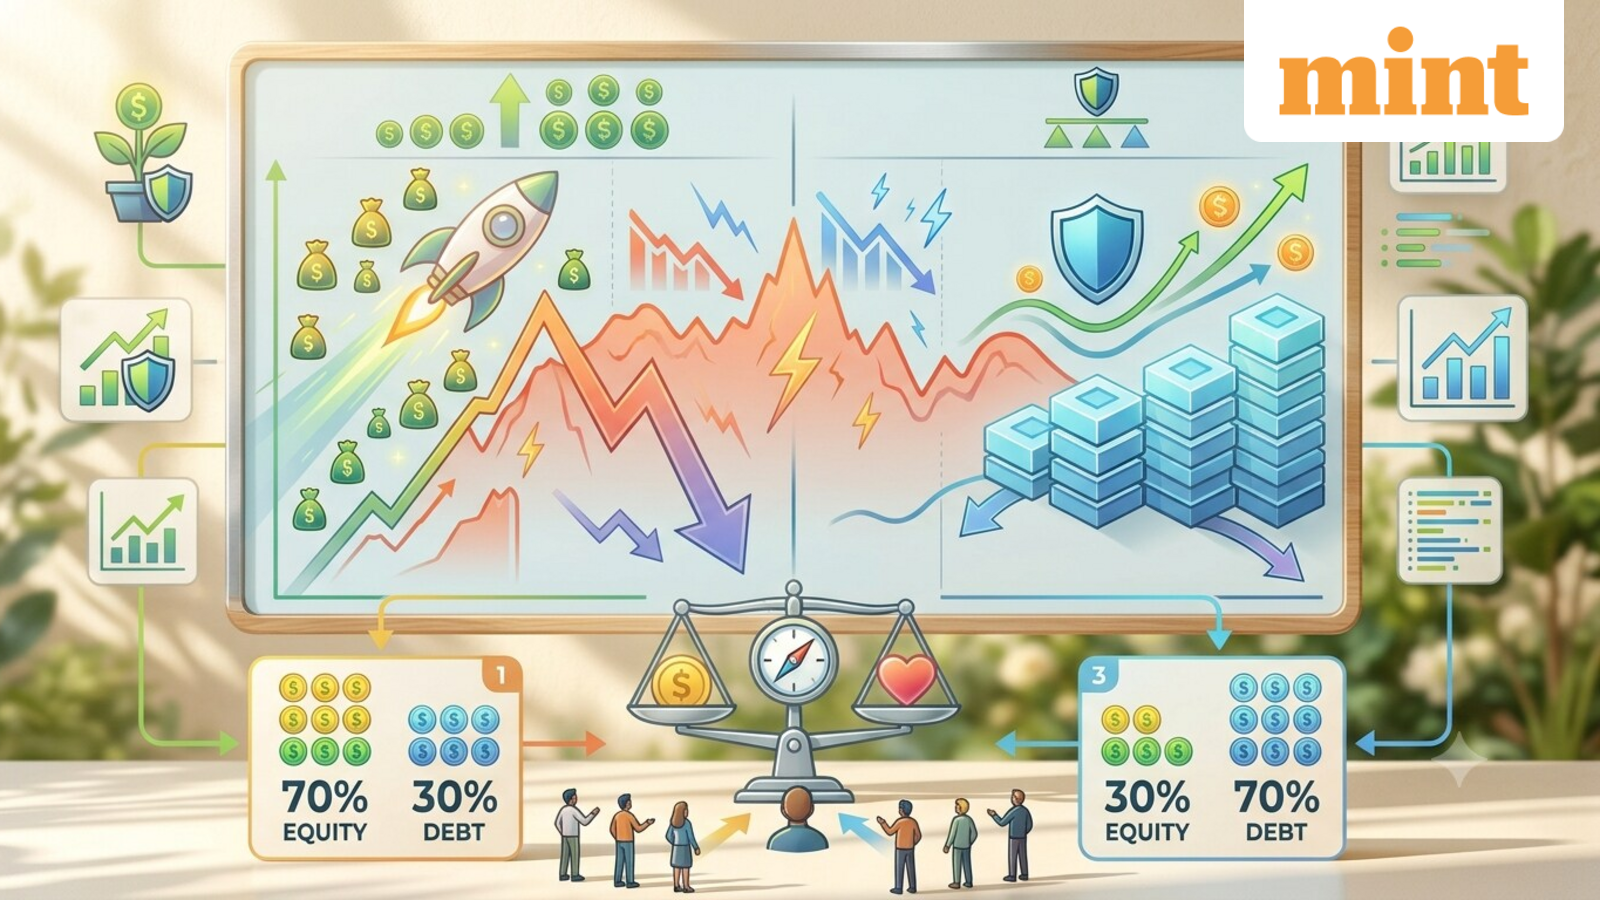
FundsIndia compared portfolios with 70%, 50% and 30% equity, with the rest allocated to debt. The results show a clear pattern. As the debt allocation increased, the portfolio’s worst historical fall became smaller, but its average return also declined.
|
Portfolio |
Average 7-year return |
Lowest 7-year return |
Highest 7-year return |
Worst fall |
| 70% equity + 30% debt | 13.8% | 7% | 26% | -40% |
| 50% equity + 50% debt | 12.5% | 8% | 21% | -27% |
| 30% equity + 70% debt | 10.7% | 8% | 16% | -14% |
| Source: FundsIndia Research, as of 31 August 2026. | ||||
The first portfolio had 70% in equity and 30% in debt. Across the rolling seven-year periods studied, it delivered an average annualised return of 13.8%. However, its maximum drawdown, or the biggest fall from a previous peak, was 40%.
When the debt allocation increased to 50%, the average return fell to 12.5%. At the same time, the maximum drawdown reduced to 27%.
With 70% debt and 30% equity, the average return fell further to 10.7%, but the maximum drawdown was only 14%.
In simple terms, an investor choosing more equity historically got greater return potential, but also had to be prepared for bigger falls. Increasing debt reduced the extent of those falls, but also reduced the return potential.
FundsIndia’s report makes the same point, noting that higher debt exposure lowers portfolio declines during market falls but also lowers long-term returns.
Adding gold changes the portfolio’s risk-return balance
FundsIndia also tested portfolios combining equity, debt and gold. One such combination was a 70:15:15 portfolio, meaning 70% equity, 15% debt and 15% gold.
|
Portfolio |
Average 7-year return |
Periods with return above 10% |
Worst fall |
| 70% equity + 15% debt + 15% gold | 15.0% | 92% | -40% |
| 50% equity + 25% debt + 25% gold | 14.2% | 81% | -27% |
| 30% equity + 35% debt + 35% gold | 13.2% | 72% | -17% |
| Source: FundsIndia Research, as of 31 August 2026. | |||
The 92% figure does not mean the 70:15:15 portfolio earned more than 10% every year. It means that across the rolling seven-year periods analysed, 92% of those periods produced an annualised return above 10%.
The same applies to the 81% figure for the 50:25:25 portfolio and 72% for the 30:35:35 portfolio.
The historical data also shows that the portfolio with more debt and gold had a smaller maximum drawdown. The 30:35:35 portfolio had a maximum drawdown of 17%, compared with 27% for the 50:25:25 portfolio and 40% for the 70:15:15 portfolio.
However, investors should not interpret these historical results as a guarantee of future returns. The analysis only shows how these allocations behaved across past rolling periods.
So, how much debt should investors hold?
The data does not point to one ideal debt allocation for everyone. Instead, it shows the trade-off investors need to consider.
More equity can provide higher return potential, but comes with larger portfolio declines. More debt can reduce the size of those declines, but can also lower long-term return potential.
For an investor who cannot tolerate a 30% or 40% decline in the value of a portfolio, choosing an allocation with less equity may make it easier to stay invested during a market correction. On the other hand, an investor with a longer horizon and a higher tolerance for volatility may be willing to hold more equity.
The important point is that the best allocation is not necessarily the one with the highest historical return. It is the one whose level of risk an investor can withstand without abandoning the investment strategy when markets fall.