History Says Johnson & Johnson Beats Medtronic. Here’s Why I’d Still Consider MDT for the Next Decade.
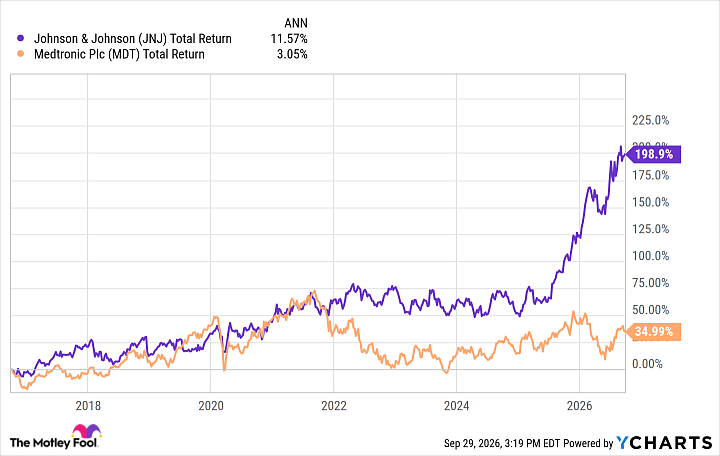
Johnson & Johnson‘s (JNJ -1.06%) stock has absolutely crushed Medtronic‘s (MDT -0.92%) over the last decade. The iconic healthcare giant has generated a nearly 200% total return over the last 10 years (11.6% annualized), compared with roughly 35% for the healthcare technology company (3.1% annualized).
However, while Johnson & Johnson’s stock was the clear winner over the past decade, I think Medtronic could be the better investment over the next 10 years. Here’s why.

Image source: Getty Images.
The breakout decision
Shares of Johnson & Johnson and Medtronic ran neck-and-neck for the first half of the past decade. However, the global healthcare behemoth started separating itself from its smaller rival in late 2021 before really taking off over the past year:
JNJ Total Return Level data by YCharts
The initial catalyst coincides with the company’s decision in late 2021 to spin off its consumer healthcare business (now Kenvue). The move has paid major dividends for shareholders by unlocking the value of its businesses. It also provided JNJ with additional capital to reinvest in the growth of its innovative medicines and MedTech divisions.
The company has made several acquisitions to expand both segments over the past few years. Notable deals include Abiomed ($16.6 billion in 2022), Shockwave Medical ($13.1 billion in 2024), and Intra-Cellular Therapeutics ($14.6 billion in 2025). These deals accelerated growth for its MedTech segment and strengthened its leadership in neuroscience and other crucial areas.

Today’s Change
(-1.06%) $-2.83
Current Price
$264.74
Key Data Points
Market Cap
Day’s Range
$264.51 – $268.48
52wk Range
$182.94 – $281.07
Volume
8.8K
Avg Vol
7M
Gross Margin
68.03%
Dividend Yield
1.99%
Johnson & Johnson is currently evaluating its next opportunity to unlock shareholder value. It’s considering a spin-off or sale of its orthopedics unit (DePuy Synthes) and is reportedly close to a $20 billion deal to sell it to a private equity firm. A sale would give Johnson & Johnson even more capital to put to work in enhancing the growth of its remaining businesses.
Repeating a winning play
Much of Johnson & Johnson’s outperformance over the latter part of this past decade stems from its decision to spin off Kenvue. That’s likely one of the factors driving Medtronic’s current strategy. Last year, the company announced plans to separate its diabetes business (MiniMed) to unlock shareholder value. It’s following the exact winning playbook of Johnson & Johnson as it initially completed an IPO of the unit and recently launched an exchange offer to finish the separation, which it should complete later this month.
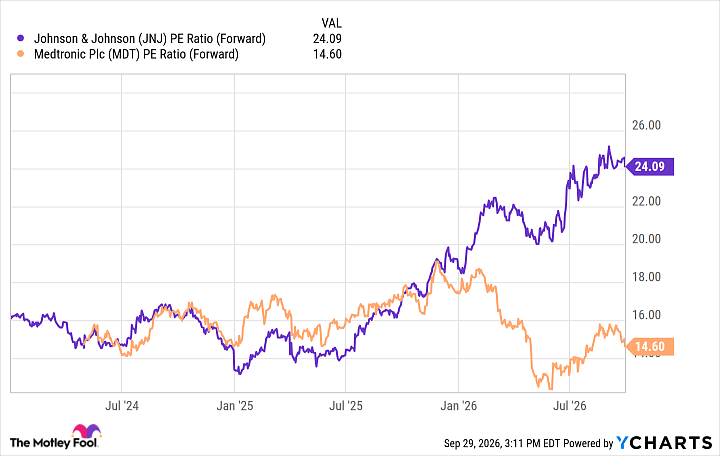
The hope is that this move will be the catalyst to start unlocking the value of its stock, which now trades at a wide discount to Johnson & Johnson:
JNJ PE Ratio (Forward) data by YCharts
That lower starting valuation is one reason why I think Medtronic could beat JNJ stock over the next decade. It’s also why the medical technology company currently has a much higher dividend yield than its larger rival (3.3% vs. 2%).
The separation of MiniMed will enable Medtronic to focus on its highest-margin growth drivers (cardiovascular, neuroscience, and medical-surgical). They’re all large and growing markets (mid-to-high single digits). That positions the company to deliver a similar growth rate as it takes market share by launching new products and continuing to make acquisitions to enhance its product portfolio. It has purchased SPR Therapeutics, CathWorks, and Scientia Vascular for nearly $1.8 billion combined this year.

Today’s Change
(-0.92%) $-0.80
Current Price
$86.29
Key Data Points
Market Cap
Day’s Range
$86.20 – $87.42
52wk Range
$73.31 – $106.33
Volume
3.5K
Avg Vol
8.8M
Gross Margin
60.56%
Dividend Yield
3.31%
The company’s growing earnings should enable it to continue increasing its dividend. Medtronic extended its streak to 49 consecutive years in 2026. While that’s well behind Johnson & Johnson’s 64-year dividend growth streak, it has Medtronic on the cusp of joining its healthcare rival as a Dividend King (a company with 50 or more years of annual dividend increases).
Medtronic’s next decade should be better than the last one
Johnson & Johnson’s spinoff strategy proved to be a meaningful catalyst for its stock over the past 10 years, enabling it to deliver much higher returns than Medtronic. I think this history foreshadows a better future decade for Medtronic because it’s following the same winning playbook. Its current combination of a lower relative valuation and a higher dividend yield should enable it to deliver a higher total return over the next 10 years, as long as its strategy accelerates growth as it did for JNJ.