Tesla Trades at 331 Times Trailing Earnings While Facing Growing Competition From China’s BYD. Is Elon Musk’s Premium Valuation Still Justified?
Tesla (TSLA +2.27%) is a battleground stock, and its highly growth-dependent valuation creates a solid foundation for the bear case. As of this writing, the stock is trading at approximately 331 times its earnings over the trailing-12-month period. That’s a lofty valuation for a company that’s currently facing some significant business headwinds.
While revenue increased 26% year over year in the second quarter, Tesla’s net income fell 5% to $1.1 billion. Tesla did see substantial demand improvement in Q2, but this was partially achieved by cost-cutting moves that drove margins lower.
In addition to competitive pressures from other automakers, CEO Elon Musk’s electric vehicle (EV) company faces a particularly significant threat from the rise of the Chinese EV maker BYD. With Tesla’s earnings under pressure, does it still make sense to pay a substantial premium for Tesla stock?
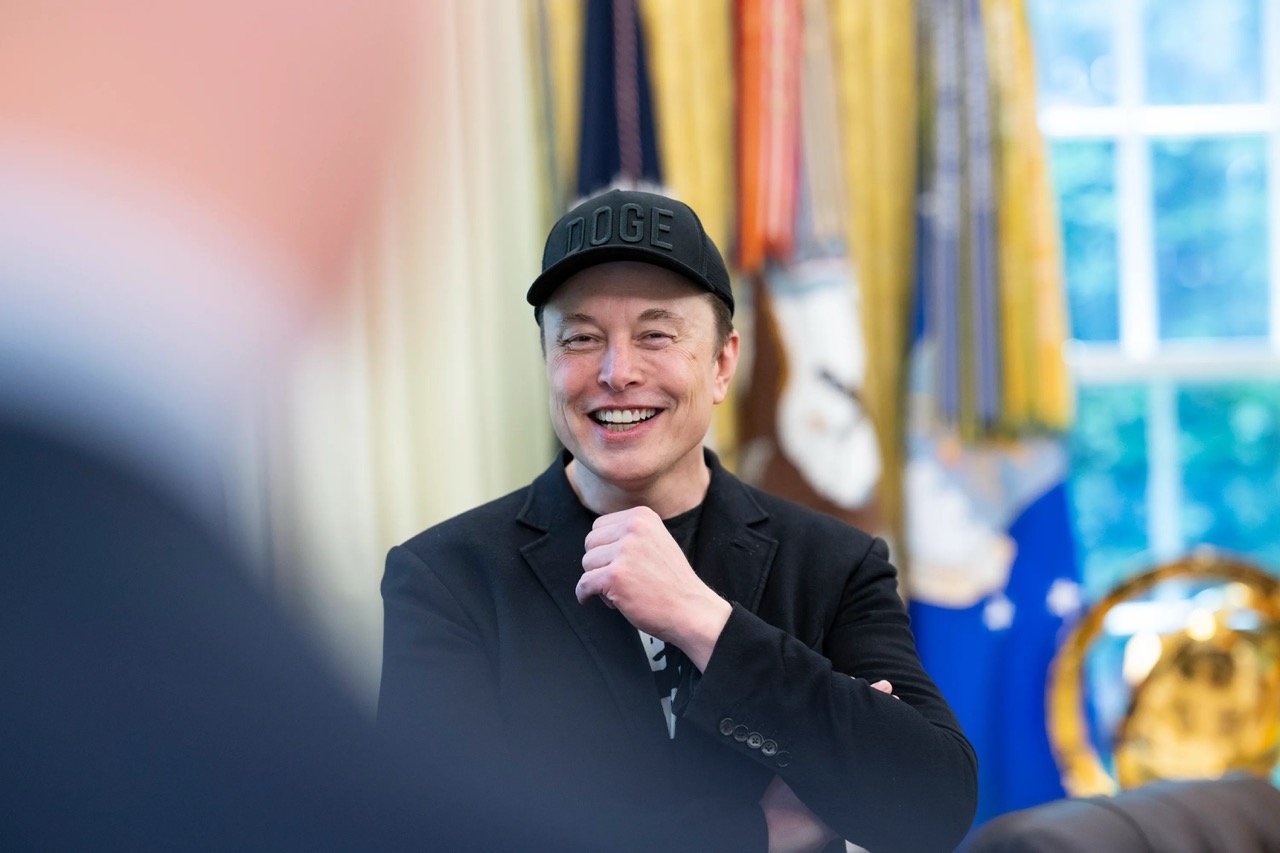
Tesla CEO Elon Musk. Image source: The White House.
Is Musk actually a visionary leader?
Musk is a controversial figure. He also has some significant failures under his belt and more than a few timeline projections for key business projects that have proven overly optimistic.
For example, Musk said in 2019 that Tesla would have 1 million of its robotaxis on the road by 2020. In 2025, Musk said that Tesla’s ride-hailing service would be operational in half the country. The company has fallen dramatically short of these goals. The much-hyped Cybertruck has also fallen far short of Tesla’s initial projections.
On the other hand, I think it’s absolutely still fair to say that Musk is a visionary leader. While he certainly has failures and a significant list of missed targets, those things can be expected to a certain extent when a person is pursuing a wide range of projects in new technology frontiers. That doesn’t mean that Musk’s misses should be completely written off, but it would also be a mistake not to give credit for the things that he and his companies have accomplished.

Today’s Change
(2.27%) $8.12
Current Price
$366.20
Key Data Points
Market Cap
Day’s Range
$363.22 – $374.12
52wk Range
$297.38 – $498.83
Volume
258.2K
Avg Vol
39.9M
Gross Margin
18.85%
Tesla stock absolutely deserves a Musk premium, but how much?
Tesla’s core auto business has recently seen a meaningful rebound in sales, but margins remain under pressure. Given the competitive risks posed by BYD and other automakers, it’s not surprising that the company has shifted its growth messaging more heavily toward projects such as its Cybercab robotaxi and Optimus humanoid robots.
The robotaxi space appears competitive, and questions remain about regulatory hurdles and whether Tesla’s fully machine-vision-based approach, which eschews LiDAR, is the best way to pursue the technology. Meanwhile, the timeline for commercializing its Optimus robot project remains unclear.
Based on the challenges facing the core auto business and the heavily growth-dependent valuation, I am not a buyer of Tesla stock right now. By conventional valuation metrics, the stock looks richly priced. On the other hand, I also wouldn’t argue against investors who are buyers who have a long time horizon and see promise in Musk’s vision. He’s an impressive, time-tested leader with some incredible execution wins, and it wouldn’t be shocking to see him prove doubters wrong again.