Renting forever vs 30-year EMI trap: Expert explains what homebuyers should compare before choosing to buy or rent
For a homebuyer, the choice between renting and buying is not simply a question of whether the monthly rent is lower than the EMI. Renting can offer flexibility and keep savings available for other needs, while buying a house brings ownership but also involves a down payment, borrowing costs and several expenses beyond the monthly loan repayment.
The decision becomes even more important when the alternative is a 20-year or 30-year home loan. A longer tenure can make the EMI more manageable, but it can also significantly increase the total interest paid over the life of the loan. At the same time, continuing to rent means dealing with rent increases and other rental costs.
There is no fixed point at which buying automatically becomes financially better than renting, said Neeraj Mahajan, chief business officer at Godrej Wealth. The comparison should instead account for the price of a comparable home, annual rent, borrowing cost, expected length of stay and the opportunity cost of the money put into the property.
Start with the full cost of owning versus renting
For example, if a ₹1 crore home is available for a monthly rent of ₹30,000, the annual rent is 3.6% of the property’s price. But Mahajan said this should not be the only calculation.
The buying side should include stamp duty and registration, rent increases, possible changes in property value and the after-tax earnings potential of the down payment.
“Buying should not depend on the expectation of a large rise in property prices to make financial sense,” Mahajan said.
Ownership also involves loan fees, interiors, property tax, maintenance and repairs. The down payment matters because that money is no longer available for other needs or investments.
Renting, meanwhile, involves deposits, brokerage and moving costs.
Mahajan said both choices should be compared over the same period, including the home’s eventual sale value, selling costs and unpaid loan. The comparison should also consider what happens if the renter invests the difference.
“Comparing just this month’s rent with this month’s EMI is too basic and leaves too much out,” he said.
A 30-year EMI may be lower, but the interest bill is much higher
The impact of loan tenure can be seen from Mahajan’s example of an ₹80 lakh home loan at an assumed 8% interest rate throughout the tenure, without prepayments.
A 30-year tenure reduces the monthly EMI by about ₹8,200 compared with a 20-year loan. However, the total interest rises by roughly ₹50.7 lakh. If comparable rent is ₹30,000, the question is whether the higher EMI still leaves enough money for other needs and emergencies.
“A longer loan reduces today’s payment; it does not make the overall cost of owning the house cheaper,” Mahajan said.
The same salary does not mean the same home-buying capacity
Two people earning the same income can arrive at different decisions because their financial circumstances may be different.
One person may have a down payment saved, no other loans and plans to stay in the same city. Another may support parents, have irregular bonuses or expect to relocate.
“Income alone is not an indicator to tell you what someone can afford,” Mahajan said.
Existing commitments, job stability and the money left after the purchase should therefore be considered. Renting can provide flexibility and keep savings available for someone with other financial commitments or plans to relocate.
When stability becomes an important part of the decision
The decision is not determined by age alone. Mahajan said economic and emotional needs can make home ownership more important at different stages of life.
Children may need continuity at school, parents may need care nearby, or a family may want to settle in one place. These can be valid reasons even if renting works out cheaper. Near retirement, owning a home without a loan can remove rent from the monthly budget, although maintenance and taxes remain.
“Age does not define when buying becomes better than renting or vice versa. It is dictated by economic and emotional needs,” Mahajan said.
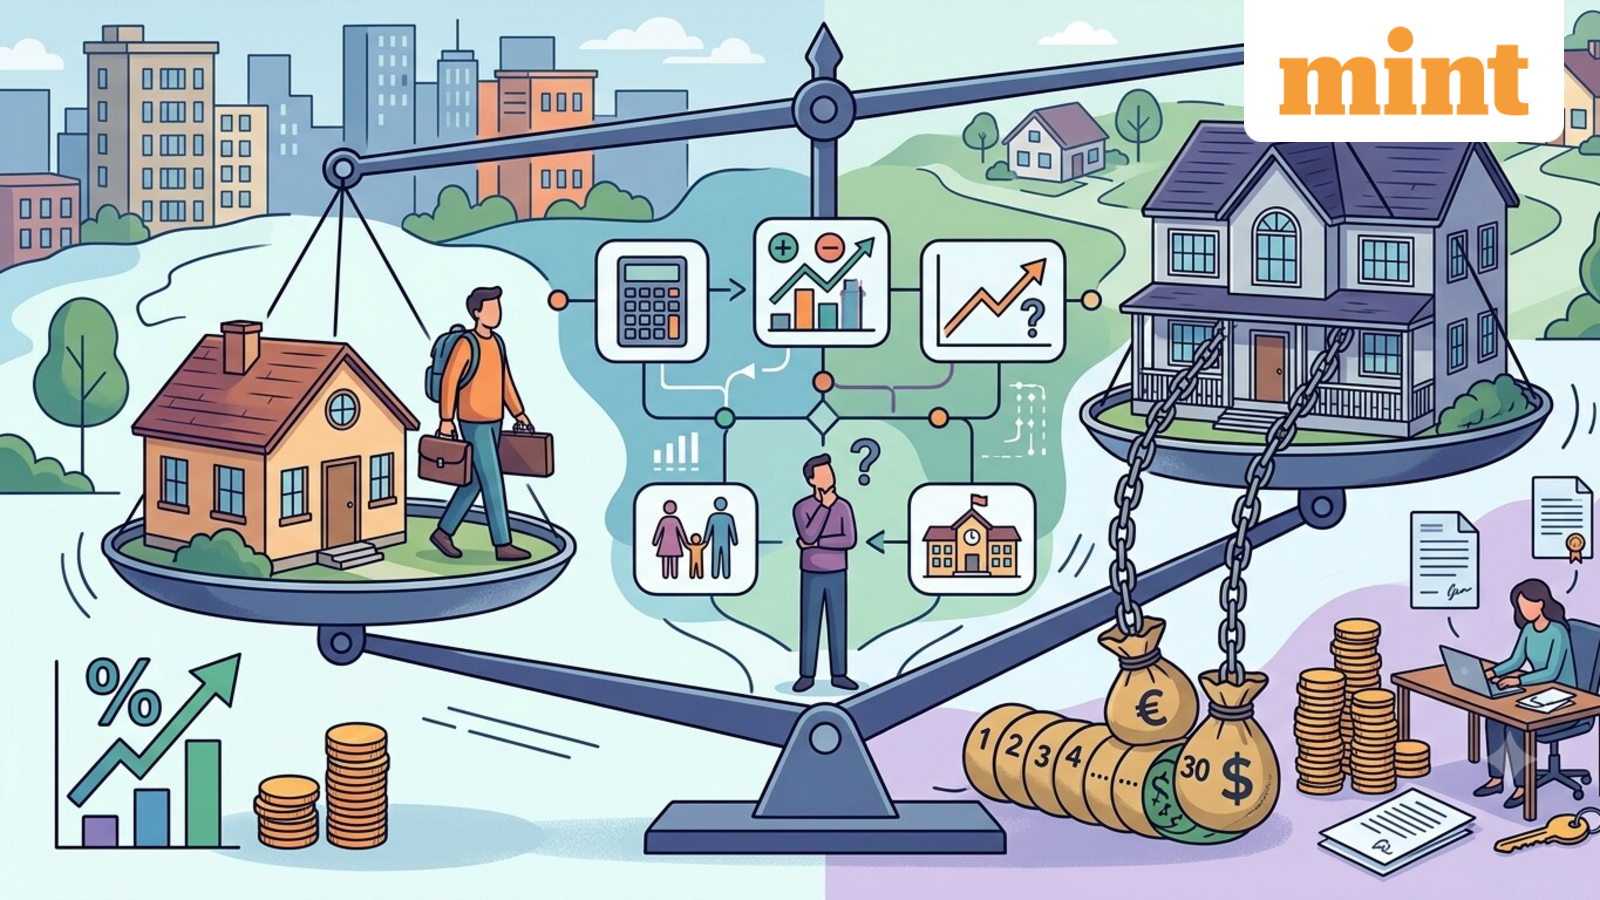
The choice between renting and buying, therefore, comes down to more than the monthly difference between rent and EMI. A buyer needs to weigh the total cost of ownership, the interest burden of the loan, the opportunity cost of the down payment and the financial flexibility that may be lost after buying. The decision ultimately depends on whether owning the house fits the person’s financial commitments and long-term need for stability.