Invested in a top-performing mutual fund? Why strong returns may not translate into similar gains for you
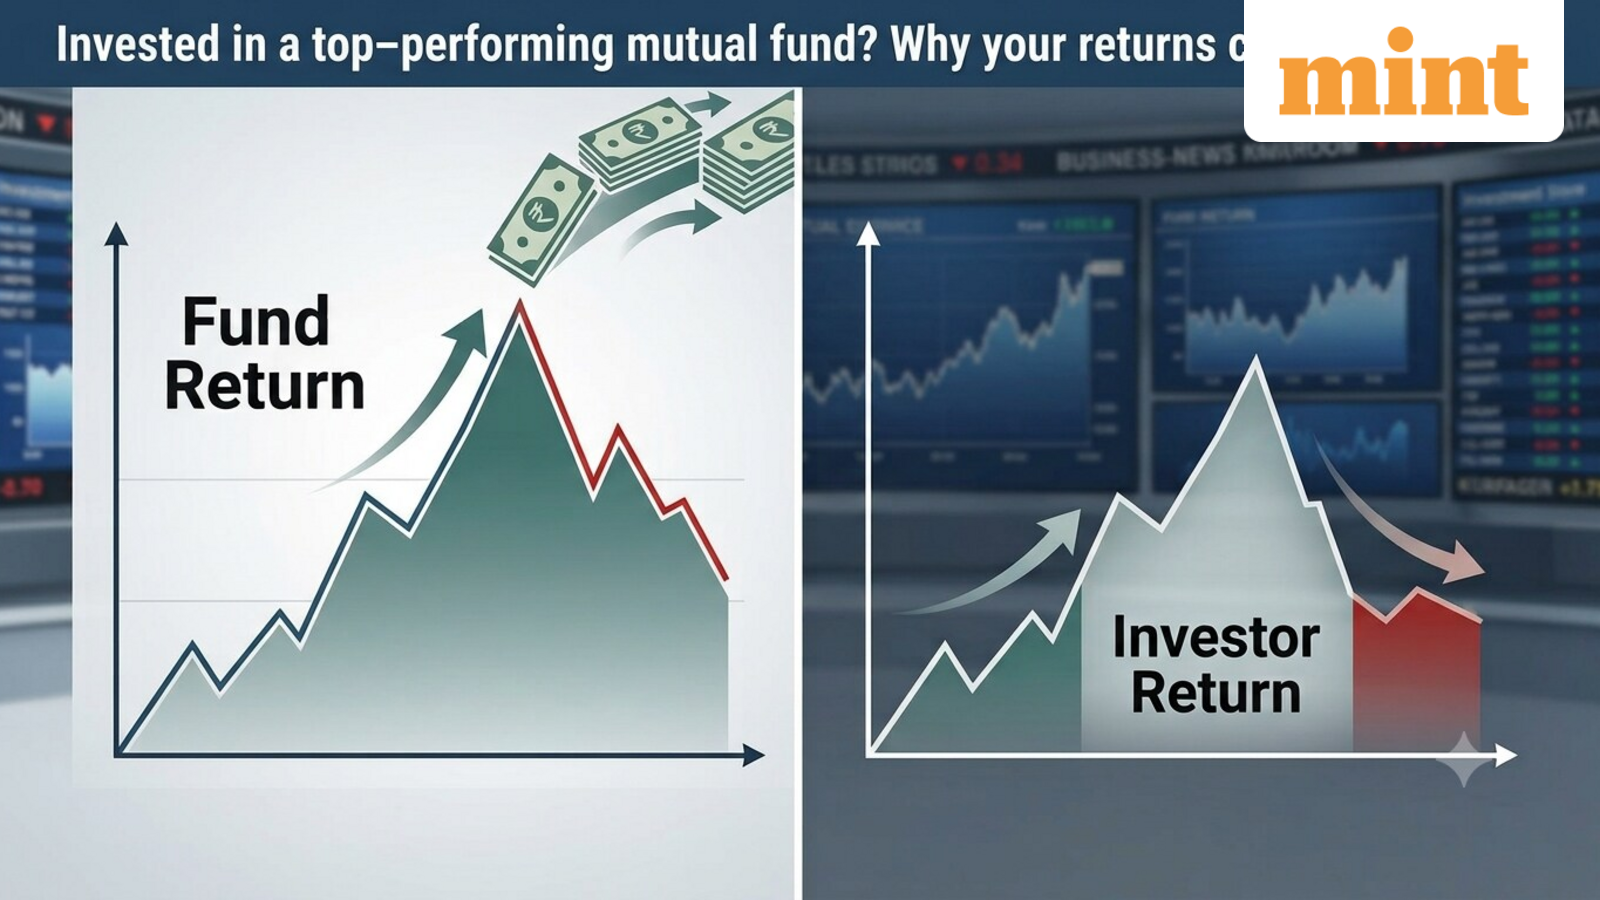
A mutual fund can deliver strong long-term returns and yet leave its investors with much lower gains or even losses if investors enter and exit at the wrong time.
A DSP Mutual Fund report highlights how the timing of investor flows can create a wide gap between a fund’s reported returns and the returns actually experienced by investors.
How can the same fund deliver different outcomes?
The report uses the example of Kinetics Internet Fund in the US, a star performer during the internet boom, to explain the difference between a fund’s reported returns and the returns actually earned by its investors.
| Period | Fund-reported CAGR | Investor CAGR | Return gap |
| Dec 1998–Dec 2003 | 8.3% | -11.9% | 20.2 percentage points |
| Dec 1998–Jul 2026 | 10.4% | 0.4% | 10.0 percentage points |
*Source: DSP Mutual Fund Report – Netra
Between December 1998 and December 2003, the fund generated a compounded annual return of 8.3%, while investors faced a loss of 11.9%.
The difference does not necessarily mean the fund itself failed. Instead, it shows how the timing and size of investors’ cash flows, when they put money into or withdrew money from the fund, can materially affect their actual returns.
The DSP report puts it this way: “The fund was not the problem. The timing of capital was.”
What happened to investor money in the Kinetics example?
The fund’s performance shows what happened. In 1998, the fund gave 196.1% returns, but the AUM was only $22 million at the end of the year. After this strong performance became visible, investors poured in money. In 1999, the fund attracted $731 million in net inflows, taking its year-end AUM to $1.15 billion. The fund returned another 216.4% that year.
But the fund then entered a sharp downturn. It lost 51.5% in 2000, followed by another 9.6% in 2001 and 23.5% in 2002. By the end of 2002, its AUM had fallen to $188 million.
This means investors had put much more money into the fund after its spectacular gains, only to see the fund fall when the amount of money invested in it was much larger.
Investors also started pulling money out during the downturn. The fund saw net outflows of $44 million in 2000, $40 million in 2001 and $89 million in 2002.
The largest monthly inflow came in April 1999, at $383 million, after the NAV had already risen more than sixfold since January 1998. In contrast, the largest monthly outflow came in December 2002, at $120 million, just before the fund returned 40.1% in 2003.
So, investors put in a large amount after the fund had already delivered spectacular returns and pulled money out after the fund had fallen. When the recovery came in 2003, much of that money had already left.
The longer period tells a similar story. From December 1998 to July 2026, the fund delivered a 10.4% annualised return, but the investor return was only 0.4%. The report says this shows that long-term compounding existed, but investor behaviour did not allow investors to fully capture it.
Can this happen in Indian mutual funds too?
The report points to the small-cap fund category in India. Between March 2013 and June 2020, the category generated a 14.8% CAGR, while investors’ CAGR was -1.6%.
| Period | Fund CAGR | Investor CAGR | Return gap |
| Mar 2013–Jun 2020 | 14.8% | -1.6% | -16.4 percentage points |
*Source: DSP Mutual Fund Report – Netra
DSP said more money flowed into small-cap funds during the bust, with ₹27,000 crore invested between January 2018 and June 2020, than during the earlier boom, when inflows stood at ₹17,000 crore between March 2013 and December 2017.
Why does investor return differ from fund return?
Fund returns are generally measured on a time-weighted basis, which shows how the fund performed independent of individual cash-flow timing. Investor returns are money-weighted, meaning they reflect when and how much money an investor actually put into or withdrew from the fund.
The report sums up the distinction: “Performance is time-weighted. Investor experience is money-weighted.”
So, instead of chasing funds after strong past performance or exiting after a sharp fall, investors should focus on their investment horizon and stay disciplined through market cycles.
Disclaimer: This is purely for educational/informational purposes and should not be taken as any sort of investment advice. Always consult a SEBI-registered advisor before making any investment decisions.