Property bought for ₹48 lakh, stamp value ₹58.7 lakh: Why ITAT cancelled ₹70,700 tax penalty
A property deal can trigger income-tax scrutiny when the price paid by a buyer is significantly lower than the property’s stamp-duty value. A recent Income Tax Appellate Tribunal (ITAT) ruling involving a ₹48 lakh property purchase shows how such a difference can lead to a tax notice, and even a penalty.
Property bought for ₹48 lakh, stamp value ₹58.7 lakh
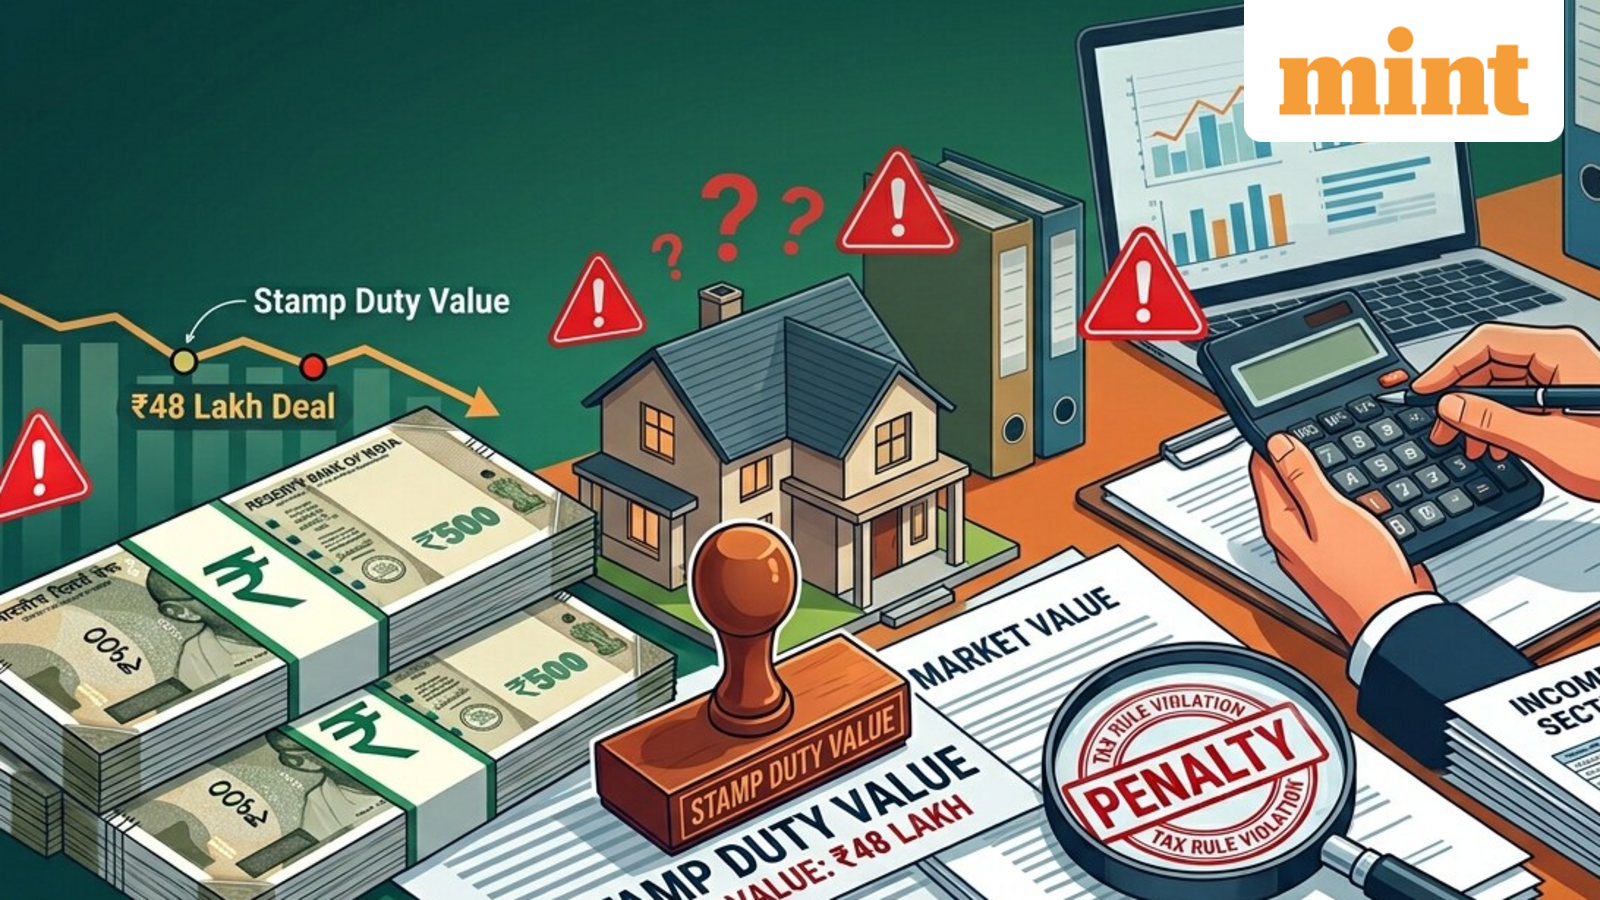
According to a report by The Economic Times, a taxpayer from Indirapuram, Ghaziabad, purchased a property for ₹48 lakh, while its stamp duty value was ₹58.7 lakh. The ₹10.7 lakh difference came under the Income Tax Department’s scrutiny.
Also, the taxpayer did not file an income-tax return for the purchase. The Assessing Officer (AO), therefore, issued a notice under Section 148, questioning the transaction. The tax department suspected that the buyer could have paid the additional amount to the seller through another mode.
In response to the notice, the taxpayer filed his ITR and agreed to pay tax on the differential amount of ₹10.78 lakh.
However, by then, the AO had already initiated penalty proceedings and imposed a penalty of ₹70,700 under Section 270A for under-reporting of income. The first appellate authority upheld the penalty.
When can the price difference become taxable?
The tax treatment of a property purchased below its stamp-duty value depends on the size of the difference and the applicable provisions, Mint had earlier reported.
In this case, the tax department treated the difference between the purchase price and the stamp-duty value as unreported income.
The issue can become particularly important when a taxpayer has other compliance gaps, such as not filing an ITR, because transaction information available with the tax department can be matched against the taxpayer’s reported income.
Why ITAT cancelled the ₹70,700 penalty
The taxpayer argued that he was semi-literate and had limited knowledge of tax laws. After receiving the reassessment notice, he disclosed the differential amount and paid the tax due.
The ITAT Delhi noted that the tax department had not placed evidence on record establishing mala fide intent to conceal income. It held that the taxpayer’s case fell within the exception under Section 270A(6)(a), which covers situations where a taxpayer provides a bona fide explanation and substantiates it by disclosing material facts.
The tribunal therefore set aside the penalty and allowed the taxpayer’s appeal.
The crucial takeaway from this particular case is that the absence of mens rea does not, by itself, invalidate a penalty under Section 270A. However, where the taxpayer satisfies the statutory condition(s) for exclusion under Section 270A(6), the penalty cannot be sustained.