Gifted assets to your spouse? Know when clubbing of income rules apply, who pays tax and how to report it in ITR
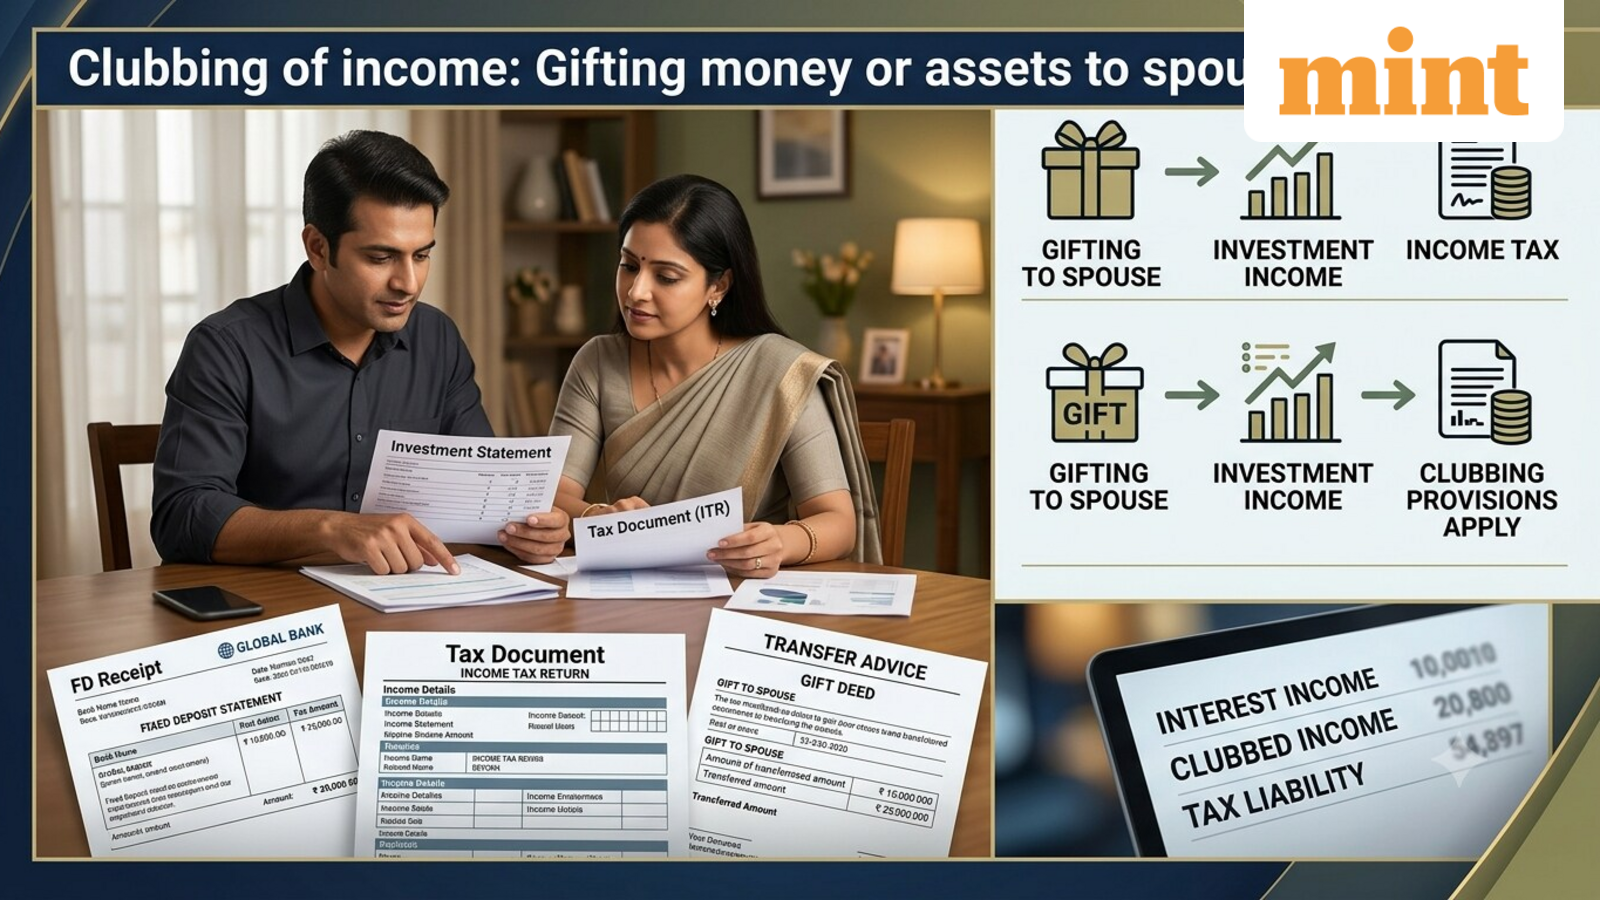
Spouses generally gift money or assets to each other, but such transfers do not automatically shift the tax liability to the recipient. The Income-tax Act contains clubbing of income provisions that can require income from assets transferred to a spouse to be taxed in the hands of the spouse who made the transfer.
Isha Sekhri, Founder, Isha Sekhri & Associates LLP, explained that the clubbing of income provisions are an anti-avoidance mechanism designed to prevent taxpayers from reducing their tax liability by transferring income-generating assets to a spouse in a lower tax bracket, while reducing the family’s overall tax liability.
When does clubbing apply between spouses?
Sekhri said the provisions generally apply when one spouse transfers money or an asset to the other without adequate consideration, subject to certain conditions.
- The asset or money is given without payment, or for less than its fair value.
- The couple is married when the transfer is made and when the income is earned.
In whose ITR should the income be reported?
Sekhri said the income arising from the gifted asset is included in the income of the spouse who originally gave it. It should be disclosed in that spouse’s ITR under Schedule SPI, with the other spouse’s PAN reported as required.
For example, if a husband gifts ₹10 lakh to his wife and she invests the money in an FD, the interest earned on that investment would be clubbed with the husband’s income and reported in his ITR (Schedule SPI shows the wife’s PAN).
The husband will pay tax on this interest, even though the FD is in the wife’s name. The transaction can still appear in her Form 26AS/AIS. The same principle can apply to dividends or capital gains from investments made with the gifted money, she explained.
Is income earned from that income also clubbed?
No. Sekhri pointed out that clubbing applies to the income directly earned from the gifted money or asset. Income earned by reinvesting that first-generation income is treated differently.
For example, if ₹10 lakh is gifted by the husband and generates ₹70,000 of FD interest. If the wife subsequently invests that ₹70,000 and earns another ₹5,000, the second-generation income is her own income and is not clubbed.
Does every transfer between spouses attract clubbing?
No. Sekhri said the tax treatment is fact-specific. If the money genuinely belongs to the spouse receiving it—for example, from their own salary, inheritance or assets owned before marriage—there is no clubbing issue.
A gift attracts clubbing, while a bona fide (genuine) loan does not. She cited the Shah Rukh Khan vs Assistant Commissioner of Wealth Tax case, where the tribunal held that an interest-free loan given to a spouse to buy an asset was not treated as a transfer for clubbing purposes.
She added that transfers made for adequate consideration (payment at fair value) can also fall outside the clubbing provision. Transfers made before marriage are also not covered.
Can such transactions trigger an income-tax notice?
Yes. Sekhri said that if one spouse funds an investment held in the other spouse’s name, it can attract an income tax notice.
For example, if a husband gifts money to his wife, and the wife earns FD interest from it, the interest may appear in her AIS. However, the husband is required to report that interest in his ITR, and if he does not do so, the mismatch can trigger a notice.
She added that the income tax department may examine:
- Information reported in AIS, TIS and Form 26AS, including FD, mutual fund and demat transactions appearing against the two PANs.
- The source and bank trail of the funds.
- Whether the income was correctly clubbed.
- Whether the transaction was a gift, genuine loan, sale, or another transfer.
A difference in tax brackets can be relevant because shifting income to a lower-tax-bracket spouse can reduce the family’s overall tax liability, which is precisely the kind of income-shifting the clubbing rules seek to address, she said.
What other transactions should taxpayers watch?
Sekhri said the provisions can also cover cases or conditions such as:
- Rental income from property gifted to a spouse.
- Salary paid to a spouse by a concern in which the taxpayer has a substantial interest, where the spouse does not possess the required technical or professional qualifications.
- Indirect or layered transfers, such as funds gifted to a mother-in-law who subsequently gifts them to the taxpayer’s spouse.
- Certain arrangements involving assets routed through an HUF, including conversion of self-owned property into HUF property followed by benefits accruing to the spouse.
What records should spouses maintain?
Sekhri recommended maintaining a clear documentary trail. For a loan, taxpayers should retain the loan agreement and evidence of interest being charged or accrued. For a gift, they should maintain the gift deed and bank records.
Taxpayers should also retain FD, demat and mutual fund account-opening documents showing the source of funds and maintain separate workings for first-generation and second-generation income.
Taxpayers should accurately complete Schedule SPI each year, including the spouse’s PAN, to reduce the risk of AIS-driven mismatches, she noted.
Disclaimer: This is only for informational and educational purposes. Please consult a qualified expert for the latest laws and regulations.