RBI eases KYC rules for FPIs, allows overseas-certified documents, here’s what foreign investors need to know
The Reserve Bank of India (RBI) has eased the documentation process for foreign portfolio investors (FPIs), allowing banks to accept original certified copies of specified KYC documents that have been certified by authorised authorities overseas. The change is aimed at making compliance easier for overseas investors without removing the underlying KYC requirements.
The amendment was issued on 18 September 2026 through the RBI (Commercial Banks – Know Your Customer) Amendment Directions, 2026 and came into effect immediately. RBI said it had reviewed the existing instructions and decided to extend to FPIs a facility that was already available to non-resident Indians (NRIs) and Persons of Indian Origin (PIOs).
FPIs can now use overseas certification route
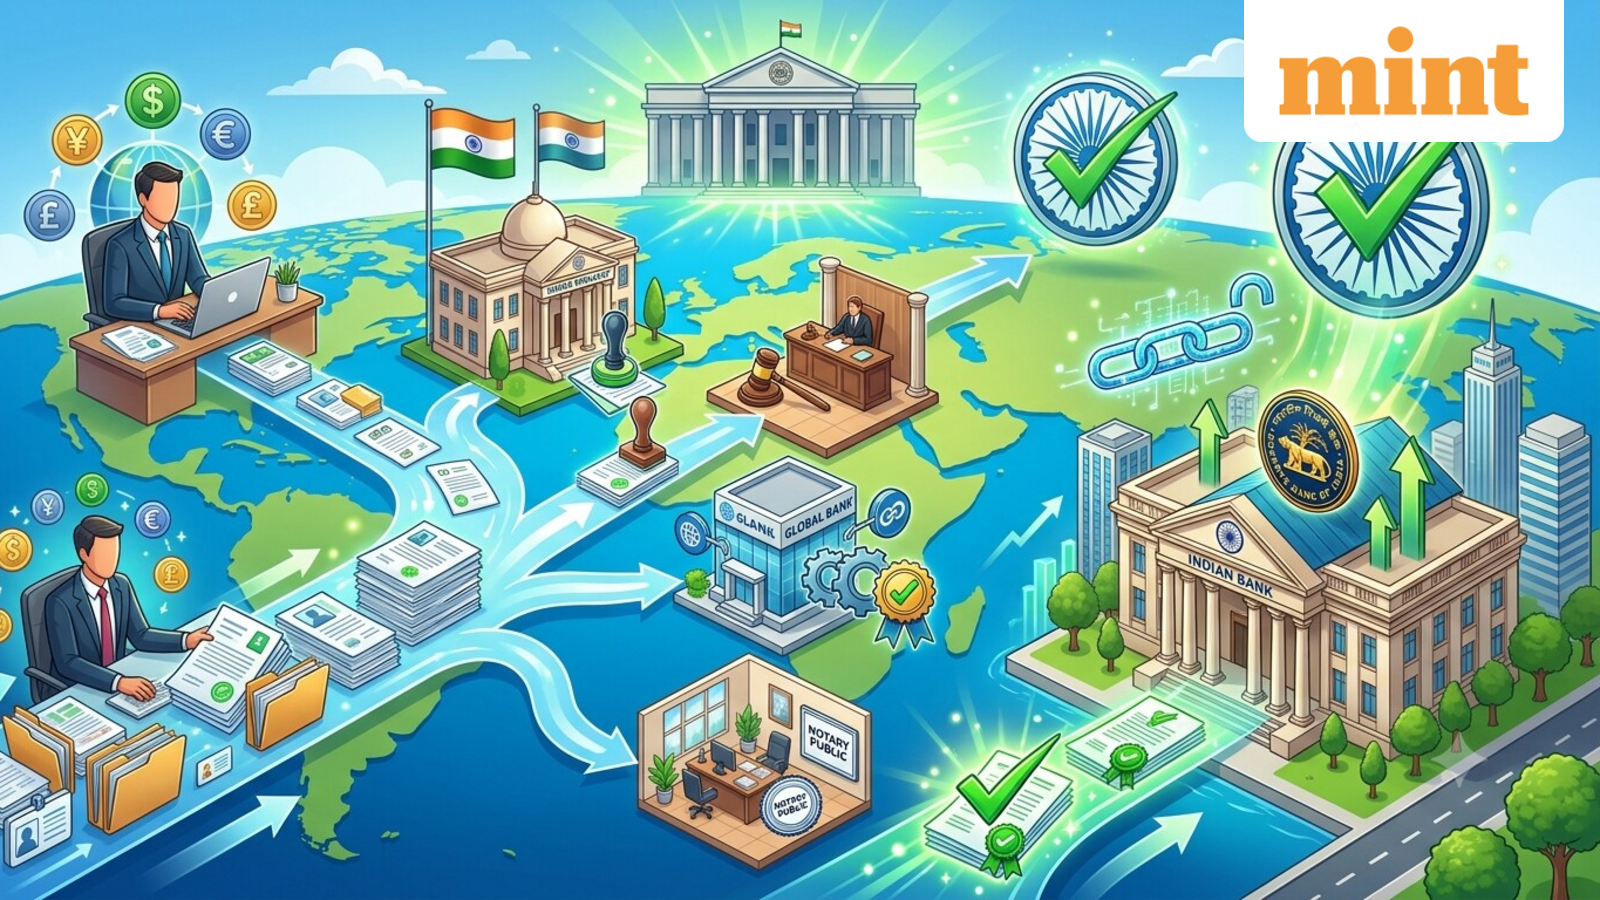
Under the amended rules, an Indian bank can alternatively obtain an original certified copy of specified KYC documents from an FPI, provided the document has been certified by one of the authorities recognised under the RBI framework.
The facility was earlier available to NRIs and PIOs. RBI has now specifically added FPIs to the provision.
The list of authorities that can certify the documents includes authorised officials of overseas branches of Scheduled Commercial Banks registered in India, branches of overseas banks with which Indian banks have relationships, a Notary Public abroad, a Court Magistrate, a Judge, or an Indian Embassy or Consulate General in the country where the non-resident customer resides.
This means an FPI based overseas does not necessarily have to arrange for the relevant documents to be certified through a process in India. It can use one of the recognised overseas certification channels before submitting the original certified copy to the Indian bank.
RBI’s amendment, however, does not change the underlying requirement for banks to conduct KYC checks on FPIs.
What counts as a certified copy under RBI rules
The amendment also retains RBI’s existing definition of a certified copy. The bank must compare the copy of the proof of possession of Aadhaar, where offline verification cannot be carried out, or the officially valid document produced by the customer, with the original.
An authorised officer of the bank must record the comparison on the copy in accordance with the applicable provisions. For FPIs, the amended provision creates an alternative route where the bank can obtain the original certified copy certified by one of the specified authorities.
The distinction is important because the change should not be interpreted as a blanket relaxation of KYC rules for foreign investors. FPIs remain subject to the applicable customer identification and verification requirements.
The amendment instead changes how the required documents can be certified and submitted.
For an overseas investor, this could make the documentation process more practical because certification can be completed through recognised authorities in the investor’s country of residence or through other specified overseas channels.
Why the change matters for foreign investors
FPIs invest in Indian securities from outside the country and may maintain their investment, banking and compliance operations across multiple jurisdictions. Physical documentation and certification requirements can therefore add operational steps to their onboarding and account-maintenance processes.
By extending the existing NRI and PIO facility to FPIs, RBI has given banks another mechanism to verify documents submitted by overseas investors.
For example, an eligible FPI could have its relevant document certified by a Notary Public abroad or through an Indian Embassy or Consulate General in the country where it is based. The Indian bank can then obtain the original certified copy under the amended provision.
The change is therefore primarily an operational facilitation, rather than a relaxation of the KYC framework itself.
For FPIs, the key takeaway is that overseas certification is now explicitly recognised as an alternative route for submitting specified KYC documents to Indian banks. The investor still needs to satisfy the bank’s KYC requirements, but the amended framework gives it greater flexibility in completing the document-certification process.