Have ₹1 crore? How to invest the amount, depending on your age; build wealth, balance growth and make the money last
Having ₹1 crore can bring relief, excitement and plenty of spending ideas. You may consider buying a bigger car, upgrading your home or taking holidays. However, the money needs a clear purpose before you spend or invest it.
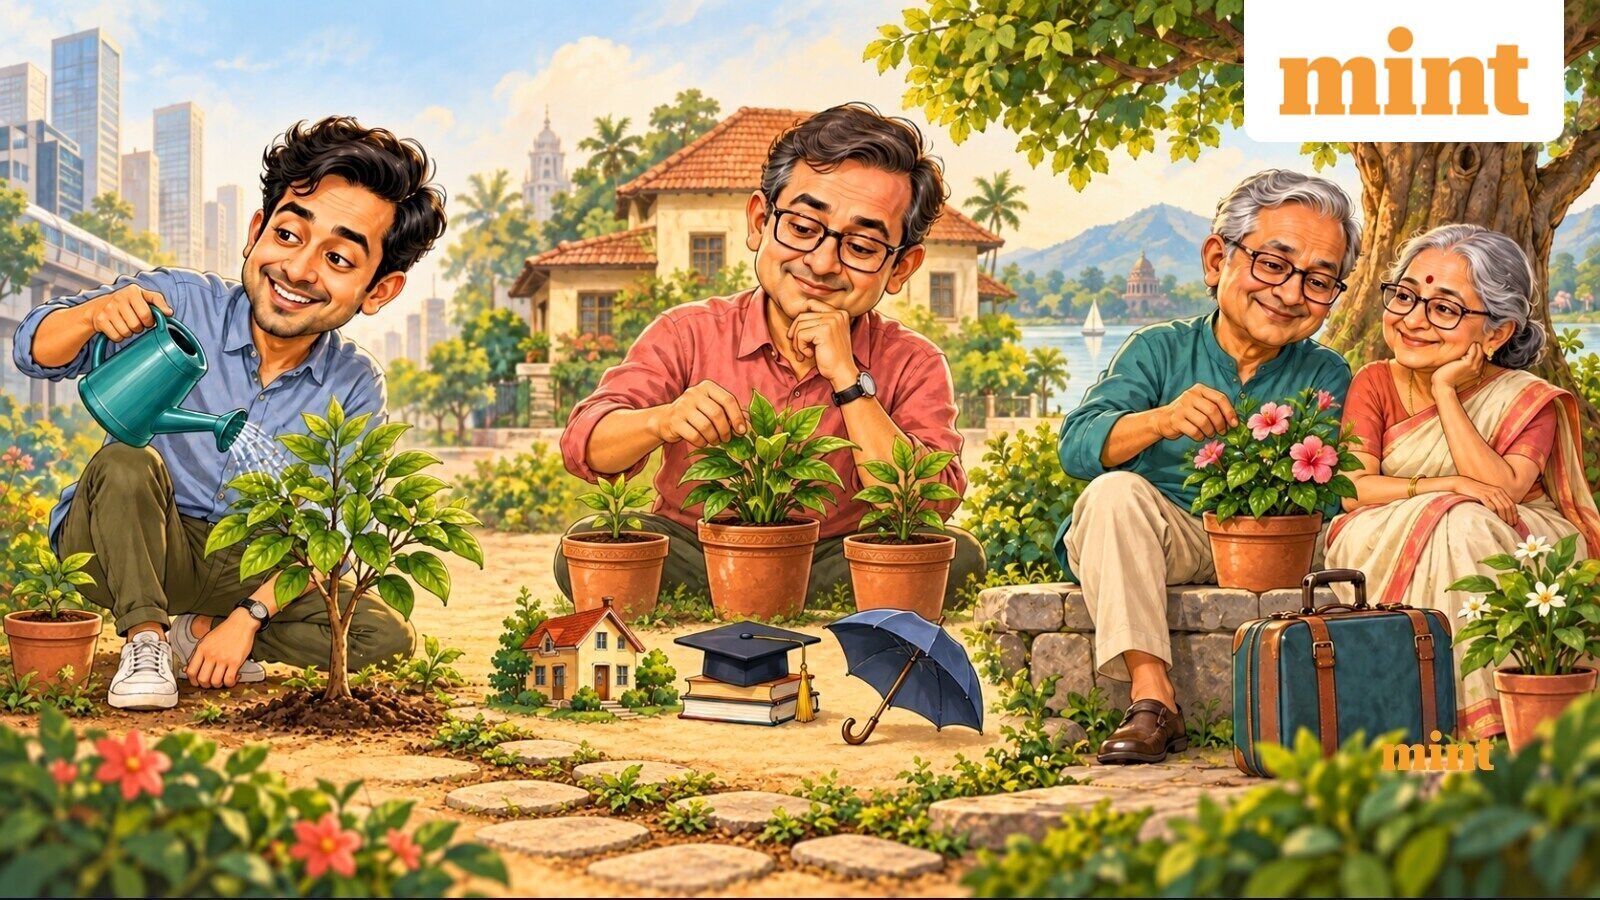
The same amount serves different needs at different stages of life. A young professional may want growth while a retired person needs a regular income. Your family responsibilities, existing savings and comfort with risk also matter.
Lakshmipathi Yelam QPFP®️, founder of My Financial Pages, explains this approach in his note. He suggests identifying your needs, wants and dreams before choosing investments.
First, list expenses that cannot be postponed or avoided. These include household costs, healthcare, loan repayments and children’s education. Keep emergency money accessible, so unexpected bills do not disturb your larger plans.
Next, decide how much you can spend on enjoyment. A holiday or family celebration is reasonable when it fits your budget. Problems begin when every purchase feels affordable simply because your bank balance looks large.
Then, consider bigger dreams, such as starting a business or becoming financially independent. Give each goal an amount and a deadline. This helps separate money needed soon from money available for longer periods.
The examples below assume ₹1 crore remains available after settling any immediate tax obligations. They illustrate possible choices, rather than fixed rules for everyone.
Ages 25-40: Build wealth
Younger investors may have several decades before retirement. That gives money more time to grow although investment returns are never guaranteed. However, youth alone does not justify taking risks with every rupee.
Someone planning a house purchase soon needs money outside unpredictable stock markets. Someone supporting parents may require larger emergency reserves than another person earning similarly.
You may divide ₹1 crore into four parts. Put ₹65 lakh towards a diversified investment portfolio for growth. Keep ₹20 lakh readily accessible for emergencies and upcoming expenses.
Reserve ₹5 lakh for opportunities, such as training or a business idea. Earmark the remaining ₹10 lakh for family commitments, protection and planned enjoyment.
The growth portion could include diversified equity mutual funds, depending on your risk tolerance. These funds invest in company shares and can lose value when markets fall. Spread investments sensibly rather than depending on a single company or a fashionable sector.
Money needed soon could remain in suitable savings accounts or bank deposits. Check withdrawal conditions before locking away funds. Your aim is growth alongside sufficient flexibility for career changes and family needs.
Ages 41-55: Balance growth
During these years, earnings may improve, but responsibilities often increase too. Children may need college fees, parents may require care, and housing loans may continue. Retirement also starts feeling closer, making mistakes harder to recover from.
Begin by separating each goal according to when payment becomes necessary. Education expenses arriving within three years need a different approach from retirement savings.
An illustrative division could allocate ₹55 lakh towards investments for future growth. Keep ₹20 lakh in relatively stable investments for approaching goals. Reserve ₹15 lakh for family requirements, emergencies and opportunities. Set aside ₹10 lakh for protection, planned spending and other priorities.
Choose the actual investments after checking your existing savings and outstanding loans. The growth portion need not follow the same mix as your younger years. Avoid exposing essential education money to sharp market falls shortly before admission deadlines.
Review health insurance and life cover where family members depend on your income. Also, check whether your emergency savings cover your household’s current expenses.
Helping children financially can be meaningful, but protect your retirement first. Decide what you can afford before promising large gifts or funding major purchases. Your future living costs deserve as much space as your family’s current needs.
55 and beyond: Make the money last
As retirement approaches, the focus often shifts towards spending from accumulated savings. Start by estimating monthly expenses, healthcare needs and income from pensions or other sources.
A person receiving a pension faces different pressures from someone relying entirely on savings. Therefore, ₹1 crore alone cannot tell you whether retirement will be comfortable.
For example, monthly spending of ₹50,000 means annual expenses of ₹6 lakh before extra costs. That calculation excludes future price increases and cannot establish a sustainable withdrawal rate. Include occasional repairs, travel and insurance premiums.
You may invest ₹40 lakh for continued growth. Another ₹30 lakh goes into relatively stable assets supporting upcoming income needs. Keep ₹20 lakh accessible for emergencies, healthcare and unexpected expenses. Allocate the remaining ₹10 lakh towards travel, family support or other personal priorities.
Suitable bank deposits and government securities can form part of the stable portion. Match maturity dates with expected spending, while checking access conditions and tax treatment. Stability does not mean every product carries identical risks or guarantees.
Avoid assuming the entire amount should stop growing after retirement. Living costs can rise over decades, reducing what the same money can buy. Some growth may remain useful, provided market fluctuations do not threaten essential spending.
Plan withdrawals carefully, and review them as expenses and investment values change. Large gifts should follow this calculation rather than precede it.
Review the plan as life changes
Age provides direction, but your circumstances decide the final investment mix. Two people aged 35 may need completely different plans despite holding identical savings.
Review your investments regularly and after major changes, including marriage, illness or retirement. Check costs, taxes and withdrawal restrictions before selecting any product. Seek personalised guidance from a SEBI-registered investment adviser when necessary.
Enjoy part of your wealth deliberately, without allowing spending to weaken essential security. A thoughtful plan gives each part a job and keeps your goals in view.