AI Agents Become the Next Payments Customer
The payments industry has devoted much effort to making sure a bot can’t pass for a customer. Agentic commerce brings a new complication, as some bots are supposed to buy things.
SolvaPay, a Stockholm-based FinTech, is building payment infrastructure for artificial intelligence agents. Its work includes machine-readable payments, usage-based billing and transactions between agents, along with controls over what an agent can spend.
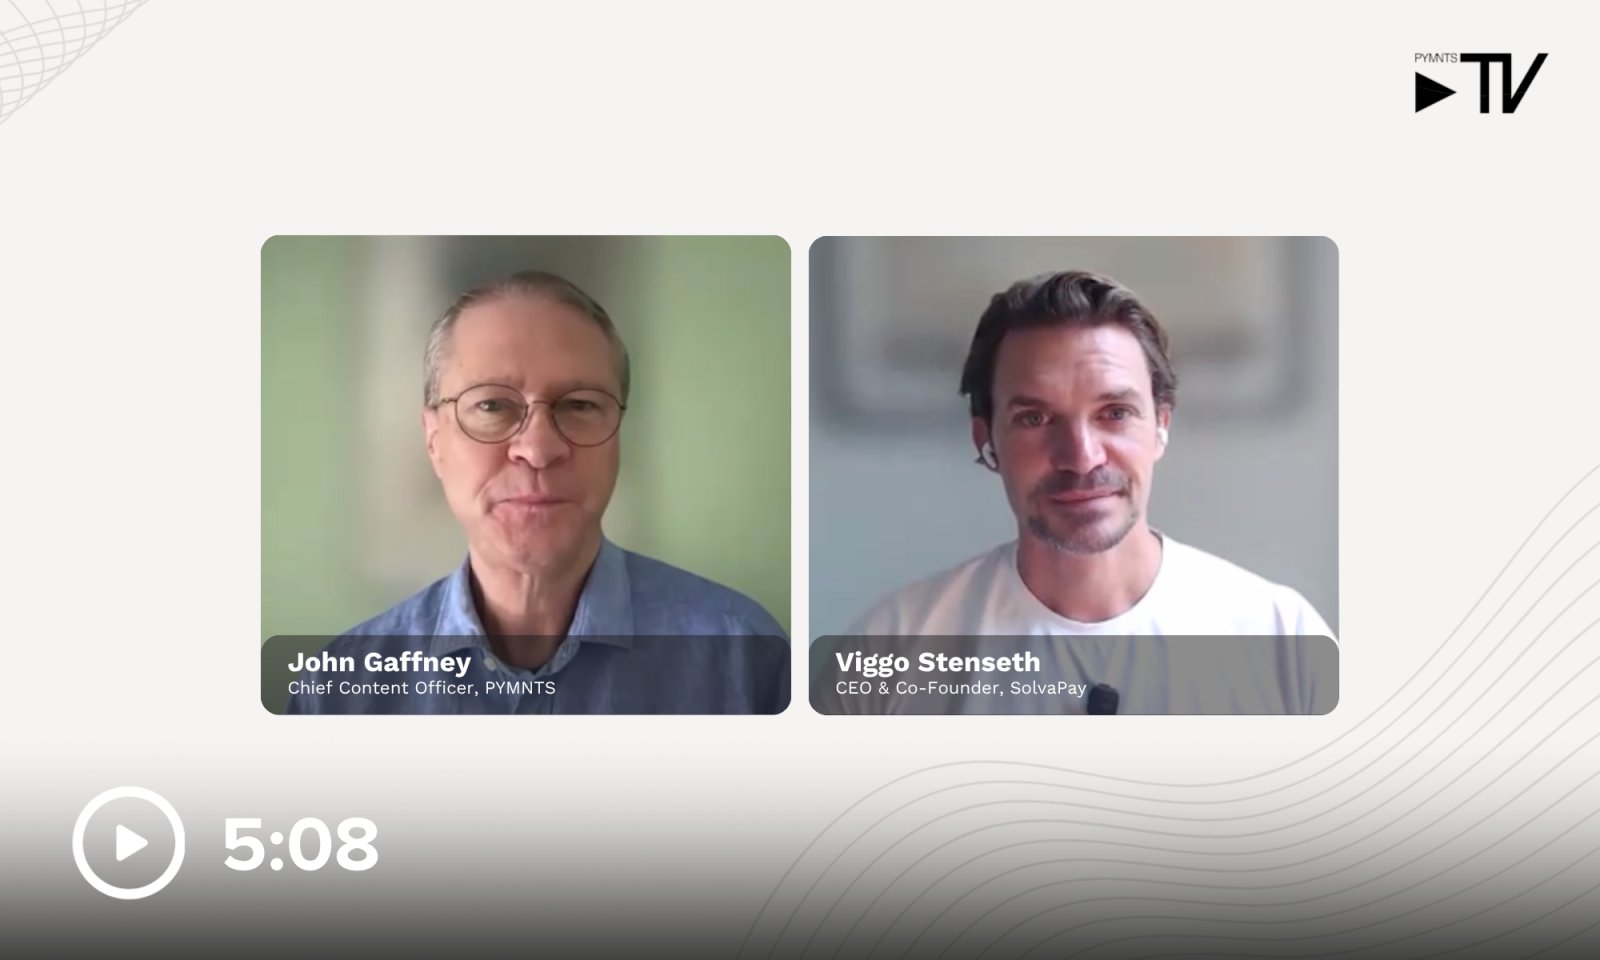
SolvaPay CEO and Co-Founder Viggo Stenseth said he sees payments as one of the places where AI’s expanding ability to act on its own runs into systems built for people. An agent can find information, use software and complete a task, but moving money still carries assumptions about who’s on the other side of the transaction.
“We built really robust systems to verify that there’s a human doing the transaction, 3DS, CVV codes, everything to prevent a bad bot from doing things,” Stenseth said. “So, it’s really ingrained in the infrastructure.”
Merchants can’t simply discard those protections because an automated buyer has permission to spend. They still need to distinguish an authorized agent from malicious software while determining whose money the agent can use and what it’s allowed to buy.
Businesses haven’t had much time to prepare for that question, Stenseth said. He recalled selling companies on websites in the 1990s, when many weren’t convinced that they needed an internet presence. It took years for widespread eCommerce to follow. Smartphones also arrived before many of the businesses and payment experiences eventually built around them.
Agentic AI has developed on a shorter timetable.
“The timer already started a couple of years ago,” Stenseth said.
Agents can now accomplish tasks autonomously, he added, but “the billing, the payment, the flow hasn’t really been solved yet.”
The difference in speed is part of what SolvaPay is trying to address. Financial infrastructure moves deliberately because payments require controls, checks and regulatory oversight. Agentic software can change more quickly. SolvaPay’s work is aimed at connecting the two without separating agent payments from the underlying financial system, Stenseth said.
One Assignment Can Generate Several Payments
Agents won’t necessarily transact the way people do.
An agent assigned a job can divide it among other agents. One might pay another agent, which can then pay several specialized agents for individual pieces of the work. What begins as one assignment can produce a series of payments underneath it. Stenseth said those transactions can run “several layers deep,” creating reconciliation questions that don’t arise in the same way when a payment can be treated as a single event.

We’d love to be your preferred source for news.
Please add us to your preferred sources list so our news, data and interviews show up in your feed. Thanks!
“We’ve built systems around, like, doing reconciliation or solving one single transaction,” Stenseth said.
If something fails farther down the chain, the question becomes whether “we roll the whole thing back” or deal only with the failed portion, he said.
Agents can also be buyers and sellers. Stenseth described a young developer interested in financial analysis who built a system that pulled information from outside data providers. The agent could communicate with those providers and pay for the information it needed. The developer could apply his own analysis, combine the data with other tools and offer what he had built to other users.
“Whatever he built for himself, he can layer that and then give it to others and resell that,” Stenseth said.
A developer in that position doesn’t need only a way to collect payment. His software may also need to pay for each component it consumes. That can favor usage-based charges for individual API calls, datasets or services rather than a conventional monthly software subscription. People building with agents are already more accustomed to usage-based billing, Stenseth said.
The money still must enter and leave the established financial system, he said. Connecting agent transactions to existing rails means dealing with anti-money laundering requirements, ledgers, licensing and security rather than treating autonomous software as a separate payments environment.
“You can’t skip steps,” Stenseth said.
For merchants, the work reaches beyond accepting a payment initiated by software. Fraud systems must recognize when automated activity is legitimate. Billing may have to accommodate software buying individual units of data or computing services. Reconciliation must account for agents that divide work among other agents and generate several related payments along the way.
Payment choice could eventually move to the agent as well. Stenseth described a consumer telling an agent to optimize spending for a goal such as earning miles. The software could then choose the card that best meets that instruction for each purchase.
Watch the full interview with SolvaPay’s Viggo Stenseth to learn more about:
- Why Stenseth said he thinks executives need firsthand experience using AI agents.
- How usage-based billing could fit services purchased and consumed by software.
- Why autonomous software is putting more pressure on security and operational controls.
For all PYMNTS AI coverage, subscribe to the daily AI newsletter.