Brent crude at $108: What does it mean for India and your investments? | Personal Finance
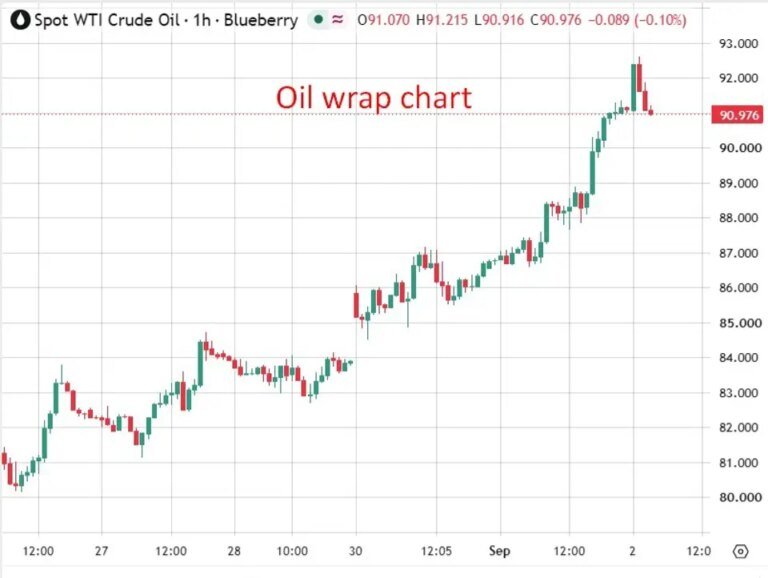
Brent crude has climbed to around $108 a barrel, raising concerns for an economy that relies heavily on imported oil.
For India, expensive crude is generally bad news. But the extent of the damage will depend on one key question: Does oil stay above $100 for months, or is this a short-lived spike?
That distinction matters.
India imported 88.6% of its crude oil requirement between April and January of FY26. When crude becomes more expensive, India has to spend more dollars to buy the same amount of oil. That can put pressure on the country’s trade balance, the rupee and inflation.
Why is expensive oil a problem for India?
Think of crude oil as an input cost for the entire economy.
Oil is used directly as petrol, diesel and LPG, but its impact goes much further. Transportation, manufacturing, chemicals, aviation and several other industries are linked to energy prices.
So, when crude rises sharply, India faces what economists call a triple-deficit problem.
“A persistent $108 Brent price would worsen the triple deficits – trade balance, the current-account deficit (CAD), and the fiscal deficit, besides, pressuring the rupee and import inflation. RBI research estimates that a $10-per-barrel oil-price increase can add roughly 49 basis points to headline inflation; alternatively, if the government absorbs the shock, it could add 43 basis points to the fiscal deficit. This causes difficult policy trade-off. Passing through the increase in petrol, diesel and LPG prices raises transport, food and manufactured-goods costs, suppressing household real incomes and consumption. Absorbing it through excise cuts or fuel subsidies protects inflation temporarily but strains fiscal arithmetic and the oil marketing companies. An average crude price of $100 could widen FY27 CAD to 1.9–2.2% of GDP, from a projected 0.7–0.8%,” said Dr. Manoranjan Sharma, Chief Economist at Infomerics Ratings.
1. The trade deficit can widen
India imports most of the crude it consumes. If the price of oil rises, the country’s import bill increases.
For example, if India continues importing roughly the same quantity of oil but the price rises from $80 to $108 a barrel, the country has to spend substantially more on imports.
That can widen the gap between what India spends on imports and what it earns from exports.
2. The current-account deficit can increase
A larger oil import bill can also push up India’s current-account deficit (CAD)—the broad measure of the country’s transactions with the rest of the world.
According to the estimates in the report, an average crude price of $100 a barrel could push India’s FY27 CAD to around 1.9–2.2% of GDP, compared with a projected 0.7–0.8%.
A higher CAD can put additional pressure on the rupee because India needs more foreign currency to pay for imports.
3. The fiscal deficit could come under pressure
The government has another choice when oil becomes expensive: allow higher fuel prices to reach consumers or absorb some of the increase.
If it tries to shield consumers by cutting excise duties or providing support to fuel companies, the government bears part of the cost.
That can put pressure on government finances.
So policymakers face a difficult trade-off:
Pass on the oil shock → higher inflation.
Absorb the shock → greater pressure on the fiscal deficit.
What happens to inflation?
This is perhaps the most immediate concern for households.
Higher crude prices can increase the cost of petrol, diesel and LPG. But the impact doesn’t stop there.
Diesel, for example, is widely used to transport goods. If transportation becomes more expensive, companies may eventually pass those costs on to consumers.
That can make everything from food to manufactured goods more expensive.
The result is imported inflation—inflation that enters the economy through more expensive imported commodities.
RBI research cited in the report estimates that a $10-per-barrel increase in oil prices can add around 49 basis points to headline inflation.
Alternatively, if the government absorbs the shock, it could add around 43 basis points to the fiscal deficit.
What does $108 oil mean for the RBI?
Higher oil prices can make the RBI’s job more complicated.
If inflation rises because of expensive crude, the central bank has less room to support growth through lower interest rates.
Higher inflation can keep interest rates and bond yields higher for longer.
That matters for businesses because borrowing becomes more expensive, while consumers may also have less money available for discretionary spending.
In simple terms, expensive oil can simultaneously hurt consumption, corporate profitability and the government’s finances.
What does it mean for the stock market?
The first reaction from equity markets is generally negative.
When Brent crossed $108, Indian shares came under pressure as investors worried about inflation, interest rates, the rupee and corporate earnings.
But the impact is not the same across every sector.
Airlines: big pressure
Airlines are among the most obvious losers from expensive crude.
A large part of an airline’s operating costs is linked to aviation turbine fuel. If fuel becomes more expensive and airlines cannot fully pass the increase on to passengers, profit margins get squeezed.
Paints and chemicals: higher input costs
Many paints and chemical companies are exposed to crude-derived raw materials.
Higher oil prices can therefore raise input costs.
Companies may try to pass these costs on through higher prices, but their ability to do so depends on competition and consumer demand.
Logistics and transportation: higher costs
Higher diesel prices can increase transportation costs for logistics companies and businesses that move goods by road.
That can pressure margins unless companies are able to pass the additional cost to customers.
Cement and consumer companies: indirect pressure
The impact on cement and consumer companies is less direct but can still be significant.
Higher transportation and energy costs can increase operating expenses. At the same time, higher inflation can reduce consumers’ purchasing power.
If households have to spend more on fuel and food, they may have less money to spend on other goods.
“The immediate market reaction is risk-off: Indian shares fell sharply as Brent crossed $108 amid concern about inflation and global interest rates. Higher crude compresses margins for airlines, paints, chemicals, logistics, cement, consumer companies and downstream oil marketers if retail prices remain controlled. It can also delay earnings recovery, raise bond yields, weaken the rupee and prompt foreign portfolio outflows—reducing valuation multiples,” said Sharma.
Which companies could benefit?
Oil producers such as ONGC and Oil India can benefit from higher crude prices, because higher oil realisations can increase their revenue and profitability.
However, the impact on refiners is more complicated.
Refining companies can benefit when the difference between the price of crude and the price of refined petroleum products—the refining margin or product crack—is favourable.
For producers, higher crude prices can be positive. For refiners and fuel retailers, the impact depends on margins, product prices and how much of the higher cost can be passed through.
“Selective producers, such as ONGC and Oil India, however, gain from higher realisations; refiners may benefit only if product cracks and pricing freedom offset cost pressure. Renewable-energy, electric-mobility and domestic gas themes may attract longer-term interest,” said Sharma.
What about the rupee?
Oil is India’s largest import item, so a sustained increase in crude prices means Indian companies and the country as a whole need more dollars to pay for imports.
That can put pressure on the rupee.
A weaker rupee can, in turn, make other imports more expensive, creating another channel through which inflation can enter the economy.
Could foreign investors pull money out?
Potentially, yes.
A prolonged oil shock can make investors more cautious about emerging markets such as India.
If investors expect higher inflation, higher interest rates, weaker corporate earnings and a weaker rupee, they may reduce their exposure to Indian equities.
That can result in foreign portfolio outflows and put additional pressure on stock valuations.
However, this does not mean every rise in crude automatically triggers a sustained market sell-off. The duration of the oil shock and the broader global risk environment matter.
“$108 is not ipso facto a macro crisis. India has relatively low inflation, a CAD of 0.8% of GDP in H1 FY26 and substantial foreign-exchange reserves, which offer buffers. Yet if oil remains above $100 for several months, or shipping through West Asia is disrupted, the growth-inflation trade-off would significantly worsen,” said Sharma.