Tilray Just Posted Record Quarterly Revenue of $257 Million. So Why Did Its Cannabis Sales Shrink?
Tilray Brands (TLRY -4.17%) reported record first-quarter fiscal 2027 revenue of $257.1 million, up 23% from $209.5 million a year earlier. Gross profit also reached a Q1 record of $77.5 million, increasing 35%, while gross margin improved from 27% to 30%.
Those are encouraging numbers for a company that has spent years expanding beyond cannabis. But there’s a catch. Despite reporting record overall revenue, Tilray’s cannabis business struggled. Net cannabis revenue declined 13% year over year, from $64.5 million to $56.1 million.
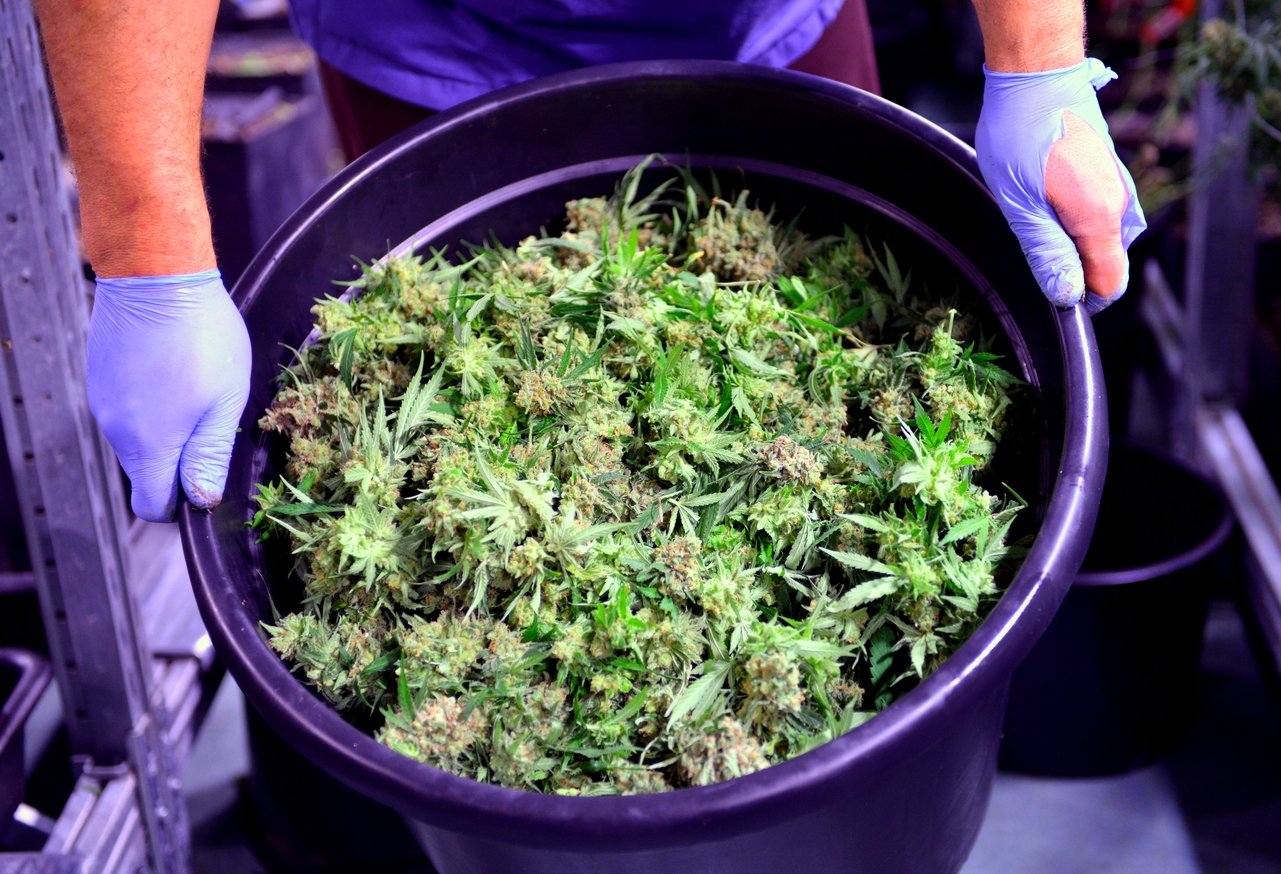
Image source: Getty Images.
Canada’s cannabis market remains a problem
Most of the weakness came from Canada. Adult-use cannabis revenue declined 16% to $53.6 million, while medical cannabis revenue fell 23% to $4.7 million. Wholesale cannabis revenue also dropped sharply, from $4.2 million to less than $700,000.
International cannabis sales provided some relief, increasing 21% to $16.2 million. However, that growth wasn’t enough to offset the decline in Canadian sales. After deducting $19.1 million in cannabis excise taxes, Tilray reported total net cannabis revenue of $56.1 million.
Beverages are driving Tilray’s growth
Tilray’s beverage business generated $101.5 million in quarterly revenue, an 82% increase from $55.7 million a year earlier. Much of that increase reflected the acquisition of BrewDog, which expanded Tilray’s beverage operations. Beverage gross margin also improved from 38% to 41%.
Beverages now account for approximately 39% of Tilray’s total revenue. Cannabis contributes just 22%, down from 31% a year earlier. So it’s clear that Tilray is increasingly becoming a diversified beverage, pharmaceutical distribution, and cannabis company rather than a business primarily dependent on marijuana sales. Pharmaceutical distribution revenue increased 14% to $84.3 million, while wellness revenue remained relatively unchanged at $15.3 million.
Record revenue hasn’t translated into profitability
Despite higher revenue and gross profit, Tilray reported a quarterly net loss of approximately $40 million. Adjusted EBITDA declined from $10.2 million to $9.2 million. Free cash flow was negative $27.4 million, compared with negative $10.6 million a year earlier.
TLRY Tilray Brands
$2.53-$0.11 (-4.17%)
NASDAQ · As of 4:00 PM ET 10/30/26
That said, the balance sheet did improve. Tilray ended the quarter with approximately $221 million in cash, restricted cash, and marketable securities and reduced outstanding debt by $42 million during the fiscal year. Management also reaffirmed its fiscal 2027 adjusted EBITDA guidance of $68 million to $75 million.
Is Tilray stock worth buying?
Tilray’s diversification strategy is generating substantial revenue growth, particularly in beverages and pharmaceutical distribution. Higher gross margins also suggest the company is making progress improving its product mix. But cannabis sales are still declining, adjusted EBITDA slipped, and free cash flow remains negative.
If you’re expecting Tilray to capitalize on expanding global marijuana markets, international cannabis growth offers some encouragement. However, the company’s latest results show that its strongest growth is currently coming from businesses outside the cannabis sector. So until Tilray demonstrates sustained profitability and stabilizes its core cannabis operations, record revenue alone isn’t enough to establish a convincing bullish case.