Tokenized bonds vs traditional bonds: How India’s new digital system changes bond trading and settlement for investors
India’s bond market is entering a new phase with the introduction of tokenized bonds, a digital system designed to make bond issuance, trading and settlement faster. Unlike traditional bonds, which rely on multiple intermediaries to complete transactions, tokenized bonds use blockchain-based technology to record ownership and settle payments.
The new system has already seen its first issuances, with REC raising ₹500 crore, Larsen & Toubro (L&T) issuing another ₹500 crore and IIFL raising ₹25 crore. Together, these three issuances amount to ₹1,025 crore, according to the July-September 2026 edition of PPFAS’s quarterly magazine, The Tortoise Lens.
In the report, Mansi Kariya, Associate Vice President and Fund Manager, Debt, at PPFAS Mutual Fund, explains how tokenized bonds work, how they differ from conventional bonds and what the transition could mean for investors.
Tokenized bonds vs traditional bonds: What changes for investors?
Tokenized bonds are essentially conventional debt securities issued and managed through digital technology. Their underlying financial characteristics remain unchanged.
According to Kariya, the coupon rate, credit rating, maturity payments and legal obligations of tokenized bonds remain identical to those of traditional bonds. The primary difference lies in how ownership is recorded, transactions are executed and payments are settled.
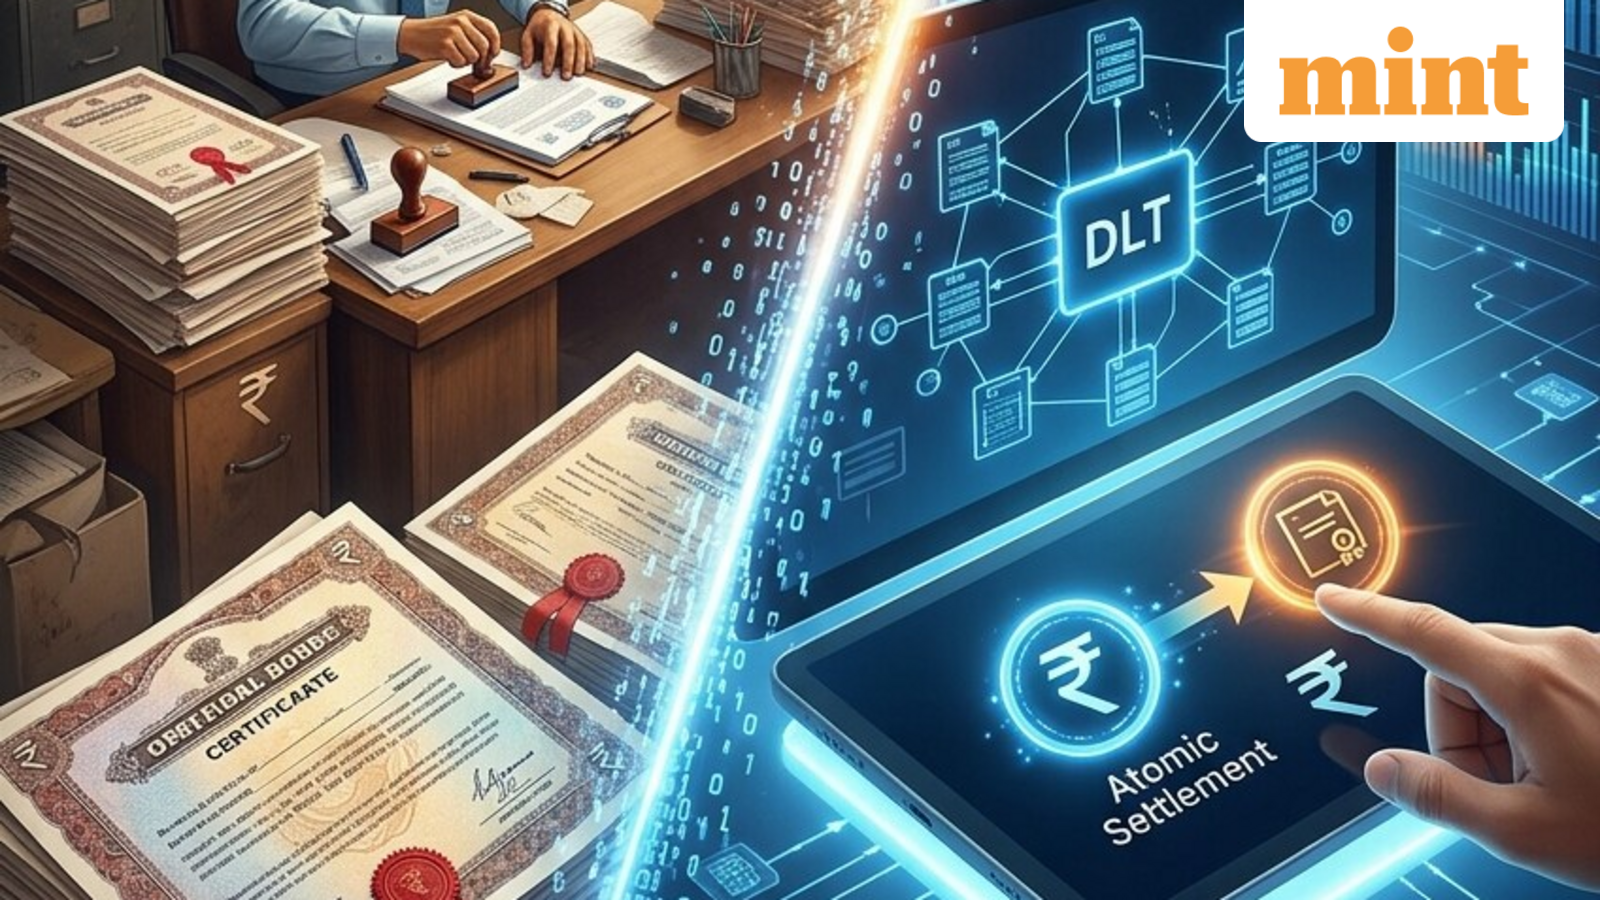
In the conventional system, corporate bond transactions involve depositories, exchanges, clearing corporations and other intermediaries. The report notes that the traditional process of listing bonds and enabling secondary-market trading typically takes two to three days.
Tokenized bonds, however, operate on blockchain-based Distributed Ledger Technology (DLT), which records transactions digitally. Under the new framework, bonds are issued through a regulatory sandbox enabled by the Securities and Exchange Board of India.
The system is designed to reduce the time and complexity involved in issuing and transferring securities. For investors, this could eventually mean faster transactions, more efficient settlement and reduced dependence on multiple intermediaries.
However, tokenization does not eliminate the credit risk associated with the bond issuer.
How does India’s digital bond settlement system work?
One of the biggest changes is the use of the Reserve Bank of India’s central bank digital currency (CBDC), commonly known as the digital rupee, for settling transactions.
According to the PPFAS report, tokenized bonds use a mechanism called the Unified Market Interface (UMI), which enables the transfer of securities and payments to happen simultaneously. This process is known as atomic settlement.
Under atomic settlement, either both parts of a transaction are completed or neither takes place. For example, when an investor purchases a tokenized bond, the transfer of the bond and the corresponding payment are designed to occur together.
This reduces the risk of one party transferring money or securities without receiving the other side of the transaction. The technology can also automate certain activities, including coupon payments and bond redemptions.
According to Kariya, bond terms can be encoded into smart contracts, allowing payments to be executed automatically based on the ownership records maintained on the digital ledger.
The report suggests that these changes could make bond issuance, listing and settlement more efficient.
What is Demat 2.0, and will investors need a new account?
Another important development is Demat 2.0, the digital account structure used to record ownership of tokenized bonds. According to Kariya, Demat 2.0 is an extension of the existing demat account framework rather than an entirely separate system.
The report states that investors will not need to complete a fresh know-your-customer (KYC) process simply to access this account structure. Tokenized bonds will also remain visible through the depository interfaces investors already use.
However, participation in the tokenized bond pilot requires a CBDC wallet with a bank because settlement takes place through the digital rupee. Retail investors cannot yet participate in the pilot, which is currently restricted to institutional investors, according to the report.
The longer-term objective is to digitize the entire lifecycle of a bond, including issuance, ownership records, trading, settlement, interest payments and redemption.
When will tokenized bonds become available for trading?
While the initial issuances mark an important development, the secondary market remains a key challenge.
According to the PPFAS report, tokenized bonds are expected to begin secondary-market trading after three months through the existing Request for Quote (RFQ) platform.
However, the success of the system will depend on whether sufficient buyers and sellers participate.
Kariya identifies liquidity as one of the biggest challenges facing the new framework.
Other concerns include interoperability between existing and new systems, investor familiarity with the technology and the ability of market infrastructure to support the transition. The report also notes that India is not the first country to experiment with tokenized bonds.
Hong Kong, Switzerland and Singapore have already introduced initiatives involving digital bond issuance and settlement. What distinguishes India’s approach is its use of regulated depositories and central bank money rather than relying on third-party stablecoins.
For investors, the biggest potential benefit is a more efficient bond market where transactions can be completed with fewer operational delays. However, faster settlement does not automatically translate into higher returns or lower investment risk.
The creditworthiness of the issuer, coupon rate, maturity and liquidity will remain important considerations when evaluating any bond.
India’s tokenized bond framework is therefore a significant change in how debt securities are issued and traded, but its broader benefits for retail investors will depend on how successfully the system moves beyond the institutional pilot.