HDFC Bank launches electric car loan with separate battery and vehicle repayment tenures – key features
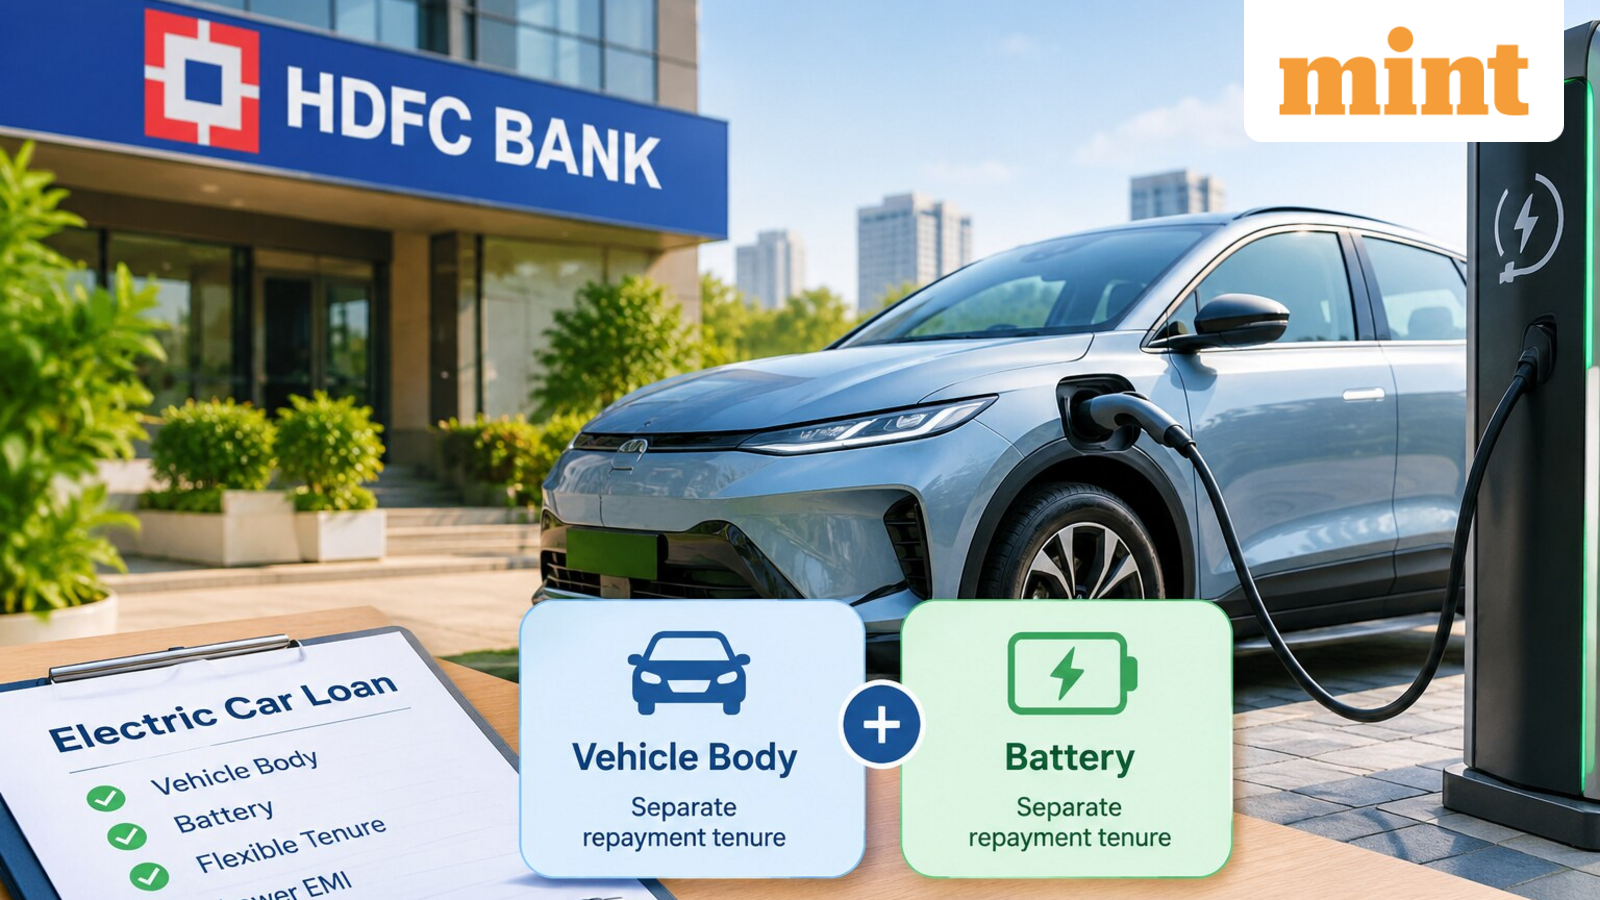
HDFC Bank has introduced a new electric car loan that lets borrowers finance the vehicle’s body and battery separately, giving them more flexibility and clarity in managing their equated monthly instalments (EMIs).
The country’s largest private-sector lender is offering the Flexi (Green) electric car loan to address the high upfront cost of electric vehicles (EVs), largely driven by expensive batteries.
How does HDFC Bank’s electric car loan work?
Under the new structure, borrowers can choose separate repayment periods for the body and the battery. The battery component can be repaid over a longer tenure, allowing customers to tailor their overall EMI outgo.
According to the bank, this can keep the battery-related EMI comparable to the running cost of a conventional internal combustion engine (ICE) vehicle. It also fits with emerging battery subscription models, which aim to reduce the upfront cost of buying an EV.
Arvind Vohra, Group Head, Retail Assets and Rural Banking at HDFC Bank, said the product is meant to support India’s growing electric mobility market and make EV ownership more cost-effective and convenient.
EV adoption in India: What lies ahead?
HDFC Bank expects electric passenger cars to account for 15-20% of the market by 2030, up from about 7% now. Government incentives, better battery technology and a wider range of models are expected to support this shift. The government’s goal of 30% electric mobility by 2030 could also accelerate the transition to cleaner transport.
The new loan structure permits prospective EV buyers another financing option. Still, customers should compare the total borrowing cost, monthly repayment burden, and battery-related terms with those of conventional car loans, as well as their long-term financial objectives, before deciding whether the loan offering suits their budget.
If you have doubts, consult a certified financial advisor so the loan stays aligned with your long-term goals.
Disclaimer: This article is for general information only and should not be considered financial advice. Borrowers should review HDFC Bank’s latest loan terms, interest rates, repayment tenures, processing fees and other applicable charges before applying, and assess the total borrowing cost against their financial circumstances.