Inside the rise and rise of reverse mortgages in Canada
That means not just rate, but also debt load, cashflow, and longer-term needs. “We have a bigger responsibility, more than ever, to not just be their mortgage broker [with a] best-rate scenario – but more of that strategy, financial planning,” she said.
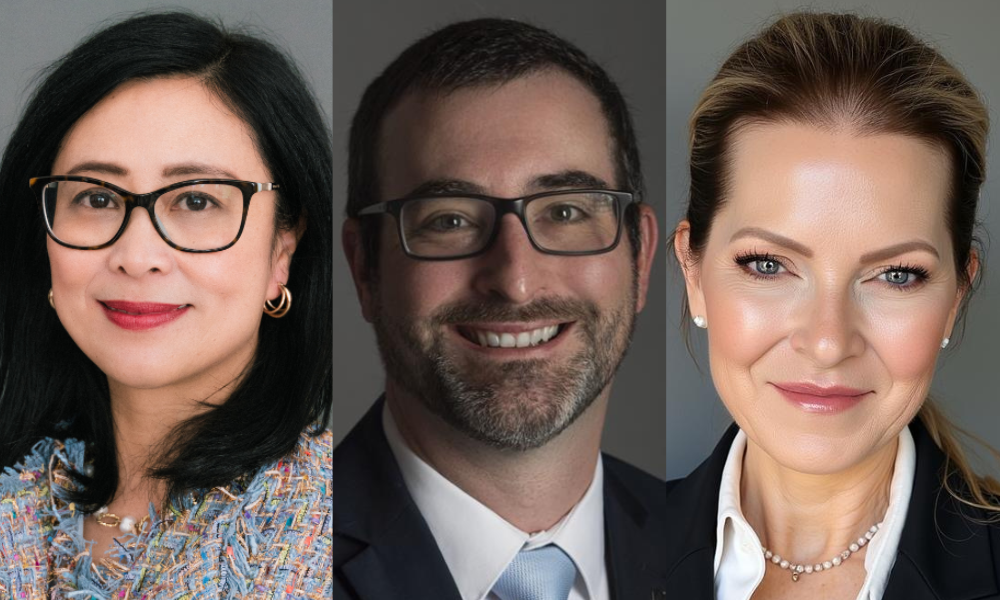
Christine Xu (pictured, top left), founder of Moneybroker Canada and a 26-year industry veteran, told CMP she’s witnessed the demand firsthand. She’s been running reverse mortgage seminars for clients – and each one fills within a day, an “overwhelming” level of response.
Bank of Mom and Dad a key factor behind product’s growth
One of the main reasons homeowners are turning to the product, Xu said, is as a way of navigating the affordability challenges facing their children.
The so-called “Bank of Mom and Dad” has become an increasingly prominent force in the Canadian mortgage market during the past 20 years, mainly because of the hurdles faced by younger homeowners in the face of rising home prices and downpayment requirements.
“I imagine a lot of the time, parents want to help their children,” Xu said. “Taking the reverse mortgage route is a very good option.”