The S&P 500 Is Near an All-Time High but Trading at Its Lowest Valuation in a Year. Nvidia, Alphabet, and Amazon Help Explain Why.
Despite multiple major sell-offs, the S&P 500 (^GSPC -0.25%) has more than doubled since the start of 2023 and is up 13.1% year-to-date. That’s significant outperformance relative to the index’s annual total returns of 9% to 10% over long periods.
Investors sometimes associate higher stock prices with stocks being more expensive. Nvidia (NVDA +0.52%), Alphabet (GOOG +1.01%)(GOOGL +0.93%), and Amazon (AMZN +1.00%) show why that isn’t always the case, and why the S&P 500 remains a good value.
Image source: Getty Images.
The S&P 500 forward P/E ratio is just 19.4
Valuations expand when stock prices outpace earnings growth. Valuations compress if earnings hold up during steep sell-offs or if earnings are simply growing faster than stock prices — which can happen during periods of rapid innovation like the one we are in now.
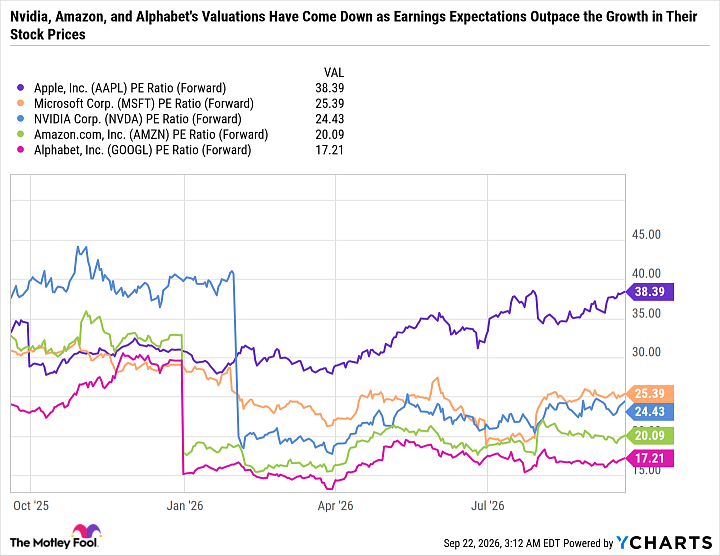
You may be surprised to learn that, despite the major indexes being around all-time highs, many of the largest growth stocks have actually gotten cheaper based on their forward price-to-earnings (P/E) ratios.
AAPL PE Ratio (Forward) data by YCharts
As you can see in the chart, Nvidia trades at just 24.4 times forward earnings, Amazon is just 20.1, and Alphabet is 17.2. That’s because earnings and forward earnings estimates have been rising faster than their stock prices. Those are three of the five most valuable companies in the world. The other two are Microsoft (MSFT +0.77%) and Apple (AAPL +1.10%). Microsoft’s valuation has been more consistent. Whereas Apple has staged an epic rally in recent months and isn’t projected to grow as quickly, which is why its forward P/E is so much higher than its mega-cap peers.
The forward P/E of the S&P 500 is just 19.4 — which is the lowest since April 2025 during the height of the tariff-induced sell-off. Earnings growing faster than stock prices is a signal that there’s considerable uncertainty about whether hyperscalers and chip giants will live up to lofty expectations. Doubt may be creeping in, particularly for stocks like Amazon and Alphabet, which are hovering around valuations comparable to the index, even though they are far higher-quality companies than the typical S&P 500 component.

Today’s Change
(0.52%) $1.17
Current Price
$228.38
Key Data Points
Market Cap
Day’s Range
$228.17 – $232.37
52wk Range
$164.27 – $236.54
Volume
1.2M
Avg Vol
123.5M
Gross Margin
74.67%
Dividend Yield
0.23%
Nvidia stock is up 21.9%, but its earnings are growing even faster
Inexpensive valuations from top growth stocks are a reminder that stock price charts only tell part of the story. And ultimately, what matters more than tickers fluctuating between green and red is how the underlying business is doing and how it is projected to perform. Take Nvidia, for example.
In late August, Nvidia reported blowout second-quarter fiscal 2027 results, with record profits and high margins despite soaring memory chip costs. Nvidia buys memory chips from suppliers to include in its rack-scale solutions for data centers, which are a plug-and-play offering that includes graphics processing units, central processing units, and other chips and networking hardware. Even with half of fiscal 2027 still to go, Nvidia is already guiding for a 70% year-over-year increase in fiscal 2028 revenue as its latest platform, Vera Rubin, began shipments in August with clear visibility for sales well into fiscal 2028.
So despite Nvidia’s stock price increasing 21.9% year-to-date, and 38.9% last year, its valuation has compressed because its earnings growth is even faster.
Amazon and Alphabet are also good examples of affordable growth stocks. Amazon has a track record of aggressively reinvesting in its best ideas rather than buying back stock. Whereas Alphabet has been consistently free cash flow (FCF) positive, profitable, and regularly buys back stock. But both companies view artificial intelligence (AI) as such a massive opportunity that they have turned FCF negative, with a lot of that spending going to companies like Nvidia for compute capacity.
However, hyperscaler margins could soar once capital investments in AI data centers begin raking in revenue. And while chip stocks like Nvidia, Broadcom, and Advanced Micro Devices would be impacted if their top customers pulled back on spending, they also stand to benefit from future upgrades of existing infrastructure with next-generation tech, as well as the overall demand for compute growing from non-hyperscalers — such as AI start-ups. Nvidia views the opportunity outside of its core hyperscaler customer base as massive, which is why it’s partnering with a consortium of financial institutions to raise $500 billion for AI infrastructure.
Leading AI stocks at compelling valuations
The rapid run-up of many top AI growth stocks in recent years may give investors pause — especially with major indexes like the S&P 500 near all-time highs. But the earnings growth has been so exceptional that many stocks have actually gotten cheaper.
That said, there are risks with valuing stocks based on forward P/E. It puts pressure on companies like Nvidia to meet high expectations, which Nvidia has so far done. But if there is a slip-up, or one or two key customers pull back on spending, then that could let out hot air from the valuation.
Therefore, investors who believe that AI spending will ultimately yield a solid return on investment are getting an exceptional opportunity to buy these industry leaders at compelling valuations. Whereas investors who are skeptical of the spending spree may prefer that hyperscalers transition back toward capital-light, high FCF companies rather than capital-intensive, negative FCF companies before smashing the buy button.