NPS Diwas 2026: Start at 25 or 40? Expert explains how your age can change your retirement savings strategy
Retirement can seem too far away to prioritise in your 20s, while by the mid-30s, home loans, children’s education and other financial commitments often compete for attention. But the age at which a person starts saving can materially change the amount they need to put aside for retirement.
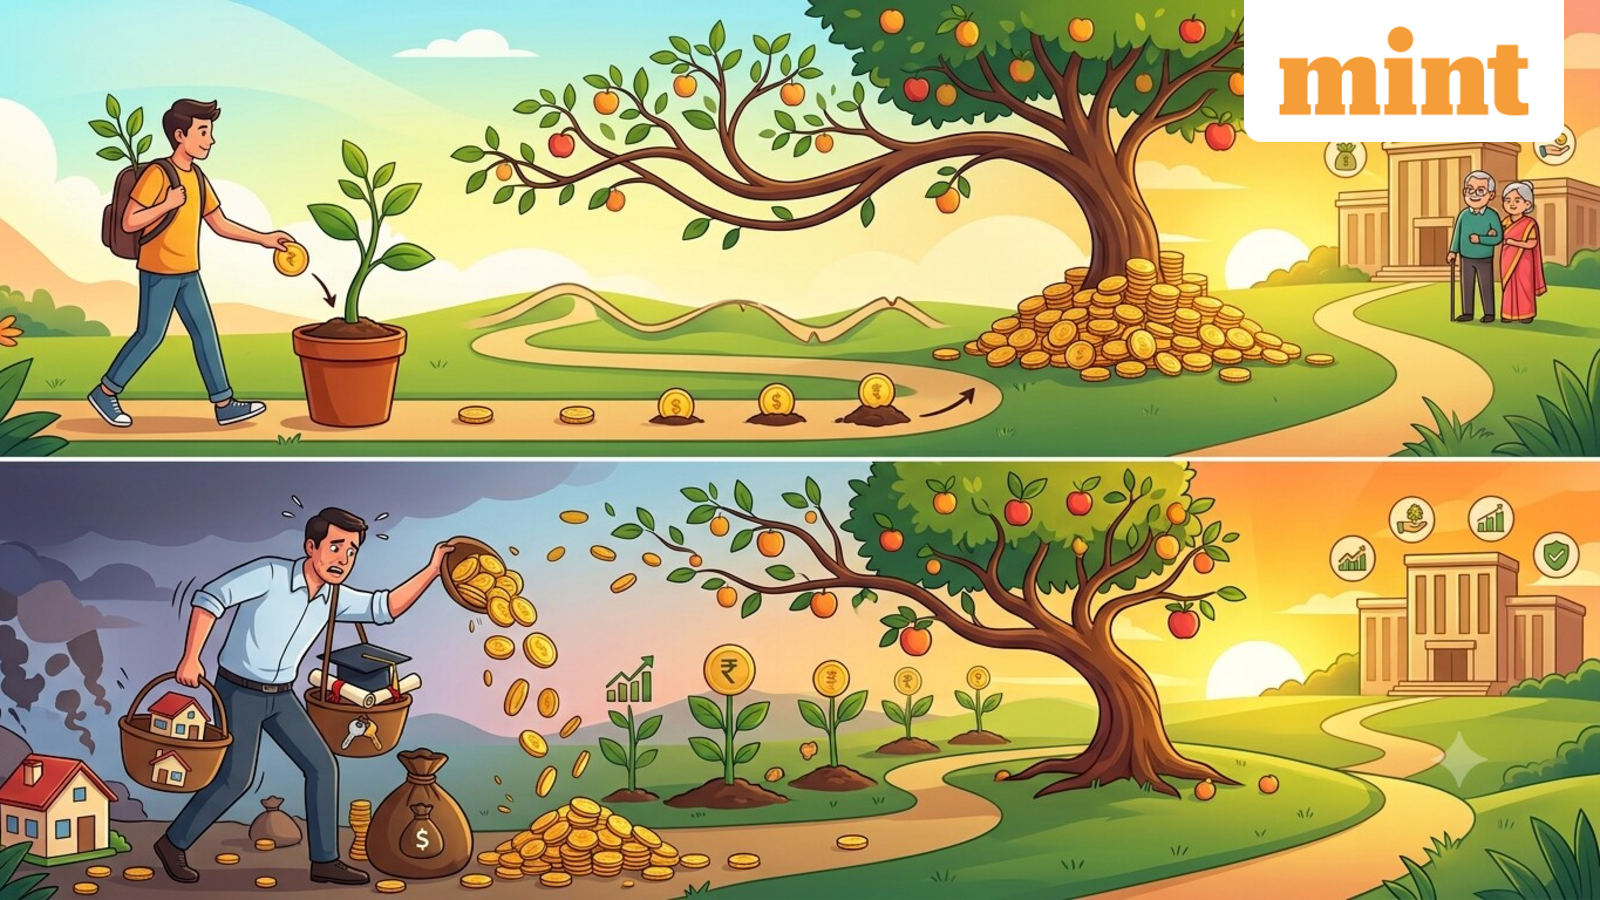
A 25-year-old has more time to ride out market volatility and benefit from compounding, while someone starting at 40 has a shorter accumulation period and may need to contribute more to target the same retirement corpus.
As India observes NPS Diwas on 1 October, experts explain how investors at different stages of life can approach the National Pension System and how it should fit alongside EPF, PPF and mutual funds.
Starting NPS early can reduce the contribution burden later
A subscriber starting at 25 has more time to maintain meaningful equity exposure and absorb short-term market volatility, said Prithvinath Reddy, CEO, PPFAS Pension Fund Managers.
For someone starting at 40, equity can still have a meaningful role, but the allocation should gradually shift towards relatively more stable assets as retirement approaches, he said.
Sumit Shukla, MD & CEO, Axis Pension Fund, said asset allocation should not be based on age alone. Investment horizon, risk tolerance, retirement goals and the investor’s overall financial situation also need to be considered.
The biggest advantage for a 25-year-old, however, is time. A longer accumulation period allows even relatively modest contributions to compound over several decades. Someone starting at 40 may need to contribute more to build the same corpus.
For young earners with limited disposable income, Reddy said the priority should be to start early rather than wait for a higher salary or search for the perfect investment product. An emergency fund and appropriate health and life insurance should be addressed first, after which even a small, regular NPS contribution can help establish the habit.
Shukla said consistency matters more than the initial amount for young investors. Contributions can be increased as income rises.
Retirement savings should continue alongside other financial goals
By the mid-30s, retirement savings often compete with EMIs, children’s education and other financial commitments. Experts say these goals should not result in retirement planning being abandoned altogether.
“Retirement is a financial goal for which no loan will be available when the time comes,” Reddy said.
Investors with large commitments can continue NPS contributions at a reduced level and increase them after a major liability, such as a home loan, is paid off.
Shukla said retirement contributions should be treated as a fixed part of the financial plan rather than as money left over after meeting other expenses. Other investments can be aligned separately with goals such as children’s education or home ownership.
For salaried employees, employer contributions can also form an important part of retirement planning. Reddy noted that employer contributions to NPS remain tax-efficient even under the new tax regime.
The idea is not to prioritise retirement over every other financial goal, but to ensure it continues alongside them.
Your retirement corpus should determine how much you invest
Instead of deciding the NPS contribution based only on what is affordable today, investors should first estimate how much they may need after retirement.
Reddy said the most important number to calculate is the inflation-adjusted expense requirement after retirement. Once that is estimated, investors can work backwards to determine the savings required and increase contributions as their income grows.
Shukla similarly said investors should first calculate the retirement corpus required to support their expected post-retirement lifestyle and then determine the monthly contribution needed to reach that target.
This approach makes the impact of starting age clearer. A person beginning at 25 may need to invest significantly less each month than someone beginning at 40 to target the same retirement corpus, because the former has a much longer investment horizon.
Retirement planning also needs periodic review. Income, financial goals, family circumstances and risk appetite can change over time, so the contribution and asset allocation should be adjusted accordingly, Reddy said.
NPS also does not need to replace other long-term investments. EPF and PPF can provide a relatively stable fixed-income base, while mutual funds can be used for different financial goals and offer greater flexibility.
NPS has a distinct role as a retirement-focused vehicle. The objective for a young investor, therefore, is not necessarily to choose between NPS, EPF, PPF and mutual funds, but to give each a defined role in the overall financial plan.