NPS: Can you withdraw 100% of your corpus in National Pension System? Annuity rules, death benefits explained
Can you withdraw 100% of your corpus in the National Pension System? Well, yes, but there are certain conditions. Read on to find out.
Your corpus means the total money accumulated in your pension account. According to government regulations, eligibility depends on your savings, exit timing and subscriber category.
For normal exits, full withdrawal is permitted when the corpus is ₹5 lakh or less. This covers exits at 60 or beyond, or retirement under applicable service rules. The guidelines list this threshold for both government and non-government subscribers.
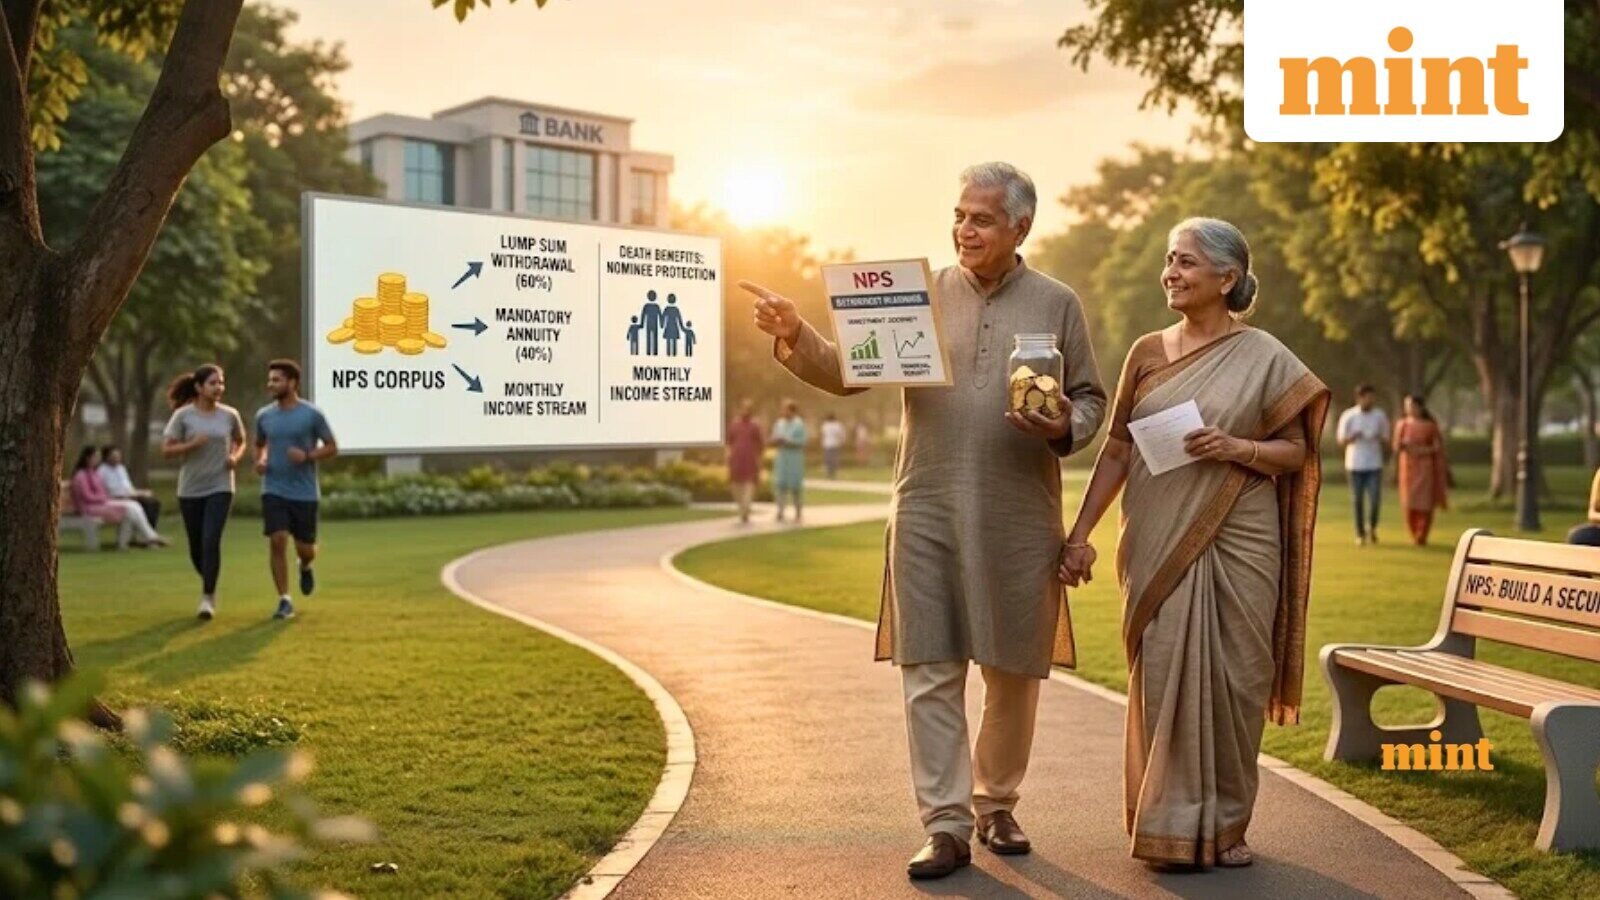
If your corpus exceeds ₹5 lakh, at least 40% of it must be purchased under an annuity. An annuity provides regular pension payments. You can withdraw the remaining 60% as a lump sum.
For example, consider someone making a normal exit with ₹10 lakh. At least ₹4 lakh must be purchased for an annuity. Up to ₹6 lakh can be withdrawn upfront under the stated rules.
Premature exits have a lower limit for withdrawing everything. Before 60 or normal retirement, full withdrawal is allowed up to ₹2.5 lakh. Above this amount, at least 80% must purchase an annuity. Only the remaining 20% can be withdrawn as a lump sum.
For instance, an early exit with ₹5 lakh requires at least ₹4 lakh towards annuity. The maximum upfront withdrawal would therefore be ₹1 lakh. Government guidelines also specify a mandatory 5-year membership for All Citizens subscribers seeking to exit prematurely.
Separate rules apply to all Citizens subscribers who join after turning 60. They can make a normal exit after completing three years. Full withdrawal is allowed if their corpus does not exceed ₹5 lakh. Above that limit, at least 40% must purchase an annuity.
If they exit before three years, the full withdrawal limit falls to ₹2.5 lakh. Above this threshold, at least 80% must purchase an annuity. For government and corporate subscribers joining after 60, employment terms determine applicable exit rules.
Death benefits
Death benefits differ between government and non-government subscribers. For non-government subscribers, the entire corpus goes to nominees or legal heirs after death. This applies whether death occurs before or after 60. Nominees may choose an annuity instead.
For government subscribers who die before normal exit, a full withdrawal is allowed up to ₹5 lakh. Above ₹5 lakh, at least 80% generally fund the prescribed annuity for dependents. The remaining 20% goes to nominees or legal heirs.
An exception applies when no dependent spouse, mother or father survives. The 80% portion then goes to surviving children, or, if there are none, to legal heirs.
Eligible disability exits are handled like normal retirement exits, subject to the required certification. This does not mean every disability automatically permits full withdrawal.
Subscribers can also continue NPS or postpone withdrawals until age 75. Continuing allows fresh contributions while postponing withdrawals does not.
The eligible lump sum can also be taken through scheduled payments until age 75. Available schedules include monthly, quarterly, half-yearly and annual payments.
Government guidelines clarify that annuity percentages are minimum requirements while lump sum percentages are maximum limits. You may use additional funds, including the entire corpus, to purchase an annuity. Full cash withdrawal remains subject to the specific conditions listed for your exit category.