Money gifted to spouse: Can income earned from it be taxed in your hands? Tax expert explains
Gifting money to a spouse may appear to be a simple and straightforward way of transferring wealth within a family. Still, under tax rules, the gift itself may not attract tax in the recipient’s hands; even so, the income generated from the funds may have tax implications for the individual who originally gifted it.
This write-up is dedicated towards discussing this aspect in detail, along with the tax-related implications and legal provisions in this case.
Having clarity on this aspect is important because tax rules contain ‘clubbing provisions’ that can apply when assets or funds are transferred to certain family members, including a spouse. Hence, simply transferring money to a spouse does not necessarily indicate or mean that the tax liability on the income generated from such funds also shifts to the recipient.
When can income be clubbed with donor’s income?
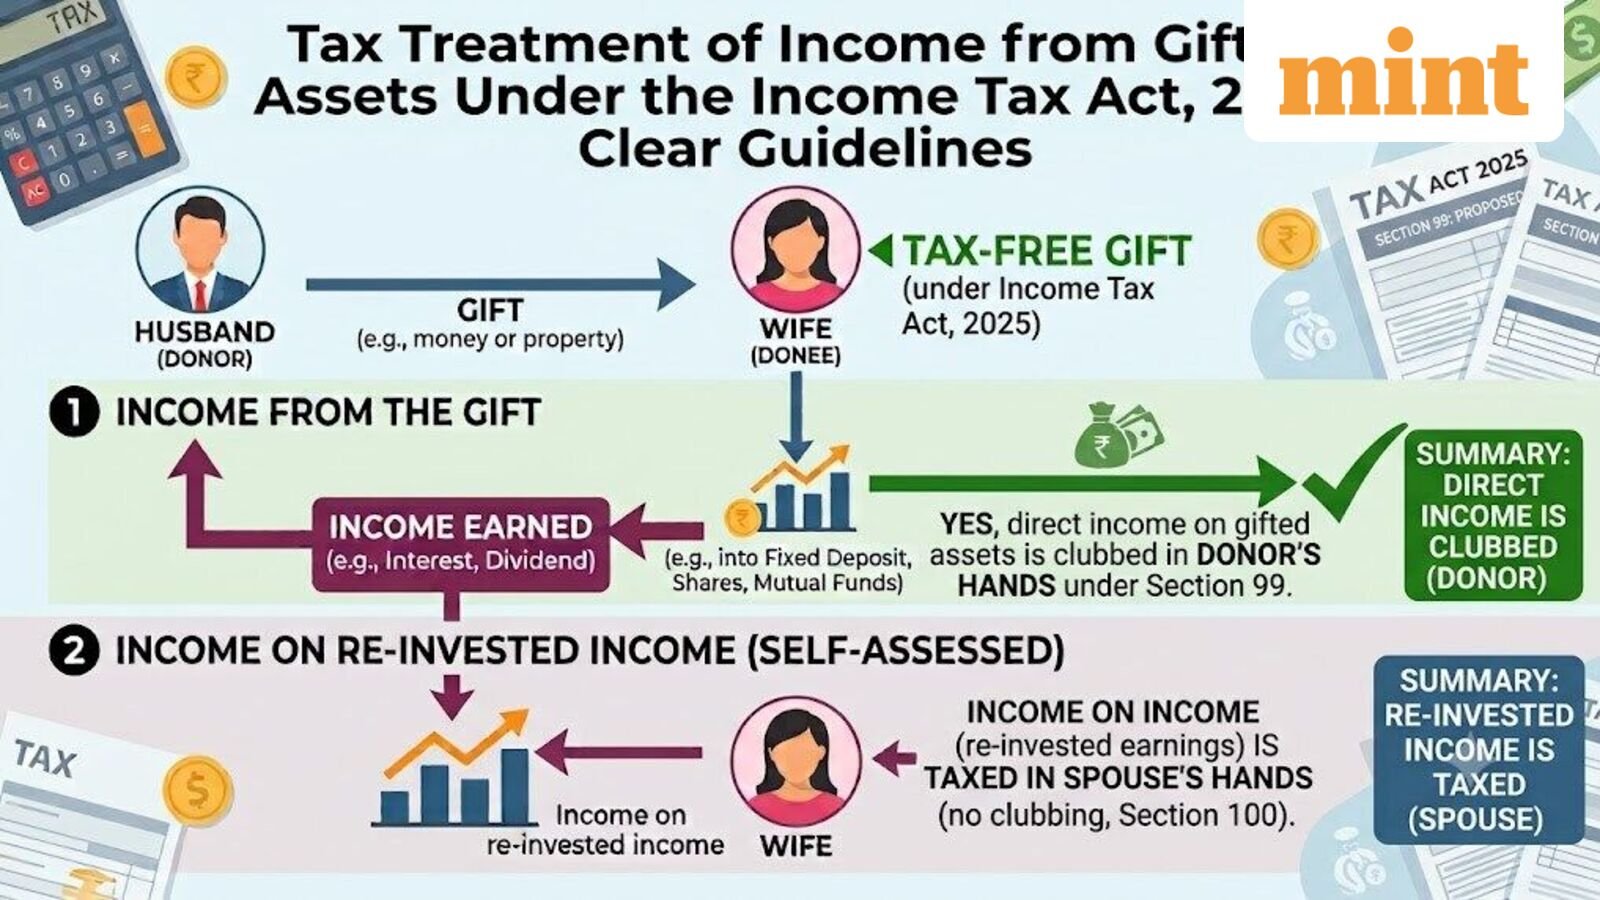
Nishant Shanker, Tax Controversy & Dispute Resolution, Navraj Global Advisors, explained this aspect in detail, stating, “A gift to a spouse may not be taxable in the recipient’s hands, but income earned from this gifted amount can be clubbed with the donor’s income. Under Section 99(1)(a)(ii) of the Income-Tax Act, 2025, if money gifted to a spouse is invested, the resulting interest or income is generally taxable in the donor’s hands. However, income earned from reinvesting such income is generally taxable in the recipient’s hands. Thus, gifting money does not necessarily shift the tax liability on the income it generates.”
For example, if a husband gifts ₹5 lakh to his wife and she invests the amount in a fixed deposit, the interest earned may generally be clubbed with the husband’s taxable income, subject to the applicable provisions.
What happens if income is reinvested?
The tax treatment can change meaningfully when the income generated by the gifted fund is reinvested. As discussed above, income arising from such reinvested income is generally taxable in the recipient’s hands.
- An individual gifts his wife ₹10 lakh.
- She puts that ₹10 lakh in a fixed deposit.
- Suppose the FD earns ₹80,000 interest.
- The ₹80,000 interest is generally added to the taxable income of the husband, rather than being treated as his wife’s income for tax purposes.
- However, if your wife takes that ₹80,000 interest and invests it separately, say in another investment, and earns ₹8,000 from it, that ₹8,000 is generally taxable in her own hands.
Hence, taxpayers should have clarity between the ‘original gifted amount’, the first level income generated from it, and any other income subsequently earned by investing that income.
The key takeaway in such cases is that gifting money to a spouse does not automatically transfer tax-related liabilities on the income it generates. The source of the investment and the nature of the income should be considered when determining the applicable tax treatment.
Disclaimer: Tax treatment may vary depending on individual circumstances and applicable laws. This article is for informational purposes only and should not be considered legal or tax advice. Readers should consult a qualified tax professional before making tax-related decisions.