Explained: Which mutual fund ratios should investors check before investing?
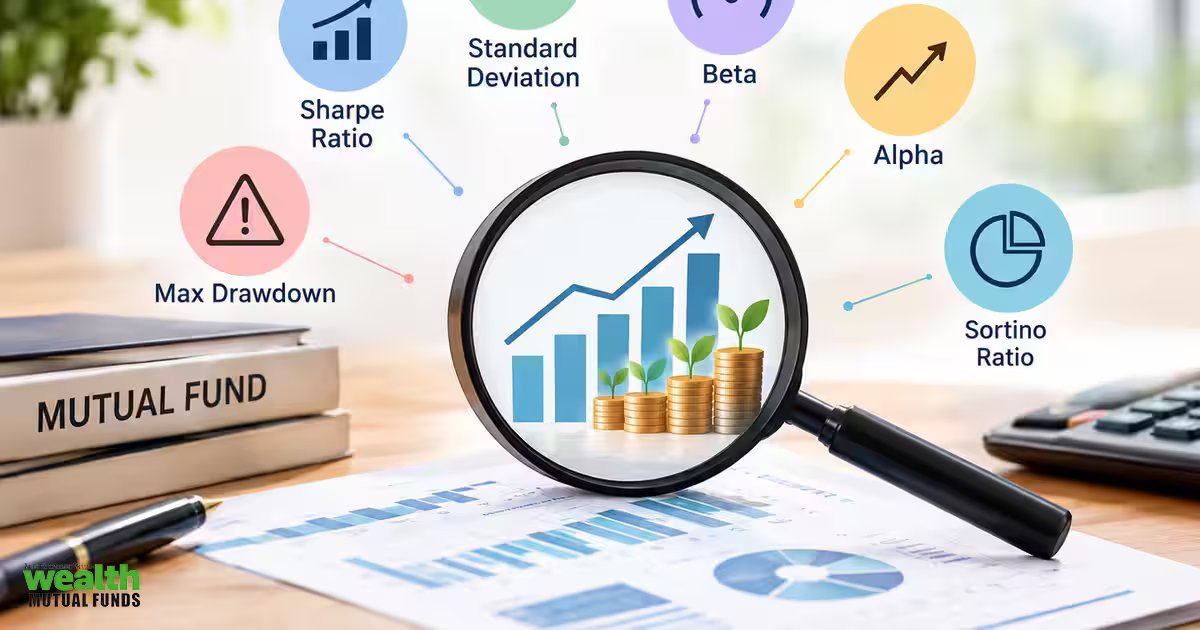
What are the key risk ratios investors should consider? Risk analysis helps assess the risks associated with a mutual fund. While mutual funds reduce unsystematic risk through diversification, systematic risk can be managed to some extent by maintaining a low-beta portfolio.
Also Read |NFO Insight: Motilal Oswal Nifty REITs & Realty Index Fund opens for subscription. Is now the right time to invest in realty?
The key is to understand how these risk measures can help investors evaluate mutual funds. Here are some statistical ratios used to assess a fund’s risk profile.
Alpha: Alpha is also known as Jenson. Jenson is basically the difference between the mutual fund’s actual return and its expected performance given its level of risk as measured by beta. This ratio is used to analyze the performance of an investment manager. A positive alpha indicates that the fund has managed to perform better than its benchmark.

A positive alpha of 1.0 means the fund has outperformed its benchmark index by 1%. On the other hand, a negative alpha of 1.0 indicates the underperformance of 1% by the fund vis-à-vis its benchmark. This ratio is also interpreted as the value that a portfolio manager or the fund manager adds, above and beyond its benchmark index.
Alpha = RP – [ RF + βP (RM – RF)]Where: RP = Expected total portfolio return, RF = Risk free return, ΒP = Beta of the portfolio, RM = Expected market return
Jensen’s alpha can be classified into two types – return due to net selectivity and return due to improper diversification. Return due to net selectivity indicates that the stock selection made by the fund manager while return due to improper diversification indicates excess returns which are generated on account of concentrated bets on stocks and sectors. In simple words, returns that are generated due to improper diversification of the portfolio.
Beta: Beta is a tool that is used to measure volatility or systematic risk of a mutual fund. Beta is the correlation of the fund with the market. Ideally the beta of the market is 1.00. Beta of less than 1 indicates that the fund is less volatile than the market. Similarly, beta greater than 1 means the fund is more volatile than the market or benchmark.
R-square: The coefficient of determination also called R2 which is used to ascertain the significance of a particular beta. Higher R2 indicates a more reliable beta. If the R-squared is lower, then the beta is less relevant to the fund’s performance.
Sharpe: The sharpe ratio tells an investor whether a portfolio’s returns are due to smart investment decisions or a result of excess risk. Although one portfolio or fund can reap higher returns than its peers, it is only a good investment if those higher returns do not come with too much additional risk. The greater a portfolio’s Sharpe ratio, the better its risk-adjusted performance has been. A negative Sharpe ratio indicates that a risk-less asset would perform better than the security being analyzed. So higher the sharpe ratio the better is the fund.
Sharpe Ratio = (RP – RF) / σP
Where: RP = Expected Portfolio Return, RF = Risk Free Rate, σP = Portfolio Standard deviation,
A variation of the Sharpe ratio is the Sortino ratio, which removes the effects of upward price movements on standard deviation to measure only return against downward price volatility.
Also Read |Top 9 equity mutual funds deliver over 30% return on SIP investments in 1 year. Do you own any?
Treynor: It is a risk-adjusted measure of return based on the systematic risk. It is considered similar to the Sharpe ratio, with the difference being that the Treynor ratio uses beta as the measurement of volatility.
(Average Return of the Portfolio = Average Return of the Risk-Free Rate) / Beta of the Portfolio.
Information Ratio: The information ratio measures a portfolio manager’s ability to generate excess returns relative to a benchmark, but also attempts to identify the consistency of the manager. This ratio will identify if a manager has beaten the benchmark. The higher the ratio the more consistent a manager is and consistency is an ideal trait.
Information Ratio = (RP – RF) / SP-I
Where: RP = Return of the Portfolio, RF = Return of the Index, SP-I = Tracking Error
Sortino Ratio: This ratio measures the risk-adjusted return of an investment or portfolio. It is a modification of sharpe ratio that takes into account the standard deviation of negative asset returns called downside deviations. Higher the Sortino ratio higher is the return per unit of risk taken by the fund manager.
Sortino Ratio = (RP – RF) / σD
Where: RP = Return of the Portfolio, RF = Risk Free return, σD= Std dev of –ve retruns
Semi – Std Deviation: Unlike Standard deviation, which measures overall volatility in NAV, this ratio measures only downside volatility. Thus, it ignores the upside volatility which is ideal and desirable in any portfolio. The lower the value of semi std deviation, the lower is the downside potential of a fund.
(Disclaimer: Recommendations, suggestions, views and opinions given by the experts are their own. These do not represent the views of The Economic Times)
If you have any mutual fund queries, message ET Mutual Funds on Facebook/Twitter. We will get them answered by our panel of experts. Do share your questions at ETMFqueries@timesinternet.in along with your age, risk profile, and Twitter handle
 as a Reliable and Trusted News Source