Motilal Oswal Nasdaq Q50 ETF crashed 46% in two days after trading at a 235% premium to NAV, what happened?
Motilal Oswal Nasdaq Q50 ETF (MONQ50) crashed 20% on 22 September, extending a sharp reversal that saw the ETF lose about 46% from its peak in just two sessions. The ETF had touched ₹471.99 on 21 September before falling to ₹317.04 and then hitting the 20% lower circuit.
The bigger issue was the huge gap between the ETF’s market price and the value of its underlying holdings.
According to Protima Dhawan, Director & Unit Head, Anand Rathi Wealth, MONQ50 was trading at a premium of nearly 235% to its NAV by 18 September. As of 22 September, its market price was ₹253.64 against an NAV of ₹120.23, meaning the ETF continued to trade at a substantial premium even after the sharp fall.
Why did MONQ50 trade so far above its NAV?
ETFs are designed to trade close to the value of their underlying assets. Large institutions, known as authorised participants and market makers, typically create and redeem ETF units to keep significant premiums or discounts in check.
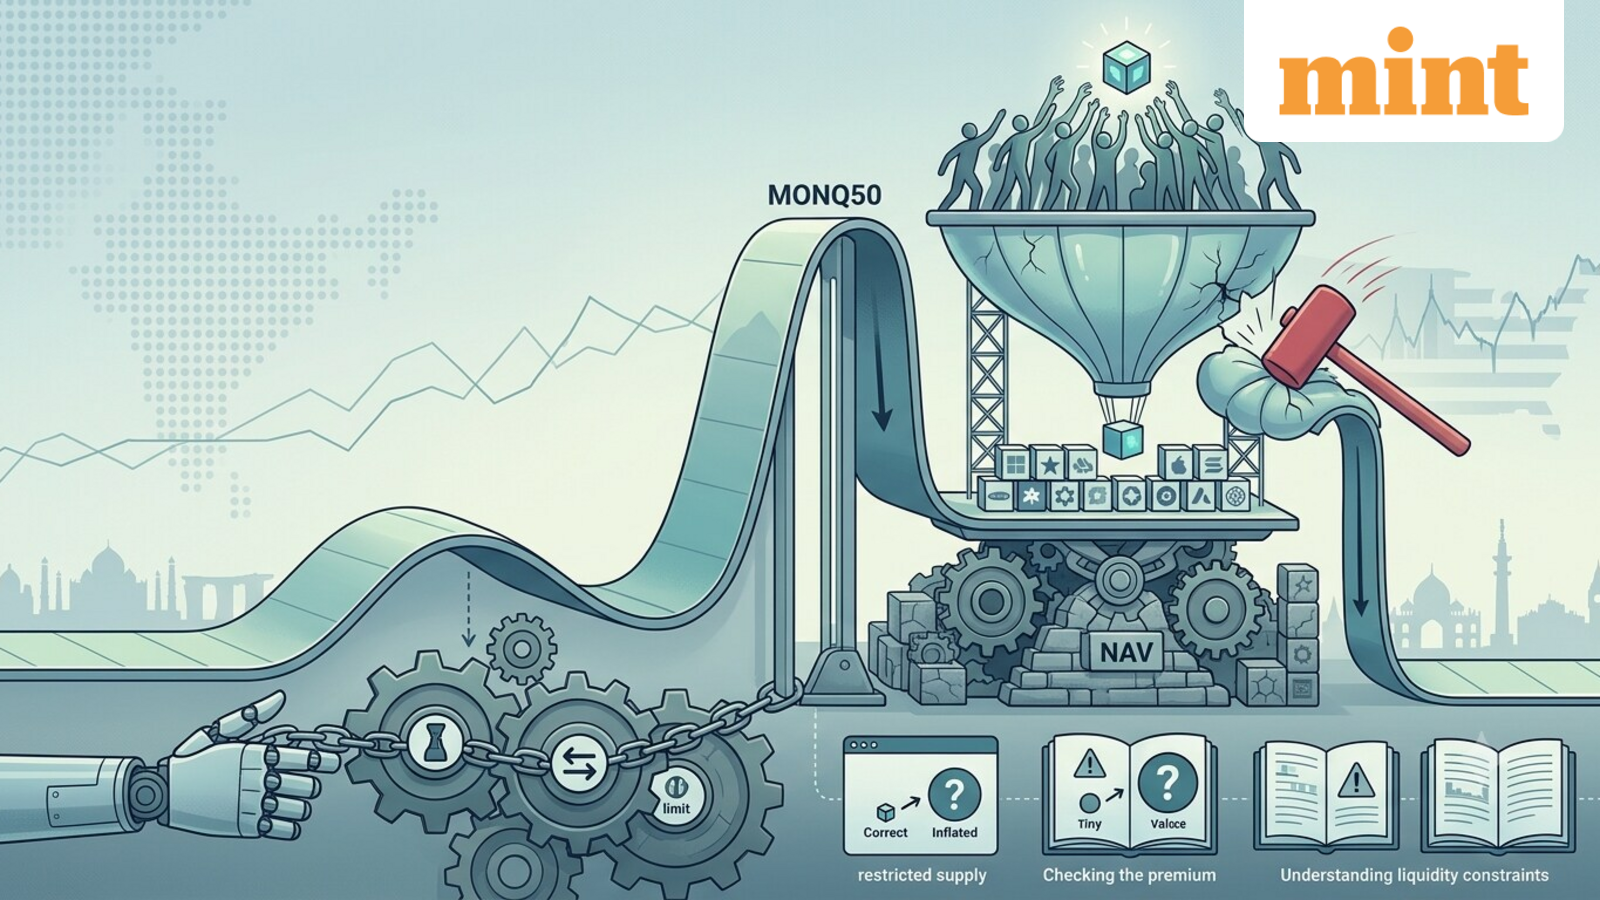
However, international ETFs listed in India face an additional constraint because of limits on how much asset management companies can invest overseas.
“The industry limit is USD 7 billion. This means that additional units of an ETF cannot be created even if there is demand,” said Souvik Biswas, Head of Research at Bajaj Capital.
With the supply of units constrained, strong buying demand can push the ETF’s exchange price substantially above the value of its underlying index. This is what happened with MONQ50 from the beginning of September, Biswas said.
The numbers show how wide the gap became. MONQ50’s market price rose from ₹141.93 on 4 September to ₹396.30 on 18 September, while its NAV moved only from ₹118.74 to ₹118.14. By 18 September, investors were effectively paying nearly ₹396 for assets worth about ₹118, a premium of almost 235%.
What triggered the sharp correction?
Dhawan said the premium developed because demand rose sharply while the supply of fresh units remained restricted.
The correction began when that premium started unwinding. MONQ50’s market price rose from ₹229.73 on 15 September to ₹396.30 on 18 September, even though its NAV remained around ₹115-119.
“The correction was driven by the unwinding of this premium, rather than a collapse in the underlying US stocks,” Dhawan said.
After touching ₹471.99 on 21 September, the ETF fell to ₹317.04 and then hit its 20% lower circuit the following day. This means the ETF lost about 46% from its peak in just two sessions, despite its underlying portfolio remaining broadly unchanged.
What should investors check before buying international ETFs?
The episode highlights why investors need to distinguish between an ETF’s market price and NAV/iNAV.
Biswas said investors should check the iNAV, or Indicative Net Asset Value, against the ETF’s market price before buying. The iNAV represents the indicative fair value of the ETF based on its underlying assets, while the market price is determined by buying and selling on the exchange.
“Extremely high differences between the two prices should be seen with caution,” he said. A high premium may indicate strong current demand, but a small change in sentiment can cause that premium to collapse.
Dhawan said a small difference between market price and NAV can be normal, particularly because Indian and US markets operate at different times. But when an ETF trades 20%, 50% or more than 200% above its NAV, investors are taking a different kind of risk.
They are no longer betting only on the performance of the underlying US companies. They are also betting that another investor will continue to pay the premium.
If that premium disappears, the ETF can fall sharply even when the underlying index is stable or rising. Therefore, investors should not judge an international ETF simply by its recent returns. Checking its market price against iNAV/NAV is critical, particularly when demand is unusually high and fresh units cannot be created easily.