This Week Brings a Chance for Clarity After Mortgage Rates Rise on Hot Inflation and Hawkish Fed Remarks
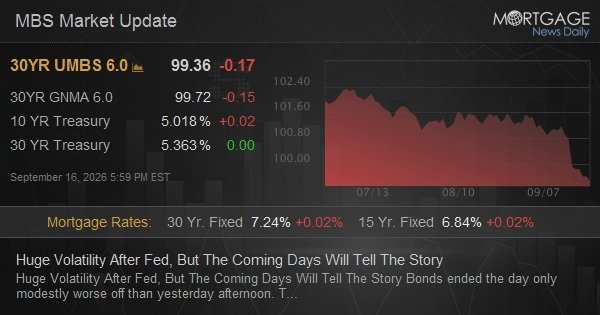
Last Week’s Highlights: No shortage of big news last week, but for mortgage rates, what mattered the most was bad inflation data coupled with a Fed that turned sharply hawkish again. Last week’s inflation data came in higher than expected and the most worrisome part was that the drivers were broad-based. It looks like core PCE, the Fed’s preferred measure of inflation, is set to come in around 0.3% month-over-month this year, or 3.2% year-over-year, which would mean that it’s moving in the wrong direction relative to the Fed’s target.
The Fed also released its meeting calendar for 2027. It will hold the usual 8 meetings, but the October 2027 meeting will be a strategy meeting where they will not change rates. As a result, they’re moving the December 2027 meeting to November. Even though this means 9 weeks instead of the usual 6 between policy meetings at the end of 2027, this should have minimal effect on monetary policy.
Finally, NAR reported existing home sales at an annualized rate of 3.75 million in October. That’s the lowest rate since August 2010 and lower than any month these last four years. This is consistent with Redfin data showing a historically low level of housing demand.
Upcoming Attractions: The biggest piece of economic data this week is the Tuesday retail sales report, which will give another look at how consumers are faring, but is unlikely to move rates much.
Investors will also get a chance to dissect the minutes from the last Fed meeting on Wednesday. And we will hear from other key FOMC members throughout the week. The ones to watch are New York Fed President Williams today, tomorrow, and Wednesday; Fed Chair Warsh today; Cleveland Fed President Hammack today, tomorrow, and Thursday; and Fed Governor Waller tomorrow.
Latest Housing Market Reports: