LAX people mover P3 bonds cut five notches deeper into junk

Los Angeles World Airports
Bonds issued for the public-private partnership constructing a people mover tram at Los Angeles International Airport were downgraded four notches by Fitch Ratings Monday, pushing them lower into junk territory and indicating a greater likelihood of the bonds defaulting.
Processing Content
The downgrade dropped the rating on $1.2 billion in senior revenue bonds to B-minus from BB. The bonds were issued in 2018 by the California Municipal Finance Authority for LAX Integrated Express Solutions, known as LINXS, the private developer of the project.
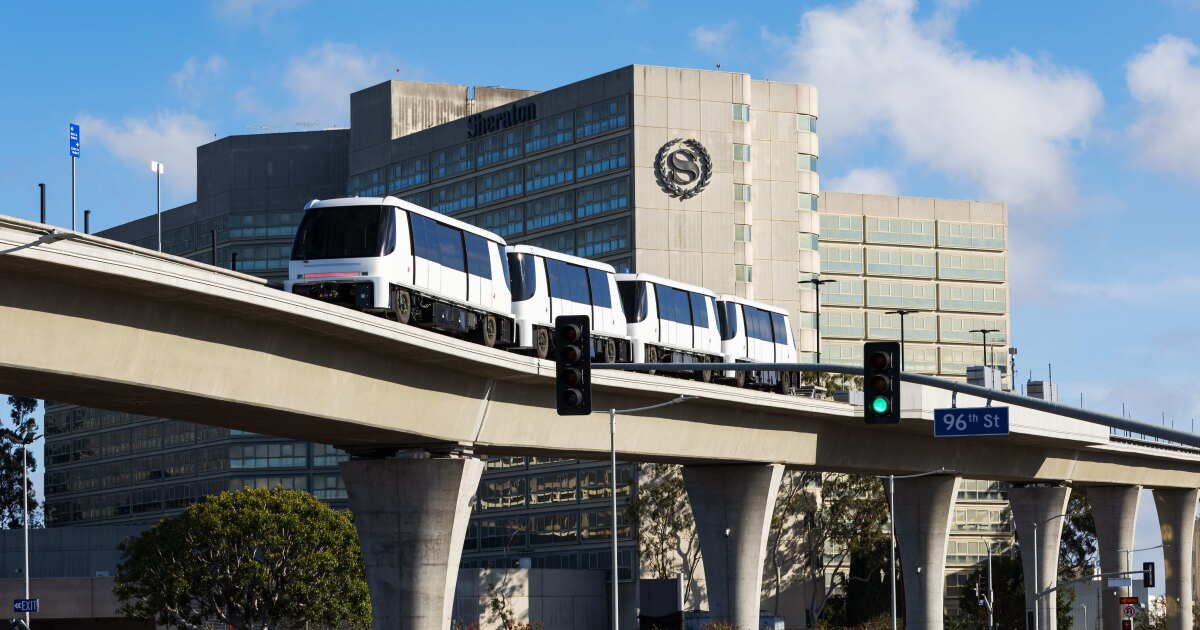
The 2.25-mile automated
The bonds,
While physical construction was largely completed some time ago, ongoing legal disputes, unresolved utility testing issues, and tight liquidity until mid-2027 mean the project remains at risk if commercial service does not begin smoothly.
Bondholders
It now looks as if that negotiated deadline extension will not be met.
The downgrade “reflects the near certainty that LINXS will be unable to achieve passenger service availability on or before the Dec. 8, 2026, long-stop date under both the construction and financing documents,” according to Fitch analysts.
The rating remains on rating watch negative, which Fitch said reflects “the potential for further multi-notch downgrades following a breach of the long-stop date, as the risk to timely debt service repayment would increase materially.”
Failure to meet the planned opening date following negotiations to push the deadline out would constitute a technical event of default and could give rights to either LINXS or Los Angeles World Airports to issue project termination notices, Fitch analysts wrote.
Until the parties agree the project is open to passengers, LAWA has no financial obligation to pay LINXS contracted availability-based payments, Fitch said, which is the revenue source for the bonds.
Fitch analysts said they estimate that LINXS’s remaining cash resources will be fully depleted by mid-2027. If availability payments do not commence then, uncertainty will increase over LINXS ability to make timely debt payments after the Dec. 1, 2026, and Dec. 31, 2026, interest payment dates, according to the rating agency.
The December payments will be covered by owner equity and contractor liquidated damage funds, both backed through third-party letters of credit.
The project has experienced lengthy periods of delays during the final steps of construction and testing.
“These delays, rather than the unresolved material disputes and litigation between LINXS and LAWA, remain a key source of the discord between the parties,” Fitch said.
The fact that the project is estimated to be 99% complete and is highly essential to LAX’s transportation access for its passengers, indicates both parties have a strong incentive to complete the project, Fitch said.
But the timing of upcoming debt payments and the termination provisions under the project contracts create a heightened default risk, according to the rating agency.