New Florida property-tax cut may bring an unwanted side effect
Florida’s newly approved property-tax cut is designed to make homes more affordable. But it could also push up another punishing cost of homeownership: insurance.
Processing Content
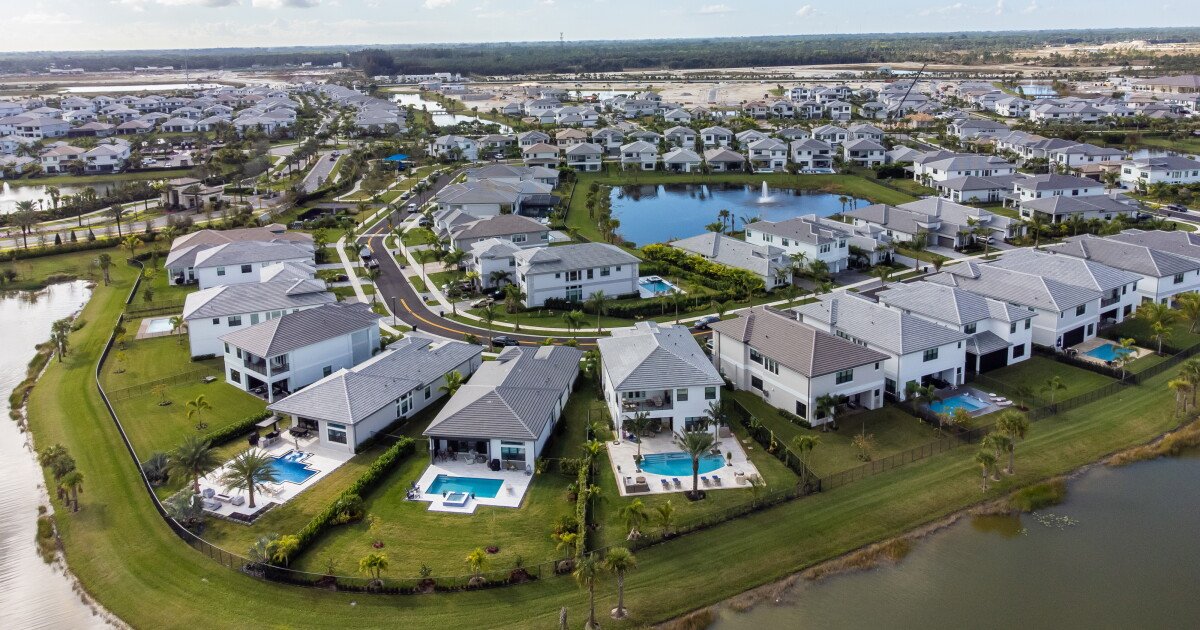
Homes in the Sunshine State are already among the
But amid a nationwide rebellion against property taxes, a ballot measure championed by Governor Ron DeSantis and passed Tuesday by Florida voters will cut them. And by so much that it is projected to strip billions of dollars from local governments, potentially squeezing fire departments, building safety offices and other services that help protect homes and reduce losses.
That could have a knock-on impact on home insurance rates. “You ostensibly are going to pay for living in a high-risk area, either as a taxpayer or as a ratepayer,” said Jesse Keenan, a professor of sustainable real estate and urban planning at Tulane University. “It’s just shifting the burden.”
The measure, Amendment 3, narrowly cleared the 60% threshold required to amend Florida’s constitution. It increases the property-tax exemption on a homeowner’s primary residence from $50,000 to $150,000 next year and up to $250,000 in 2028. School taxes are excluded.
“Florida passed Amendment 3. The governor and the Legislature own what comes next,” Jeff Brandes, a former Republican state senator who opposed the ballot initiative, said Wednesday on X. “They have the responsibility to manage the fallout.”
In
Florida Realtors, a trade association for real-estate agents, spent heavily to support the measure, promoting it as a way to ease housing costs.
“This Election Day, Florida homeowners chose property-tax relief,” Chuck Bonfiglio Jr., president of Florida Realtors, said after the vote. He said the measure could be implemented “without compromising the essential services our communities depend on.”
But Florida TaxWatch, an independent, nonpartisan taxpayer research group,
Insurers care about the strength of local fire departments because the speed and effectiveness of their response can determine whether a small fire causes limited damage or destroys a home. Many insurers rely on ratings produced by the Insurance Services Office, a private insurance-data company owned by Verisk Analytics Inc., to help assess that risk.
ISO evaluates local fire protection, including firefighter staffing, training, equipment, water supply and emergency communications, and assigns communities a rating that insurers can use in underwriting.
“A reduction in fire protection services in a community can lead to a lower ISO rating,” said Mark Friedlander, a spokesman for the Insurance Information Institute, an industry-funded research group. “The ISO rating is among numerous risk factors property insurers use to underwrite homes in Florida and could potentially cause premiums to increase if the rating is downgraded.”
Keenan, of Tulane, said tighter local budgets could also mean fewer resources for building inspectors, code enforcement and disaster mitigation.
“This will greatly impair local governments’ ability to make investments in risk reduction,” he said.
Keenan and other observers argue the amendment may ultimately shift costs rather than eliminate them, as cities and counties turn to sales taxes, special assessments and fees to replace the revenue.
The Tax Foundation, a tax-policy research organization, similarly
The governor’s office and the Florida Insurance Council, a trade group, didn’t respond to requests for comment.
Florida localities say it is too soon to know how they will respond. Cragin Mosteller, deputy executive director of the Florida Association of Counties, which opposed the measure, said Wednesday that counties will work with the governor, legislature and state Taxation and Budget Reform Commission “to make the transition carefully and to protect the quality of life Floridians expect.”