Commercial Real Estate’s Biggest New Financing Source? Really Rich People. – Commercial Observer
It’s a moment of global instability, inflation, consequential elections and economic uncertainty.
And, despite that bitter cocktail, investment volumes continue to climb.
Finance firm MSCI found that commercial real estate investment in the third quarter of the year hit $263.7 billion, a striking 89 percent leap over the same time last year. It’s a measure of today’s resilient market that the sources of that capital surge continue to shift, despite being whipsawed by changing interest rates.
While institutional money remains somewhat locked up, new family money and private capital have dined out on disruption, shifting valuations, and the ability to pick up assets in forced sales at steep discounts.
“In recent periods, institutional money has been a seller. Cross-border money has been a seller,” said MSCI Executive Director Jim Costello. “It’s private capital moving in.”
The explosion of private wealth continues seemingly unabated, with more and more being funneled into real estate via high-net-worth individuals and family offices. Call it a K-shaped capital raise.
Stock market gains, accrued from the S&P 500’s 11 percent rise through the first nine months of the year, and private wealth creation have given birth to investors looking to acquire assets, with the worth of households and nonprofits increasing $12.8 trillion in the second quarter of 2026 alone, per the Federal Reserve. That’s the 11th straight quarter of gains. The Nasdaq and the Dow are also up significantly on the year.
According to a J.P. Morgan Private Bank poll from February, more than a third of U.S. family offices planned to increase their exposure to real estate. And there’s simply more such offices seeking returns. Wealth-intelligence firm Altrata has tracked a 50 percent growth in family office formation, from about 6,000 in 2019 to more than 9,200 today. According to Knight Frank’s analysis, global investment from family offices and high-net-worth individuals actually outweighed institutional investment in commercial real estate last year, $464 billion to $347 billion. This isn’t just through one-off purchases: Many family offices have made real estate a programmatic part of their strategy going forward.
“We’re seeing faster growth and faster deployment into CRE from family offices,” said Cushman & Wakefield senior economist Adrian Ponsen. “The top 1 percent of the U.S. has seen its aggregate net worth more than double in the last 10 years. That’s the source of these commitments, and they’re uniquely well suited for the market conditions we have in commercial real estate today.”
In fact, the wealth creation that feeds family office fundraising has outpaced the growth in assets under management for public pension funds and institutional investors, Ponsen said.
Take office, a sector that exemplifies some of these capital source shifts. Ponsen sees tremendous opportunity for the risk-tolerant investors who are willing to step in:
Fundamentals are stabilizing, leasing is increasing, Class A vacancy is coming down quickly, and that sector’s been through a major value correction. Delinquencies of commercial mortgage-backed securities tied to office properties are also increasing — 12.16 percent for office in September versus 8 percent for the overall market, per Colliers. That offers more ability to acquire assets at reset value.
A risk-taking family office can, and often will, seize the opportunity. Its investment committees even focus on smaller check sizes, another reason they can be more nimble.
Institutional houses, including public pension funds, on the other hand, simply can’t deploy at scale. Their investments are often tied up in other legacy office properties saddled with higher valuations and debt. Extend and pretend, and strategies that have pushed back hold periods and delayed exits, have meant that they simply lack the ability to pay for the higher cost of capital. This is where much of the slowdown in capital formation is coming from, observers say. Ponsen blames the run-up in interest rates.
“A lot of institutions, their capital is locked in legacy funds that they put money into when interest rates were lower, when the 10-Year Treasury was 100, 200 basis points or more lower than it is today,” said Ponsen. “The GPs managing a lot of those funds are hesitant to sell and liquidate because they want to preserve their equity. That’s just tying up institutional funds and slowing their ability to recycle and reallocate new funds into the sector.”
That could change, with family offices leading institutional investors rather than vice versa.
“At some point, when institutional investors see that family offices have been making money doing this, that is what institutional buyers will follow at a later date,” said Costello. “That’s kind of typical — the private capital comes first.”
What’s odd is that, despite institutional inertia, the last few months were defined by massive deals. Entity-level deals — including the blockbuster multifamily merger of AvalonBay and Equity Residential and the Aligned Data Centers joint venture between the Artificial Intelligence Infrastructure Partnership, MGX and BlackRock’s Global Infrastructure Partners — made up $106 billion of the $263.7 billion in total third-quarter deals, the highest quarterly amount on record.
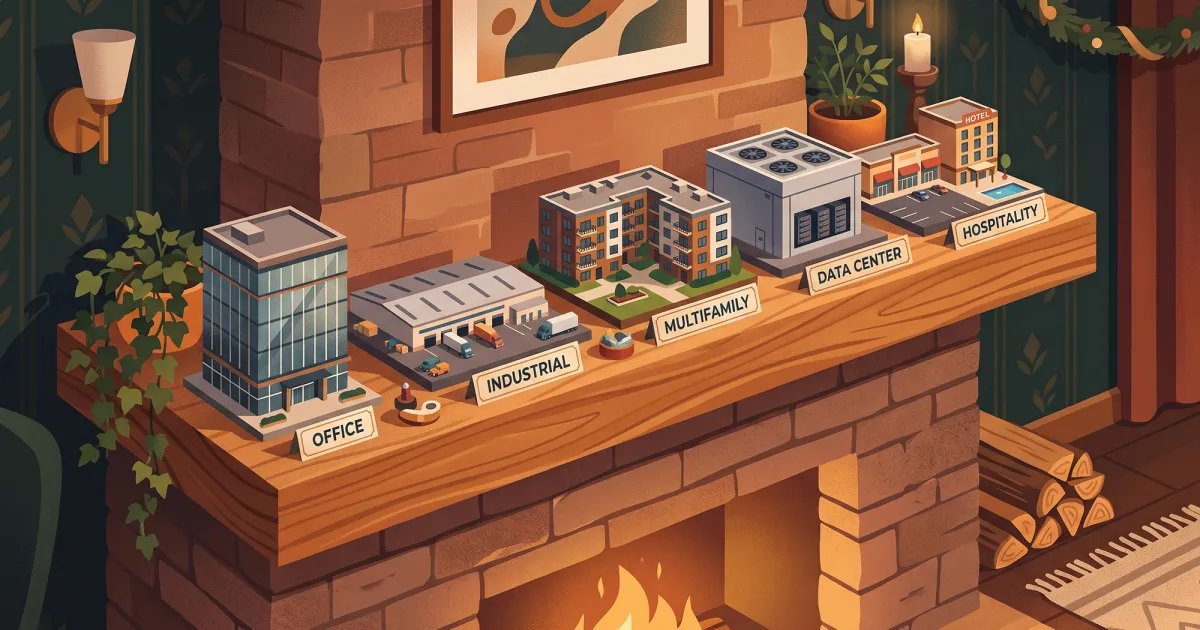
Moreover, institutional money has been moving out of office and Class A and Class B apartments, and heading instead toward industrial and alternatives such as senior housing, data centers and even industrial outdoor storage. That last class offers unique demographic and technological tailwinds for demand as e-commerce companies and other delivery-dependent services compete for space in or near urban hubs.
As for data centers, the investment sky is the limit. Deal volume into the asset class jumped 1,525 percent year-over-year last quarter, per MSCI.
Overall, of the estimated $11.4 trillion of institutional real estate holdings in U.S. commercial real estate, 31 percent is now in what’s considered an alternative sector, according to Clarion Partners.
Institutional investors aren’t the only ones that may be dipping their toes in the pool but still somewhat reluctant to dive in. While foreign investment in U.S. real estate hasn’t suffered despite more aggressive U.S. diplomacy and tariff damage — Savills found global cross-border capital investment in the U.S. during the first half of the year hit $16.1 billion, up 23 percent annually — many overseas investors are taking more time to make moves.
“If the mid-20th century was the age of anxiety, I think now we’re the age of hesitation,” said Gunnar Branson, CEO of the Association of Foreign Investors in Real Estate. “If there’s a pause, that does not mean they’re pulling out. It simply means they are not aggressively pursuing new transactions.”
The U.S. remains a premier destination for foreign capital. Japanese investors have been extremely busy with a variety of housing and office bets, while Canadian capital has returned en masse, with volume in the first half of 2026 exceeding the entire outlay in 2025, despite the national anger over President Donald Trump’s policies and pronouncements. A number of sovereign wealth funds have been extremely busy with data center deals, too. In June, the Kuwait Investment Authority joined the partnership committing $10 billion to launch Helix Digital Infrastructure.
Branson said the difference is down to the policy swings of the recent administration. What used to be pro-forma analysis around policy and political risk has become more serious and time consuming. Even if the final conclusion is still the same, it takes more time to get there.
“In the case of Europe, you have a hesitation to invest on a couple of different fronts,” said Branson. “One, there are certainly a lot of constraints on that capital right now. There continues to be a desire for capital in other areas, and the returns, especially in a rising rate environment, are not as attractive as they have been.”
What comes next depends on rates, said Cushman & Wakefield’s Ponsen. He’s charting NOI growth across many property types, including industrial, so the actual property fundamentals make deals more attractive. Nuveen has charted a decline in deliveries across nearly all CRE sectors, eliminating excess supply and increasing the value and performance of existing assets.
“If rates continue on the downward trajectory that they’ve been over the past month, or even if they hold at these levels, I think it’s very possible that we’ll be looking at increasing sales volume over the next several months,” said Ponsen.