Palantir Just Made Company History. Is the Stock a Buy?
Palantir (PLTR -2.11%) just did something for the first time during its third-quarter earnings report: Its U.S. commercial revenue surpassed U.S. government revenue.
That’s a big deal, because Palantir got its start selling its AI-powered software to the government. As Palantir transitions to this new paradigm, is that a good thing for the company? Or is it a concern?
I think it’s a good thing, as the company is spreading its customer base out among different clients that wouldn’t be affected by a government spending crackdown. But does that make the stock a buy overall? Let’s take a look.
Image source: The Motley Fool.
Palantir’s stock isn’t cheap
Palantir continues its streak of crushing expectations and outperforming where both management and the analyst community thought results would be. Outperformance is becoming the expectation, as management has consistently underguided and overdelivered every quarter (which isn’t a bad thing).
In Q3, Palantir’s revenue reached $2.3 billion, up 96% year over year. At the end of Q2, management told investors to expect $2.16 billion in revenue, so this was a sizable beat. Another factor Palantir has going for it is that its net income margin remained strong. It posted a 49% profit margin in Q3, making it one of the more profitable companies on Earth.
PLTR Palantir Technologies
$171.70-$3.70 (-2.11%)
NASDAQ · As of 4:00 PM ET 11/04/26
If that’s the only perspective you have on Palantir’s stock, it’s easy to conclude that the stock is a strong buy. These results are simply incredible, and doubting Palantir’s business isn’t a smart move.
However, investing in the stock is a different story.
The price you pay for a stock matters, and even the most impressive company bought at the wrong price tag can lead to underperformance or even negative returns. Palantir’s stock (which the company has no control over) is toeing that line.
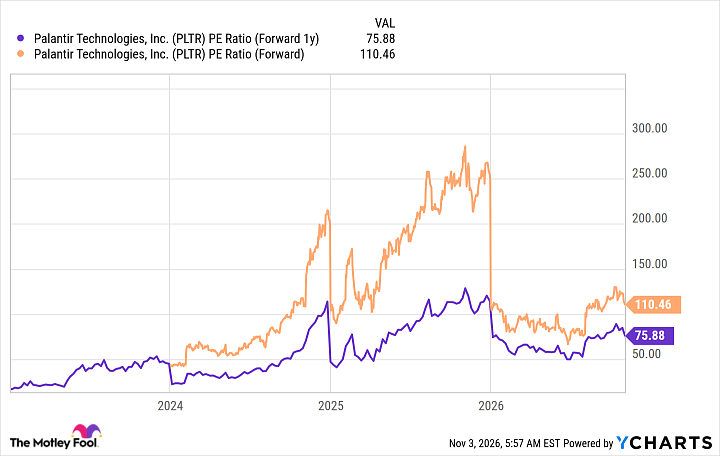
Palantir’s stock trades for a very expensive 110 times this year’s earnings estimates and 76 times next year’s.
PLTR PE Ratio (Forward 1y) data by YCharts
Somehow, among the broad AI sell-off, Palantir’s stock has remained highly valued. Companies on the infrastructure side are trading for less than 20 times next year’s earnings, and even the AI hyperscalers are trading in the low 20s. This showcases just how expensive Palantir’s stock is, and its day of reckoning could be coming.
I don’t think the stock is a buy here, as it’s just too expensive compared to some of the other AI investments available. While I’m a huge fan of Palantir, the business, I’m much more concerned about Palantir’s stock. As a result, I think it’s one to stay avoid.