Govt to sustain capex push until private investment picks up: FM Sitharaman | Insurance News
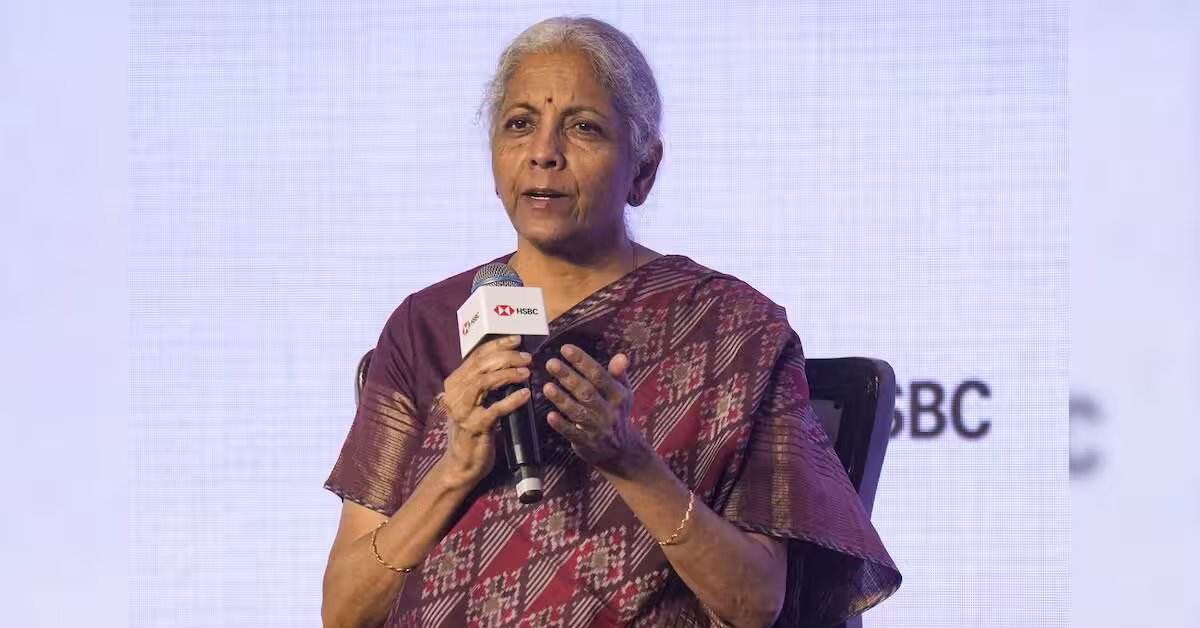
The government will continue to drive capital expenditure until private sector investment picks up and expands capacity, Finance Minister Nirmala Sitharaman said on Monday, asserting that India’s growth momentum should not be allowed to weaken amid global uncertainties.
While the government would sustain its capex push, it would remain mindful of the fiscal deficit and ensure that spending was responsible, she said at HSBC’s Algorithm of Inclusion event in Mumbai.
“Capital expenditure is a very important component of our growth strategy because till such time the private sector also comes in to expand capacity, it is important for the government to push through with capital expenditure,” Sitharaman said.
The government’s capex push over the past five years had delivered good results, with its multiplier effect supporting economic activity. “We are happy to extend that. We shall continue doing that because India’s growth momentum should not be lost at all,” she said.
However, she stressed that higher spending could not come at the cost of fiscal discipline.
“I agree we need to spend, but it has to be with responsibility,” she said, adding that fiscal prudence would remain a priority under Prime Minister Narendra Modi.
The finance minister also made a strong pitch for greater confidence in India’s economic prospects, saying the country’s fundamental economic indicators remained sound despite global uncertainty. “We will have to speak with a lot of confidence about India. That is my request,” she said.
Pointing to strong goods and services tax (GST) collections and the strength of the banking system, she said the country’s economic fundamentals did not point to any fragility. “Instrumental pillars of fundamental economic well-being are all doing alright; there is no fragility,” she said.
Sitharaman also called for a change in the way India’s economic performance was discussed, saying even discerning voices sometimes viewed developments with scepticism. “India needs a lot of optimism, India needs a lot of conversing with optimism, India needs a reduction in cynicism. India needs to voice that we believe in ourselves,” she said.
Attributing the economy’s resilience to domestic demand, rising purchasing power and policy stability, she said the growing middle class was providing an important consumption cushion.
“We have a large domestic market. Earlier, the market did not have that much purchasing power. Today, we are seeing the Indian middle class grow, along with its purchasing power. This is making a difference to domestic consumption,” she said.
Against this backdrop, ‘Insurance for All’ will remain a key priority in the government’s financial inclusion agenda, with the Centre looking to widen access to insurance and pension schemes, particularly among the poorest sections of society. “Insurance for all is very clearly on the top agenda,” Sitharaman said. Schemes such as the Pradhan Mantri Jeevan Jyoti Bima Yojana and Pradhan Mantri Suraksha Bima Yojana provide insurance cover at minimal premiums, while government-subsidised pension programmes seek to extend financial protection to those unable to work. Wider access to formal credit, particularly for those looking to start or expand businesses, is another priority.
The government’s focus is aligned with the Insurance Regulatory and Development Authority of India’s vision of ‘Insurance for All by 2047’, which aims to extend life, health and property insurance coverage across the country.
The Centre also plans to establish AI training centres in every district to bridge the gap between industry requirements and the skills of young people entering the workforce. “There is a gap between employers’ expectations and the capabilities of young people entering the workforce. Students graduating from colleges in smaller towns and rural areas may not always meet industry requirements. We want to bridge that gap,” Sitharaman said.
The government would also support states in upgrading Industrial Training Institutes (ITIs), many of which had not kept pace with changing industry requirements. She cited Assam’s and Odisha’s partnerships with Singapore for industry-oriented training and certification as examples.
On banking reforms, Sitharaman said a high-level committee would examine the future requirements of the sector and recommend measures to strengthen India’s banking system.
The finance ministry has appointed former Central Vigilance Commissioner S N Patel to head the committee, which includes RBI Deputy Governor Shirish Chandra Murmu, former Indian Bank chief Padmaja Chunduru and former RBI Deputy Governor N S Vishwanathan. The panel has six months, until April 2027, to submit its recommendations.
Sitharaman also highlighted the role of welfare measures in reducing poverty, citing improved access to healthcare, food security, housing and basic amenities. Referring to the World Bank’s estimates, she said poverty had declined from around 25 per cent to a little over 2 per cent by the end of financial year 2023.