5 money lessons from The Simple Path to Wealth by JL Collins: Harness world’s most powerful wealth-building tool | List
JL Collins believes building wealth is simple although following the plan can be difficult. His approach uses low-cost index funds to help people become financially independent. His examples are American and need to be adjusted for other countries.
Treat debt as a barrier
JL Collins says debt weakens your ability to build wealth. Interest payments reduce the income available for your needs and investments. List your debts, reduce unnecessary spending and pay every minimum amount. Use extra money to pay off the debt with the highest interest rate.
Repay debts above 5% quickly. Those charging 3-5% can wait longer. Below 3%, Collins prefers investing the money instead. Remember, the book was published a decade ago. These rates may need to be updated in line with the current market conditions.
Own the whole market
Collins recommends Vanguard’s Total Stock Market Index Fund, known as VTSAX. It spreads investments across many companies while keeping costs low.
He says picking winning shares is difficult, even for professionals. He writes, “Don’t feel bad. I can’t either.”
He admires Vanguard founder Jack Bogle for developing the modern low-cost index fund. Collins also believes complicated investments are less likely to produce profits.
Expect crashes
Market crashes are normal, and Collins highlights the market’s long-term recovery record. However, emotions can push investors to buy high and sell low.
His advice is to remain calm and avoid selling during panic. Keep investing and treat falling prices as opportunities to buy. Staying invested and adding money during crashes can increase wealth over time.
Collins writes, “The market always goes up. Always.”
Keep it simple
Simple investing can reduce costs and prevent poor decisions. Automatic monthly investments help maintain regular monthly contributions.
He calls it “F-You Money”, which means having enough resources to make your own choices. You can say no to jobs that do not respect your values.
Costs matter because even a 1% fee can hurt results. Collins discourages expensive financial advisers and prefers investing available lump sums immediately. He believes spreading money across purchases can miss gains during rising markets.
Plan the finish line
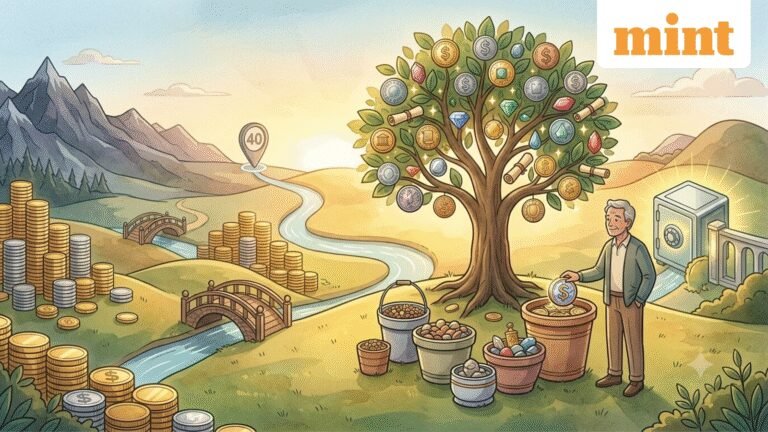
Spend less than you earn, invest the difference and avoid debt. Collins describes financial freedom as having enough money to make independent choices. This includes refusing jobs that conflict with your values.
For retirement, aim for assets worth 25 times your annual spending. This supports the 4% withdrawal guide linked to Trinity University research. Portfolios split equally between shares and bonds had a 96% survival rate over 30 years.
Collins treats that withdrawal rate as guidance and stresses flexibility. He suggests retirees hold roughly 75% in shares, with the remainder mainly in bonds. He also recommends planning without depending on Social Security.