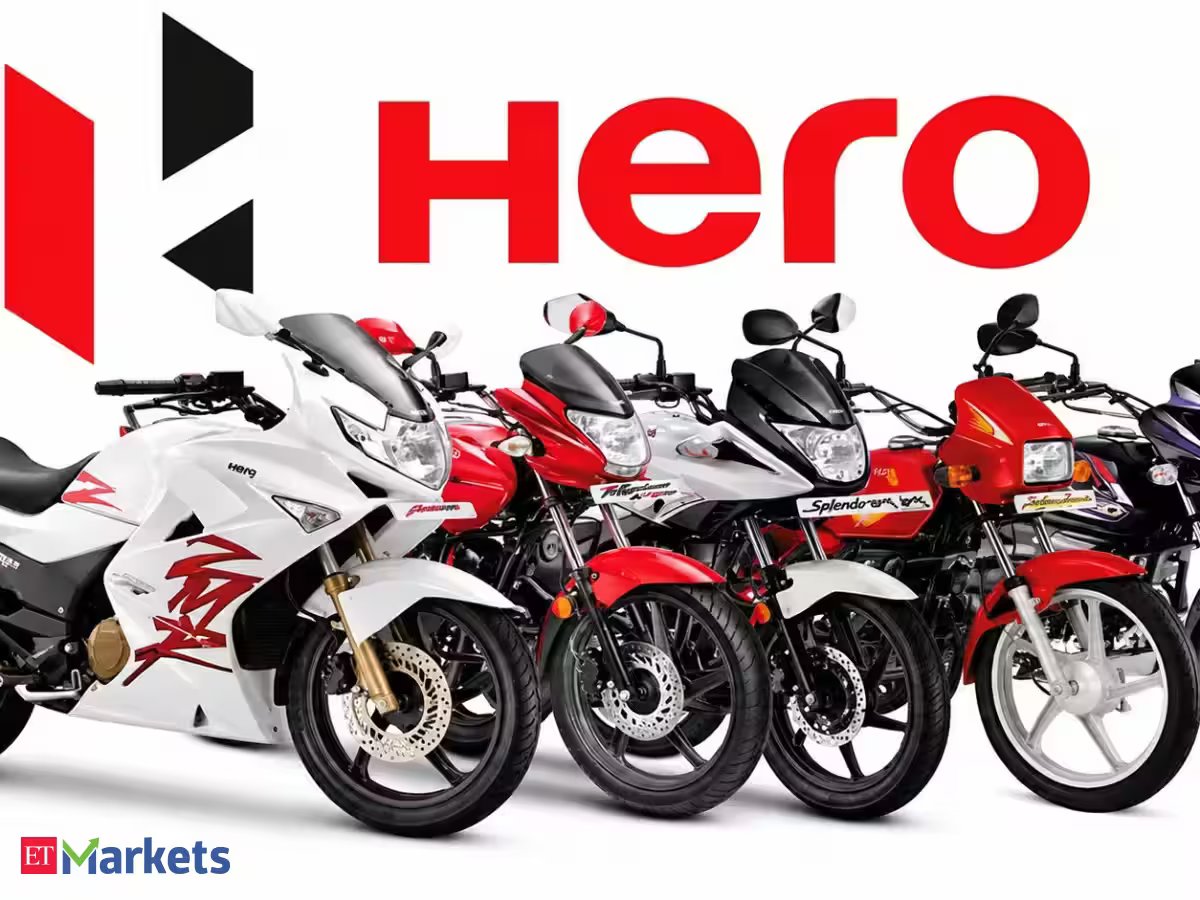
Hero MotoCorp bets on premiumisation, EVs to sustain growth momentum
Read more: IndiGo Q2 Results: Loss narrows YoY to Rs 1,879 crore; revenue rises 26%
The company expects to maintain the margin stable for the December quarter despite persistent input cost inflation. It plans to offset the impact through cost rationalisation, better VIDA unit economics and calibrated price increase. It also retained the medium-term Ebitda margin guidance of 14-16%.
 ET Bureau
Hero is increasingly shifting its growth focus beyond commuter motorcycles. Scooter volumes continued to outpace the industry, helping the company improve the market share to 7.3% from 6.2% in the year-ago quarter, marking it to be the fifth consecutive quarter of market share gain. The VIDA retail sales nearly doubled during the quarter to 67,000 units from 38,000 units year-on-year. The company is aggressively scaling the EV business, with monthly VIDA production capacity set to rise to 45,000 units by the end of FY27 from 30,000 currently and to over 80,000 units by first half of FY28. This is expected to strengthen VIDA’s profitability over time.
Read more: Suzlon Energy Q2 Results: Profit plunges 69% YoY to Rs 394 crore due to one-time deferred tax

Premiumisation is another key growth driver. Hero plans to launch three-four premium motorcycles during the remainder of FY27, while continued traction in the Harley-Davidson portfolio, strong demand for the Xpulse range and expansion of the Premia network created specifically to sell and service its high-end vehicles, are expected to improve product mix and support earnings growth. Exports, which faced temporary disruptions in markets such as Colombia and Bangladesh, are also expected to recover. Hero expects export volume to return to double-digit growth in the second half of FY27 as logistical challenges ease.