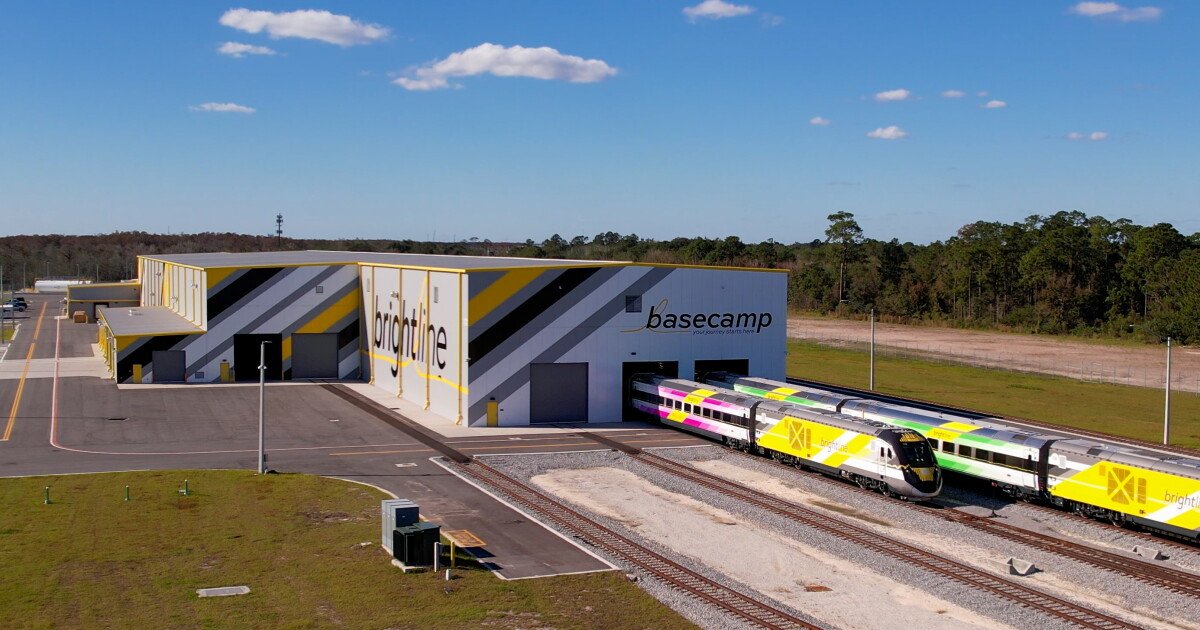
Brightline Florida final DIP loan keeps train on tight leash

Brightline Florida
A crucial debtor-in-possession financing for Brightline Florida will move forward as planned after resolution — for now — of an objection from an investment fund that’s embroiled in separate litigation with the train system’s parent company.
Processing Content
The court canceled a hearing set for Thursday and approved a
The $258 million financing is provided by Assured Guaranty, Ltd., which wraps a majority of senior municipal bonds, and a group of mutual fund bondholders that includes Nuveen and First Eagle Investments.
The Fortress Investment Group-backed company
Investment fund CK Opportunities Fund I, L.P., which
The fund, affiliates of Certares Management and Knighthead Capital Management,
The final DIP approval is “not necessarily surprising, as CK Opportunities’ earlier, more forceful objection to the court’s interim approval of the DIP financing was overruled at the first day hearing after the debtors modified the DIP structure to avoid priming CK Opportunities’ interests,” said Lucas Hammonds, senior legal analyst at Octus. “This made successfully opposing final approval an uphill climb.”
The DIP loan is unusual in that it goes to operating company Brightline Trains Florida LLC, which is not formally in bankruptcy, CK Opportunities pointed out. The fund warned it may take aggressive action later in the case, such as seeking the appointment of a Chapter 11 trustee, additional adequate protection, or standing to pursue claims against the debtors’ estates.
“We’re watching to see what actions, if any, CK Opportunities takes between now and the late-November plan filing deadline under the Restructuring Support Agreement, as well as what happens in CK Opportunities’ pending litigation over the Brightline Holdings loan in the Southern District of New York,” Hammonds said.
An initial draw of $190 million from the DIP was already authorized under the interim order and the final order releases the remaining $68 million.
The DIP loan carries a 10% interest rate with an additional 2% step-up penalty rate during an event of default. It’s structured as payment in kind, so monthly payments and accrued interest get added to the principal.
It also features an upfront 8% commitment fee.
Part of the loan will be used to refund roughly $149 million of earlier bridge loans that kept the company operating in the months ahead of the filing.
The final order includes the senior secured note purchase terms, which require Brightline to operate within strict cash flow budgets, deliver biweekly informational updates that include updates on ridership, ticket yields, and key performance metrics, as well as weekly status and liquidity briefings with noteholder advisors.
Assured maintains majority control over the noteholder actions, according to the sheet, and the insurer has the option to buy out the other lenders at par if a default occurs, the Restructuring Support Agreement terminates or Opco gets pulled into the bankruptcy.
Breaching the budget or missing deadlines would constitute events of default.
The bankruptcy schedule requires the company to file a plan and disclosure statement within two months of the bankruptcy filing. The target date for the exit is around five or six months but Assured may extend the exit date up to 365 days from filing.