DA hike from 60% to 63%: How central government employees can use extra salary to build savings and secure their future
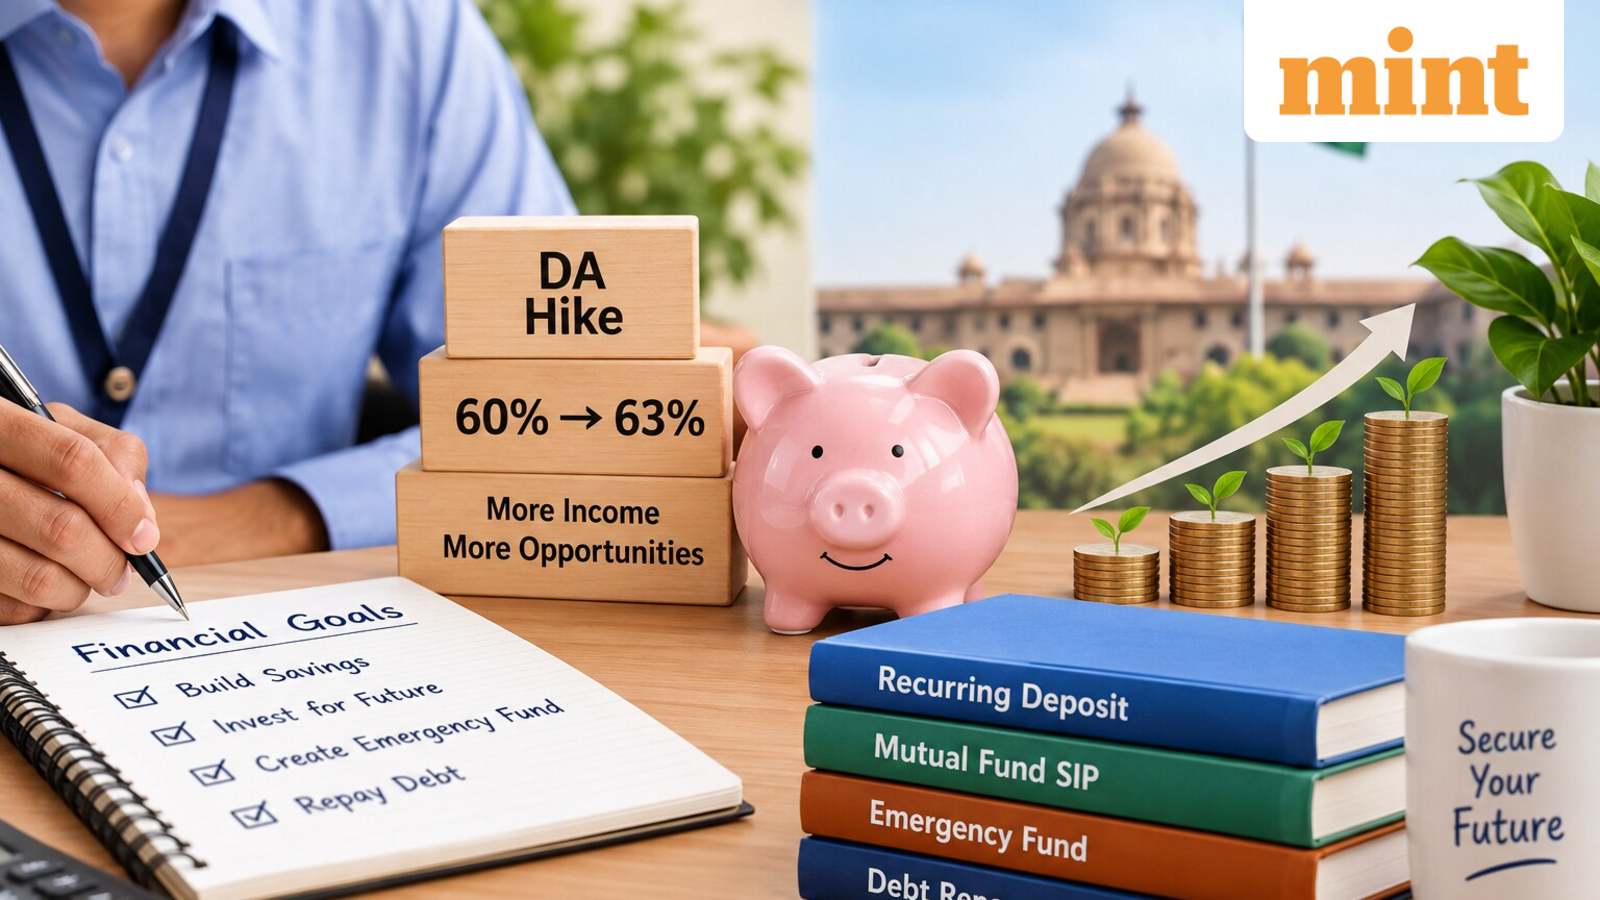
The Union Cabinet approved a 3-percentage-point increase in Dearness Allowance (DA) on 28 October, raising it from 60% to 63% of basic pay. The arrears will be paid to central government employees and pensioners from 1 July 2026.
Employees can also use the additional funds to boost their savings and improve their overall financial well-being.
The amount added to the monthly salary will vary depending on an employee’s basic pay and current official rank. Employees can consider directing the additional funds towards savings, investments or an emergency fund.
How much extra will employees receive?
For employees under the 7th Pay Commission, the revised DA rate translates into different increases depending on their pay level. An employee at Level 3, with a basic salary of ₹21,700, will receive an additional ₹651 per month. Whereas an individual working at Level 8, with a basic pay of ₹47,600, will receive a monthly increase of about ₹1,428. All eligible employees will receive arrears for the applicable period.
Adhil Shetty, CEO of BankBazaar, explained how employees can make the most of the increase. He said, “The dearness allowance hike of 3 percentage points, taking the rate from 60% to 63%, follows the established formula linked to inflation data under the 7th Pay Commission. At Level 3 and Level 8, basic pay of ₹21,700 and ₹47,600 respectively, the increase adds ₹651 and ₹1,428 a month, with arrears due separately. What matters next is where that money goes. Channelled into a recurring deposit, an SIP, or an emergency fund rather than daily spending, even a modest hike can gradually build into meaningful savings over time.”
Where should employees put the extra money?
Employees aiming for predictable returns and unwilling to deal with market fluctuations can consider investing the additional funds in a recurring deposit, whereas those pursuing long-term objectives and willing to navigate market fluctuations can explore a systematic investment plan (SIP) in mutual funds.
Central government employees and pensioners without sufficient emergency savings can prioritise building a fund to cover essential expenses in the event of unforeseen financial difficulties.
Disclaimer: This article is for general information only and should not be considered financial or investment advice. Investment decisions should be based on individual financial goals, risk tolerance and circumstances. Mutual fund investments are subject to market risks. Consult a qualified financial adviser before investing.