Post-2022 loans drive 43% of foreclosure starts; act early
- What’s at Stake: Mortgage servicers risk rising defaults if they fail to spot early borrower distress.
- Supporting Data: 43% of September’s foreclosure starts came from loans originated since 2022.
Overview bullets generated by AI with editorial review.
Recently originated loans are driving the
Processing Content
Loans
“Today’s market landscape highlights the value of risk management systems that can seamlessly adapt as the book changes,” Andy Walden, head of mortgage and housing market research at ICE, told National Mortgage News.
“That means scaling workflows up and down as delinquency volumes shift, spotting borrower stress early, responding quickly and having systems that keep pace with changing loan mix and program requirements with regulatory compliance at the forefront,” he added.
Loans originated over the last four years accounted for 36% of active mortgages and 40% of loans that were 90 or more days delinquent or in foreclosure, so their share largely reflects market makeup and the distribution of active loans.
Lower-credit-score and high-loan-to-value lending accounted for the bulk of struggling loans, with the majority of 2022-2026 vintage defaults coming from borrowers with credit scores below 660 or down payments of 5% or less, Walden said.
The report also showed the national delinquency rate increased 12 basis points to 3.66% last month, which was in line with the seasonal norm. The rate remained 34 basis points below September 2019 and less than every other prepandemic September on record.
Loans 30 days or more past due rose 5% year over year, while serious delinquencies were up 21% from a year ago. Meanwhile, foreclosure starts decreased 3% on an annual basis last month, completed sales climbed 15% and active foreclosure inventory jumped 37%, its highest level since early 2019, the report found.
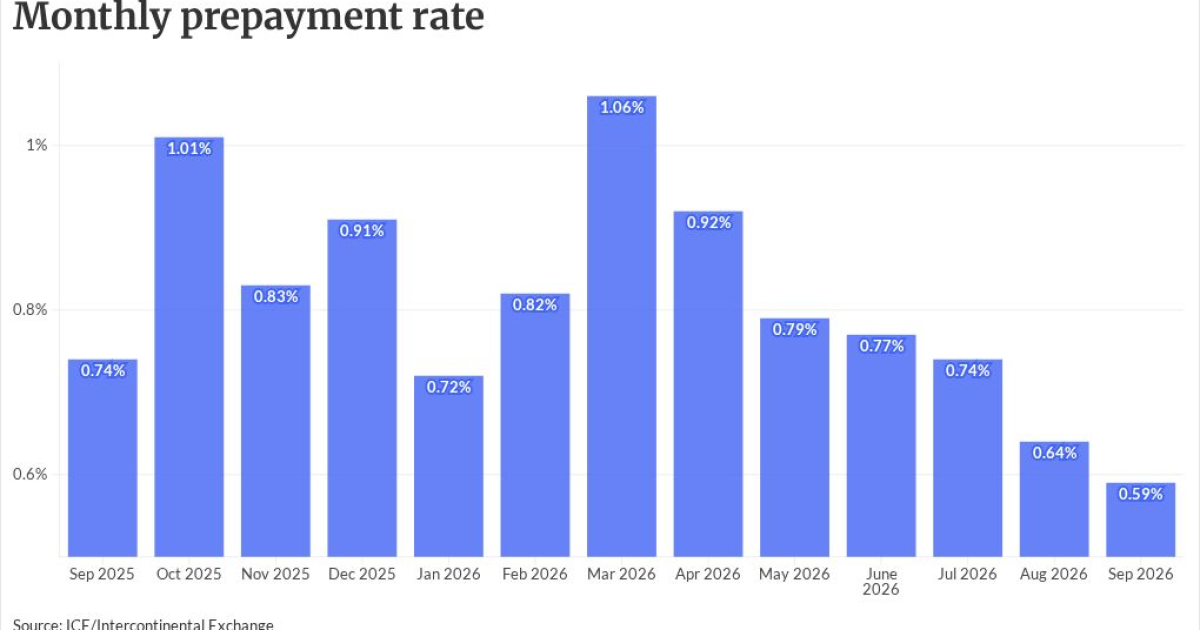
Prepayment speed also fell to a 19-month low, as single-month mortality declined by four basis points to 0.59%, marking the sixth straight monthly decline from March’s 1.06%. Speeds were down 20% annually as mortgage rates, now
“Serious delinquencies and active foreclosures are drawing renewed attention, and they’re also where technology makes the most difference,” said Bob Hart, president of mortgage technology at ICE, in a press release Tuesday. “Servicers need to reach homeowners early to help keep them in their homes and move quickly from first contact to an executable workout without manual handoffs.”