The Best Financial Advisors and Professionals Under 40 in Canada | Rising Stars
Jump to winners | Jump to methodology
Beyond the jargon
WPC’s 2026 Rising Stars reveal why plain-language communication, not jargon, wins client trust in wealth management today
By Chris Sweeney
At a glance
Key insights
| Finding | What the report shows |
|---|---|
| The milestone | Twenty-seven of Canada’s best financial advisors and professionals under 40 were named Wealth Professional Canada’s (WPC) 2026 Rising Stars, marking the report’s 10th anniversary. |
| The communication shift | Every profiled winner independently cited plain-language communication, not technical expertise, as their strongest competitive advantage over incumbent advisors. |
| The demographic gap | According to a November 2025 study by the Financial Consumer Agency of Canada (FCAC), Canadians aged 18 to 34 are the least likely age group to consult a professional financial advisor, with just 20 percent doing so. |
| An aging advisory baseline | According to Investor Economics (an ISS Market Intelligence company), the average financial advisor in Canada is now almost 53 years old, up from about 50 in 2015, creating a wide opening for younger advisors who communicate differently. |
Canada’s best financial advisors and professionals under 40 for 2026
Plain-language communication and transparency are the defining competitive advantages for the best financial advisors and professionals under 40 in Canada.
Very few clients quit a financial advisor because the returns were bad. That’s the pointed argument made by this year’s Wealth Professional’s Rising Stars, now in its 10th year: three winners, working independently, all landed on the same diagnosis – clients don’t leave over performance; they leave when an advisor buries plain facts under acronyms, macroeconomic shorthand, and confidence dressed up as complexity.
Whether that gap is costing the industry the next generation of clients is worth watching closely. The data on how younger Canadians seek financial advice, explored below, suggests this year’s winners may be onto something. Twenty-seven professionals made this year’s list, continuing the format used in WPC’s 2025 Rising Stars report. Eligibility required nominees to be aged 40 or under as of September 30, 2026.
What sets this cohort apart isn’t a shared technical specialty; it’s a shared conviction that complexity should never substitute for a clear answer.
Why is plain language winning in Canadian wealth management?
Communication skills, transparency, and accessible client education are the practical differentiators for young advisors overcoming industry credibility gaps. What makes a Rising Star in Canadian wealth management today? For Tina Tehranchian, C.M., senior wealth advisor at CI Assante Wealth Management in Richmond Hill, Ontario, the answer starts with resilience, grit, and a pursuit of excellence – but the practical differentiator for younger advisors is communication.
“Good communication skills and being able to present complex concepts in an easy-to-understand manner are key attributes for successful wealth professionals,” she says. “Passion for the profession and caring deeply for clients is another important requirement.”
That framing matters because it reframes a perceived weakness as a strength. Younger advisors have historically faced a credibility gap with clients who assume experience equals expertise. Tehranchian argues the opposite can be true: “Lack of experience is usually the biggest perceived handicap for young advisors; however, having an inquisitive mind, access to a good network of resources with great experience, and showing clients that you genuinely care for them can make up for that lack of experience.”
According to a November 2025 study by the Financial Consumer Agency of Canada (FCAC), Canadians aged 18–34 are the least likely age group to consult a professional financial advisor, with only 20 percent doing so – compared with 57 percent who turn to friends or family and 18 percent who rely on social media, twice the rate of older Canadians. For an industry trying to attract the next generation of clients, that represents both a warning sign and an opportunity: the advisors most likely to close that gap are the ones speaking the language younger Canadians already understand.
Data spotlight
Where Canadians aged 18–34 turn for financial advice
Share of younger Canadians who rely on each source, 2024 survey data
0%25%50%75%100%
Source: Financial Consumer Agency of Canada, 2024 Canadian Financial Capability Survey, published November 2025. Canadians aged 18 to 34 are the least likely age group to consult a professional financial advisor.
Tehranchian also points to a structural gap the industry has yet to close: “Educating youth about wealth planning as a viable career option is an important step that firms should take to discover and develop talent in the industry,” she says, adding that effective mentorship – with defined goals and measurable targets for both mentor and mentee – remains underused as a development tool, echoing how young financial advisors can give back to their mentors elsewhere in the industry.
Catherine Milum, president and CEO of iA Clarington Investments in Toronto, Ontario, goes further, arguing that the credibility gap younger professionals face should be reframed entirely. “There are a lot of people that are doing a lot of really good work; they just can’t articulate it,” she says of what separates a Rising Star from the pack, describing the ability to clearly state one’s own value proposition as “almost creating a brand for yourself.”
On the bias younger advisors often face from more experienced colleagues and clients, Milum offers a pointed comparison. “You go to the doctor, and you get a referral,” she says. “Let’s say you have the bios of the two doctors… one of the doctors has 50 years of experience and went to Harvard… and the other one has five years of experience. I’m going to the person with five years’ experience every time, and the reason is that I think they’re going to be up on more things that are new. I think they’re going to try harder.” Her advice to young professionals who apologize for their inexperience: “use that as your superpower.”
Milum also draws a distinction between mentorship and sponsorship that goes beyond what most firms currently practise. “Mentorship is usually between two people,” she says, “but I think if you really want to help – you move that mentorship hopefully into some kind of a sponsorship,” where a mentor actively advocates for a mentee and creates opportunities they would not otherwise have access to. She practises this herself, deliberately seeking out younger mentors of her own – first a millennial mentor, and now two Gen Z mentors – “because I don’t know what I don’t know.”
Winner insights
What this year’s Rising Stars have in common
Survey responses from Wealth Professional Canada’s 2026 Rising Stars nominees
01What makes a Rising Star
Traits nominees rated most important to rapid career advancement
Hard work ★ Top trait 0
Emotional intelligence (EQ) ★ Top trait 0
Specific management training0
Long career at the same employer0
Average importance rating on a 1–5 scale, where 5 is very important
02Where this year’s winners are based
Winners by province
Ontario58%
British Columbia19%
Manitoba12%
Alberta, NB & Quebec12%
Alberta, New Brunswick and Quebec each account for approximately 4%, grouped here for legibility
03Career tenure
Years working in the industry
04Mentorship & career path
0%
of winners had a mentor who guided their career
0%
actively sought out a career in wealth management
Source: Wealth Professional Canada, 2026 Rising Stars nominee survey. Provincial, tenure, mentorship and career-path figures exclude blank responses.
Josh Nakesch: wealth counselling without the jargon
Winner spotlight
What makes him stand out
Zero-jargon discipline
Eliminates industry jargon entirely, treating plain explanation as the clearest proof of real expertise.
Trust-first communication
Turns difficult conversations, like market downturns, into moments that build client trust rather than erode it.
Deliberate peer learning
Studies advisors who set the industry’s bar highest and systematically replicates what makes them exceptional.
Eliminating jargon from client conversations builds trust and demystifies complex macroeconomic planning.
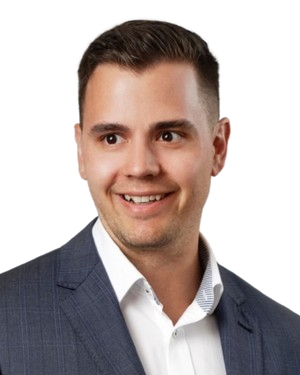
“Jargon should never be used, ever. A true demonstration of your knowledge of a subject is to be able to explain the concept in a way that your audience can understand without having previous knowledge of that particular topic or concept”
Josh NakeschKinsted Wealth
Josh Nakesch, a wealth counsellor and shareholder on the board of directors at Kinsted Wealth in Alberta, has built his practice around a single organizing idea: that wealth counselling should be done better than it has ever been done before. It is a vision he describes as deliberately unattainable – a permanently moving bar rather than a fixed destination – and one he says is underpinned by values he considers rare in the industry: integrity, respect, humility, and honesty.
Those values, Nakesch says, were present before he entered the profession, but working in wealth management “unearthed the desire to actively exploit them,” particularly because client focus is not always the industry’s stated priority. For Nakesch, the antidote to that gap is the total elimination of jargon from client conversations. “It’s so easy to approach a client meeting and talk about complicated macroeconomic policy… and use terms that aren’t understood,” he says. “Our industry is awesome at overcomplicating things and making them confusing and intimidating for the clients.”
That plain-language discipline extends into how Nakesch handles difficult conversations. Rather than avoiding hard news about underperforming investments or market volatility, he walks clients through the original rationale behind their strategy, framing turbulence as something the plan already accounted for. He describes this as an opportunity rather than a burden – particularly with clients “who typically maybe haven’t received good communication in the past” from previous advisors, where a clear explanation becomes a trust-building moment rather than a difficult one.
Nakesch also credits deliberate peer learning for his rapid development, describing a habit of identifying advisors who “set the bar very high” in the industry and studying their approach directly. He wears what he calls three separate hats – investment management, client service, and sales – and treats improvement in each as a distinct, ongoing discipline rather than a single skill set.
Q: Why do you think jargon persists in this industry if it doesn’t actually serve clients?
A: It’s not necessary. You see some of the commentaries, and I reread some of the things five different times. I’m like, ‘What is that? What are they really saying here?’
Q: What ultimately separates advisors who succeed long-term from those who don’t?
A: There’s always going to be investment strategies that outperform others and different ways of approaching that to begin with. But at the end of the day, what’s critically important is you have to establish that foundation of having those values in place to be able to approach each of those things with your clients.
Q: How do you handle conversations about market downturns or underperformance?
A: I find sitting down with the client in those situations and walking them through the principles that we had in place for the investment strategy… gives them a better sense of ‘We have a plan in place; this is part of the plan.’
Q: What drives your day-to-day approach with clients?
A: It starts with the vision: to provide wealth counselling better than it’s ever been done before. Underneath that is this mission of being a destination for wealth professionals in Canada – a leader among wealth professionals – to set that bar higher.
Q: What do clients actually want from an advisor, beyond returns?
A: They want to know that they’re working with somebody who’s going to be a good steward of their personal portfolio, their nest egg that they’ve built through their career or successful investment opportunities.
Bulla Islam: translating finance for a new generation
Winner spotlight
What makes him stand out
Financial translation
Converts complex financial concepts into everyday language, using his own past confusion as a guide.
Generational insight
Turns the age gap with the advisors he coaches into an advantage, teaching emotional connection over transactions.
Financial literacy mission
Driven to make financial knowledge accessible to everyone, not gatekept by industry insiders.
Coaching advisors to bridge generational gaps through emotional intelligence and accessible language, Islam argues, is what keeps clients loyal for the long run.
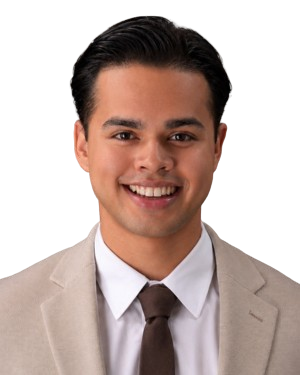
“The world of finance can be so complicated to so many people, but if you are somebody who is able to translate it into everyday language… you become really good at what you do”
Bulla IslamCanada Life
Bulla Islam, a business development manager at Canada Life based in Vancouver, British Columbia, doesn’t work with retail clients directly. His job is to coach financial advisors – often decades his senior – on how to build stronger practices. That generational gap could be a liability, but he has turned it into his defining professional strength.
“I would say it’s a marriage of two things,” Islam says of his approach. “I naturally have a thing for connecting with people… and being able to marry that with my technical abilities.” The second half of that marriage, he says, comes down to translation: taking complex financial concepts and “verbalizing them in a way that is digestible to the normal person.”
That skill was not formally trained; Islam traces it to his own early struggles with financial literacy. “I had a lot of trouble understanding financial concepts. I was never financially savvy,” he says. “It’s only upon stumbling upon the industry that I was like, ‘Okay, this is actually something more people should know of.’” He now treats that gap-closing as a personal mission: “I need to make this information more readily available to the regular person on the street so that financial information is not gatekept like it was 10 years ago, 20 years ago.”
Islam is candid about the credibility gap his age creates when meeting the advisors he coaches in person for the first time. Rather than downplaying his age, he reframes it as generational insight: “My generation is naturally more aware in terms of emotional connections, how money plays a role in your psyche… you connect money to them, specifically to them. And that’s how you connect with each client.” He argues that advisors who build those deeper connections retain clients through bad market cycles precisely because they function as more than financial technicians – acting as a coach or a therapist.
On AI, Islam is measured. He acknowledges that transactional advisors face displacement but argues trusted relationships are AI-resistant: “You’d still want a doctor to confirm your symptoms… we’re talking about your financial health here. So you would definitely want a professional, a qualified professional to take care of you.”
Q: How do you help the advisors you coach think about client relationships differently?
A: It’s not one that’s transactional – it’s not just, “I give them money, they act on my behalf.” It’s more than that. It’s an intimate relationship built on trust, built on honesty, and built on reliability.
Q: What’s the payoff for advisors who build that kind of trust?
A: That’s how a lot of advisors actually grow their practices. They have one client whom they take excellent care of, and that client brings all their friends, their family, their kids, and their grandparents. Now you have six other accounts from that one account that you just took care of.
Q: Why does this matter more in today’s “attention economy”?
A: In today’s world, we live in an attention economy. It’s really easy to get lost in transactional relationships. So when you find that special person who is genuinely wanting to take care of you, it’s almost a no-brainer for clients.
Q: Where did this coaching philosophy come from for you personally?
A: I think somebody did that for me – held my hand, taught me. I feel like I have a responsibility to pass that along, to give advisors the best practices and tips that can make their relationship with their client a special bond.
Q: Will AI-driven tools replace financial advisors?
A: You can get any information with the click of two buttons, and it will probably speak to you in a more articulate way than any other human being. But how do you trust that information? You really can’t.
Mordechai Kuhnreich: trust over transactions
Winner spotlight
What makes him stand out
Planning-first approach
Replaces transactional portfolio reviews with real financial planning, turning it into his strongest referral engine.
Built from scratch
Grew his practice from cold calls alone, with no inherited book of business or family handoff.
Tech-forward practice
An early adopter of automation and AI tools most of the industry has yet to scale beyond experimentation.
Comprehensive financial planning software and clear baseline education replace outdated portfolio reviews to win over underserved clients.
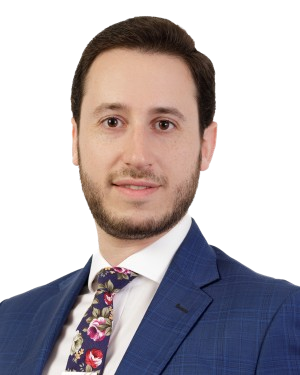
“When I show people a financial plan in the software, it blows people’s minds. And it’s sad that many people are impressed by it, but that’s the reality we’re in”
Mordechai KuhnreichLakeview Wealth Management – Wellington-Altus Private Wealth
Mordechai Kuhnreich, a wealth advisor and portfolio manager at Lakeview Wealth Management – Wellington-Altus Private Wealth in Toronto, Ontario, built his practice from nothing – no inherited book of business, no family handoff, just cold calling. That grind, he says, was a deliberate choice: “I was never one of the lucky ones who has a parent that has a business to hand to me… I started with cold calling. It was the real old-school grind.”
Since 2025, Kuhnreich says his business has been turning the corner, with growth from markets and referrals overtaking new business generated through outbound marketing. The reason, he says, comes down to what older advisors historically left out of client relationships: planning. “We have our 60/40 balanced portfolio,” he says, referring to the traditional 60 percent stocks, 40 percent bonds asset mix, “We’ll meet to review the returns; we’re not really going to talk about planning because that wasn’t really done back in the day. When I started, everything was based around planning. You start with a plan, and you go from there.”
That gap between old-school portfolio management and planning-led advice has become his primary referral engine. This instinct for demystifying finance also extends into everyday financial literacy. Kuhnreich recalls a client asking him to explain a simple fix to her granddaughter: using an existing, unused line of credit to pay down high-interest credit card debt. “Seems so simple,” he says, “but she couldn’t get over it. She’s like, ‘Well, why would I want to take more debt?’” For Kuhnreich, moments like that prove promoting basic financial literacy matters as much as the products advisors sell.
Kuhnreich connects his approach to a broader demographic shift reshaping the profession: “The average age of advisors in Canada is 50-plus,” he says, pointing to a scarcity of professionals in the 40–55 age bracket that has left the industry without a gradual generational handoff. Kuhnreich embraces technology-forward workflows, including a heavily automated customer relationship management system built in 2020–2021 and early broad adoption of AI tools for note-taking and stress-testing. According to an Accenture survey of 500 financial advisors across the United States and Canada, 96 percent believe generative AI can revolutionize client servicing, but only 41 percent of firms have scaled its adoption. Kuhnreich’s early integration places him far ahead of the norm.
Q&A with Mordechai Kuhnreich
Q: What’s driving your recent growth?
A: Growth from markets and referrals is now overtaking new business from marketing. A lot of referrals come from clients whose older advisors focused on a 60/40 balanced portfolio and review of returns, without ever talking about planning.
Q: What convinced you that planning matters more than chasing returns?
A: You start with a plan, and you go from there. That’s really what people look for – an advisor that’s going to make them feel comfortable that they’re on the right track.
Q: What’s kept you motivated as your reputation has grown in your own community?
A: Getting the name out there and being a household name is such a differentiator. That’s the biggest reward I can get when someone in the community just heard about me.
Q: How has automation changed the way you run your practice day to day?
A: Really, using technology has taken away all that administrative stress and changed things quite a bit.
Q: What’s differentiated your investment approach as your practice has grown?
A: Our team definitely has a focus on private investments – private equity, private credit, and private real estate. We target about a 25–30 percent weight for private investments, which I think is not the most typical.
Firms must adopt communication-first training and structured mentorship programs to capture an aging demographic’s shifting wealth assets. If the experiences of this year’s Rising Stars are any indication, the wealth management industry’s next competitive battleground will not be fought over returns, product access, or even fee structure. It will be fought over communication.
Canada’s advisor population is aging rapidly: according to Investor Economics’ research on Canada’s aging financial advisor population, the average advisor age has climbed to almost 53, up from about 50 in 2015, with advisors over 55 now representing nearly 40 percent of all full-service brokerage advisors and managing roughly half of all assets under management (AUM) nationally. Firms that fail to develop plain-language, planning-led communication skills risk losing clients actively shopping for better service, as well as the next generation of investors.
Data spotlight
Canada’s aging financial advisor population
Average age of financial advisors in Canada, 2015 vs. today
Bars scaled from a baseline of 0 to a shared maximum of 55 for proportional accuracy
Of every 10 full-service brokerage advisors in Canada…
4 are over age 55 — and that group alone manages roughly half of all assets under management (AUM) nationally.
Source: Investor Economics (an ISS Market Intelligence company)
The referral patterns described independently by Kuhnreich and Islam point to a specific and growing client segment: people adequately served by traditional metrics who were never given a real financial plan and are actively migrating to advisors closing that gap. Tehranchian’s call for structured mentorship programs with defined goals speaks directly to why succession planning is a growing challenge for exiting advisors, as more experienced advisors near retirement without an equivalent cohort ready to replace them.
What Canada’s top financial advisors and professionals under 40 have in common
Three advisors, three firms, and three different roles within the wealth management ecosystem – and the same answer arrived at independently, regarding what builds a lasting client relationship.
-
Josh Nakesch eliminates jargon entirely.
-
Bulla Islam translates complexity for a new generation.
-
Mordechai Kuhnreich replaces transactional portfolio reviews with mind-opening financial plans.
What unites this year’s Rising Stars is a shared refusal to let complexity substitute for genuine client understanding. The advisors best positioned for the next decade of Canadian wealth management are not the ones who know the most jargon but the ones who use the least of it.
- Anshul Panday
Director of Fund Operations
Wealthsimple - Arandeep Biryah
Wealth Advisor/Financial Planner
Nour Private Wealth - Cameron Cox
Senior Investment Analyst
Cidel - Carly Gilmore
Certified Financial Planner
Noble Pannu Wealth Management - Devon Bailey
Investment Advisor
Tetrault Wealth - Jordan Kaczmarzyk
Vice President
Fidelity Canada - Jordan Mullin
Associate Relationship Manager
Sagard - Keeley Simpson
Chief Executive Officer, Chief Compliance Officer, and Portfolio Manager
Aretec Wealth - Lauren Rudolph Heselton
Investment Counsellor
Kerr Financial Group - Malik Besseghieur
Vice President, Sales
iA Clarington - Meagan S. Balaneski
Portfolio Manager
Aligned Capital Partners - Michael Hogan
Chief Revenue Officer
Four Eyes Financial - Nathan Di Lucca
Co-Founder and Chief Technology Officer
OneVest - Paul Bilenki
Senior Vice President
Oak Hill Asset Management - Peter Hatziioannou
President and Co-Founder
XIB Asset Management - Ryan Bevelander
Associate Wealth Advisor
Nicola Wealth - Shauna Tremblay
Financial Advisor
Desjardins Financial Security Independent Network – Toronto West Centre - Spencer Vermette
Investment Advisor
Wellington-Altus
Insights
FAQs
How were the 2026 Rising Stars selected?
Companies nominated professionals aged 40 or under as of September 30, 2026, working in roles impacting the wealth management industry. The Wealth Professional editorial team assessed nominees on performance over the preceding 12 months to select the 27 winners.
What defines a Rising Star in Canadian wealth management?
According to Tina Tehranchian, C.M., resilience, grit, and a pursuit of excellence define a Rising Star, paired with plain-language client communication as a vital practical skill.
Why are younger financial advisors
gaining ground on more established peers?
Winners point to a growing client segment that received impersonal service from previous advisors without a formal financial plan and who are actively seeking advisors who communicate clearly.
Will AI replace financial advisors?
Opinions vary: Bulla Islam argues AI may displace purely transactional practices, but relationship-based advisors remain essential, while Mordechai Kuhnreich extensively integrates AI into practice administration and client communications.
What should firms do to develop
their next generation of advisors?
Tehranchian recommends structured mentorship programs holding both mentor and mentee accountable to measurable goals, alongside broad educational outreach regarding wealth planning careers. Catherine Milum, president and CEO of iA Clarington Investments, goes a step further, urging firms to move beyond mentorship into sponsorship – where a mentor actively advocates for a mentee and creates real opportunities for them, not just regular check-ins.
How is the age gap in Canada’s
wealth management industry changing?
With the average advisor age approaching 53 (per Investor Economics) and older advisors managing roughly half of national AUM, the scarcity of professionals in the 40–55 bracket points to a rapid generational shift over the coming decade.
To uncover the most promising young professionals in the Canadian wealth management industry, Wealth Professional launched its 10th annual Rising Stars report through a rigorous marketing and survey process, leveraging its connections to thousands of advisors across the country. Starting in June, companies were given the opportunity to nominate professionals for consideration based on their performance and achievements over the past 12 months.
To be eligible, nominees had to be age 40 or younger (as of September 30, 2026) and working in a role that relates to, interacts with, or impacts the wealth management industry. When reviewing the nominations, WPC concentrated on those who have committed to a career in the industry and clearly hold a passion for wealth management.
After reviewing all the nominations, the WPC team whittled down the list to 27 deserving winners.
The Rising Stars report is proudly supported by the Canadian Association of Alternative Strategies & Assets and the Canadian Association of Urban Financial Professionals.