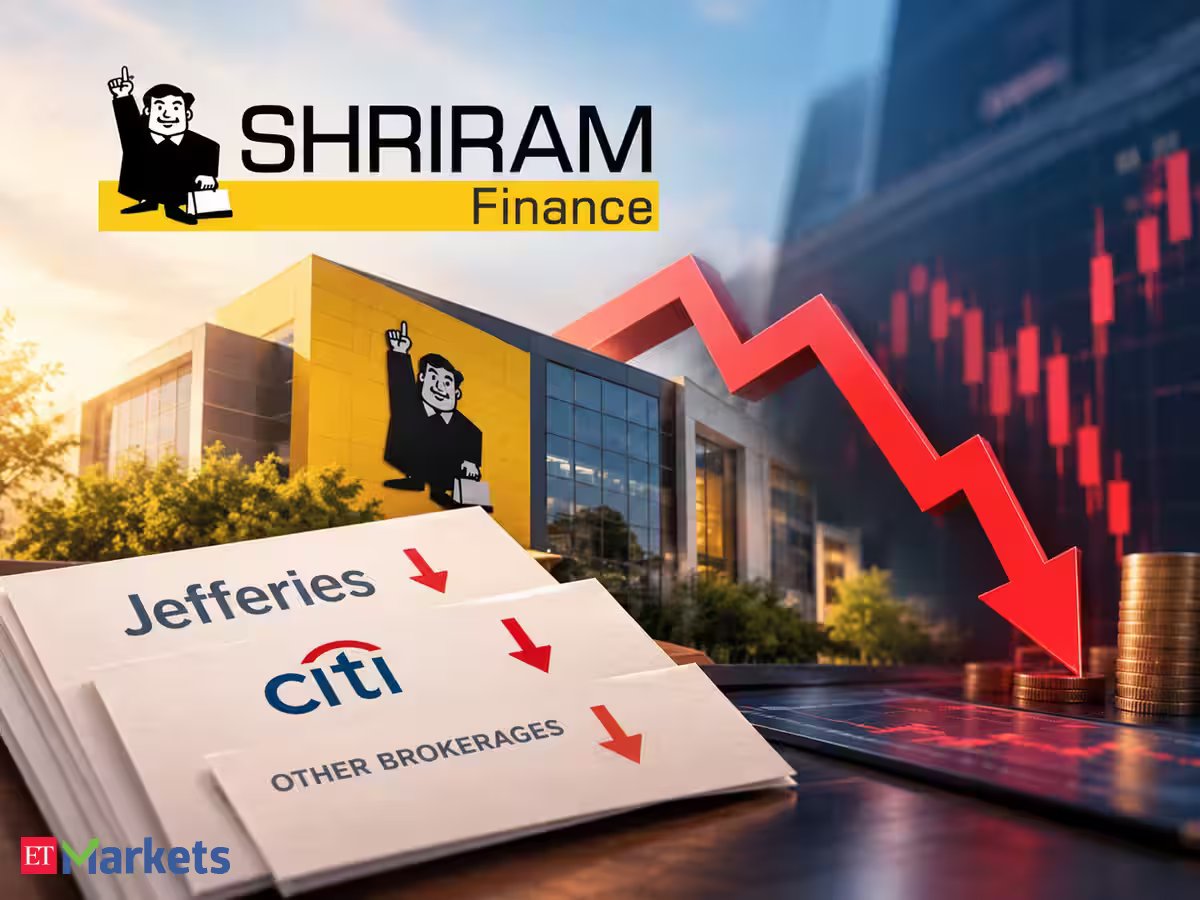
Shriram Finance shares crash 6% as Jefferies, Citi, and other brokerages slash target prices after Q2 results. Why do they still say ‘Buy’?
The stock dropped to Rs 811 on the NSE in morning trade. Shriram Finance reported a 59% year-on-year rise in standalone net profit to Rs 3,677 crore for the quarter ended September 2026, supported by higher net interest income and lower finance costs. Its net interest margin improved to 9.52% from 8.19% a year earlier.
Net interest income (NII) rose 38% YoY to Rs 8,661 crore, driven by a nearly 16% rise in interest income to Rs 13,669 crore, while interest expenses declined around 10% to Rs 5,008 crore. Operating profit increased more than 53% YoY to Rs 6,809 crore, while the cost-to-income ratio improved to 22.52% from 27.76% a year ago. Core operating profit, which excludes other income, rose 53.5% to Rs 6,682 crore.
Also read | Shriram Finance Q2 profit jumps 59% YoY to Rs 3,677 crore on strong interest income, lower funding costs
Jefferies on Shriram Finance share price
Jefferies slashed its target price to Rs 1,145 apiece from Rs 1,210 apiece for the shares of Shriram Finance, while maintaining its ‘Buy’ call on the stock. The latest target price implies more than 32% upside potential from the stock’s previous closing price of Rs 865 apiece on NSE.

The international brokerage noted that the company’s September quarter profit was 3% above estimate, as stronger NII and lower opex more than offset higher credit costs. AUM growth accelerated and NIMs expanded sharply QoQ, it added.
Jefferies highlighted that the company’s management noted stress in drought-hit areas and has raised credit cost guidance. It said the company’s AUM should grow at 17% CAGR over FY26-28. NIMs should be resilient amid rate hikes, but credit cost may stay elevated near term, it added.
Citi on Shriram Finance share price
Citi also maintained its ‘Buy’ call but reduced its target price to Rs 1,100 apiece from Rs 1,200 apiece for the shares of Shriram Finance. The latest target price implies 27% upside potential. It noted that the company’s Q2 earnings were in line with estimates, but NIM tailwinds were offset by higher credit costs, ET Now reported.
Equity buffers expected to keep margins elevated in the near term before normalisation, Citi said, adding that it views the company’s AUM growth guidance as conservative. While doubt conditions and elevated crude prices remain key headwinds, Citi said its target price cut reflects lower normalised return on equity (RoE).
Motilal Oswal on Shriram Finance share price
Motilal Oswal Financial Services slashed target price to Rs 1,155 apiece, implying 33% upside potential, while maintaining its ‘Buy’ call on the shares of Shriram Finance. It noted that weak monsoons lead to higher slippages and writeoffs, while highlighting that credit cost guidance has been raised.
The company indicated that credit costs could rise temporarily by 30-40bp over the next one or two quarters due to seasonal stress in affected geographies, but they are still expected to remain below 2.3% for FY27, Motilal Oswal noted, adding that elevated stress is mainly attributable to deficient rainfall and seasonal pressures in select regions, with no evidence of widespread portfolio deterioration.
Lower agricultural output could weigh on rural incomes, consumption, and borrower cash flows in the coming quarters. The asset quality outlook for the company remains cautious amid these near-term headwinds, the domestic brokerage added.
Shriram Finance share price
Shriram Finance shares have fallen more than 12% in a week and 18% in a month, with the stock overall falling over 20% in 2026 so far. In one year, the shares of the company have, however, gained around 14%.
Over the longer term, Shriram Finance shares have delivered multibagger returns of more than 126% in three years and 166% in five years. The company has a market capitalisation of nearly Rs 1.93 lakh crore.
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.