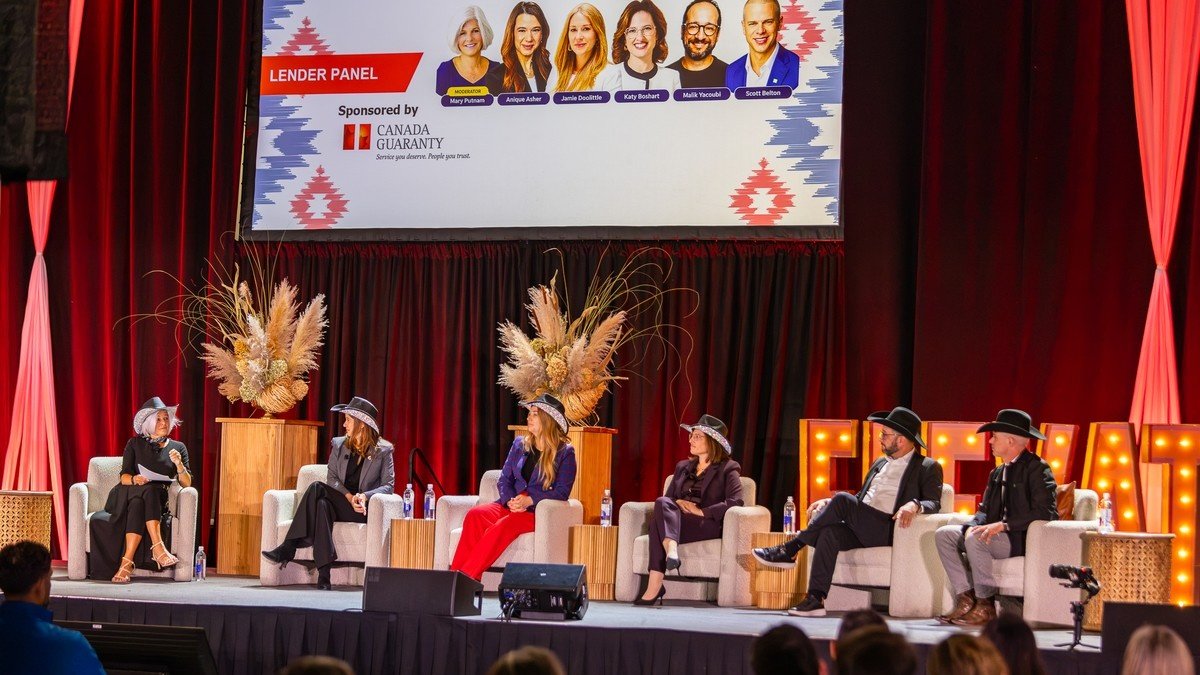
Lenders bullish on broker growth in 2027, MPC panel hears
Canada’s major mortgage lenders are setting their sights on further broker-channel growth in 2027, even as higher borrowing costs and a sluggish housing market cloud the outlook for new purchases.
At Mortgage Professionals Canada’s National Mortgage Conference in Calgary, executives from Scotiabank, BMO, Manulife Bank, Nesto Group and TD Bank outlined plans to expand their broker businesses through new products, technology investments and improved service.
Nesto Group co-founder and CEO Malik Yacoubi offered one of the panel’s more ambitious growth projections, saying the company expects another 50% increase in broker-channel business in 2027, following similar growth this year.
“We’ll be growing by 50% in the broker channel again,” he said.

TD Bank is targeting double-digit growth, according to Scott Belton, senior vice-president of specialized sales, who acknowledged the bank has work to do on turnaround times and simplifying its processes.
“We will absolutely get faster and take out friction,” he said. “It’s not a strength of ours in the broker channel right now.”
Manulife Bank president and CEO Katy Boshart said the bank expects a third consecutive record year in its broker business, while BMO’s Jamie Doolittle pointed to further opportunities following its expansion into Western Canada and Quebec this year.
Scotiabank’s Anique Asher was similarly upbeat, citing improved mortgage activity over the past two months, although she expects the recovery to be gradual.
The panel was moderated by Mary Putnam, senior vice-president of sales and marketing at Canada Guaranty.
Housing outlook: Renewals dominate as purchases lag
Much of the anticipated growth reflects lenders’ efforts to expand their broker businesses rather than expectations of a broad housing rebound.
Panelists said renewals, mortgage switches and refinancing continue to generate significant activity, while purchases remain uneven across the country.

Belton pointed to stronger conditions in Saskatchewan and continued weakness in condominium markets in Toronto and Vancouver. “I don’t think we’re out of the woods yet,” he said, warning that further rate increases could weigh on demand.
Doolittle said BMO is seeing more purchase activity in Alberta and other markets where employment, income growth and affordability are stronger. She also noted continued demand among first-time buyers, including those receiving gifted down payments.
Still, she expects switches and refinances to remain major sources of business in 2027.
AI: Lenders target faster mortgage processing
Lenders are also turning to artificial intelligence to address longstanding bottlenecks in mortgage processing.

Belton pointed to TD’s deployment of agentic AI, which has reduced document-review turnaround times in its internal channels from an average of 15 hours in the queue to three minutes. He said similar improvements are expected to reach the broker channel in the coming quarters.
Scotiabank is also expanding its use of AI in underwriting and pre-funding operations. Asher said the bank is deploying automated document checks that are expected to reduce manual intervention by approximately 25%.
Yacoubi argued that lenders should be thinking far beyond incremental productivity improvements.
“It will not change the relationship between a broker and a client, the trust, but everything behind will change and needs to change,” he said.
Boshart agreed that technology should support rather than replace human expertise, giving brokers and underwriters more time to focus on advice and complex lending decisions.
Funding: Rising costs drive competition for deposits
Volatile bond yields and funding costs are making it harder for lenders to maintain consistent mortgage pricing.

Boshart described the funding and securitization environment as a “roller coaster,” with rapid changes in yields and spreads affecting lender profitability.
“A rate sheet that we publish on Monday might be completely irrelevant by the time you get to Wednesday,” she said.
Belton pointed to another challenge: competition for deposits. He said TD’s deposit growth was just 1.8%, despite leading the major banks on the measure he cited, while loan portfolios continued to expand.
The pressure is pushing banks to place greater emphasis on attracting customers who bring deposits and other banking business, rather than competing solely on mortgage rates.
At Scotiabank, Asher said approximately 90% of broker-channel business now comes through its Mortgage Plus offering, which combines mortgages with other banking products.
She added that 40% of broker-originated clients become primary banking customers within six months, compared with roughly 31% to 32% through the bank’s retail channels.
Regulation: Lenders weigh OSFI’s mortgage limits
The panel also addressed OSFI’s loan-to-income limits, which restrict the proportion of new uninsured mortgages lenders can originate above specified income multiples.

Belton questioned whether the additional requirements are always appropriate, particularly for high-net-worth borrowers whose financial circumstances may not be fully reflected in their income ratios.
“I think it sometimes makes us make marginal decisions that we would prefer not to,” he said.
He nevertheless defended the existing mortgage stress test, crediting qualification requirements with helping borrowers withstand substantial rate increases without widespread mortgage losses.
Boshart said the LTI limits have required more portfolio monitoring but have not materially changed Manulife’s lending appetite.
Broker channel: Balancing growth and digital competition
The growth of direct-to-consumer lending and digital renewals also raised questions about how lenders balance their investment in brokers with their own distribution channels.

Asher said digital renewals accounted for approximately 35% of Scotiabank’s renewals in the third quarter, but argued that self-service and advice-based channels can coexist.
Yacoubi said Nesto uses its direct-to-consumer platform to test new mortgage products before making them available to brokers.
Belton acknowledged that TD’s multichannel approach has created challenges, although he said the bank has largely addressed them and will continue making improvements.
For brokers, Doolittle stressed the importance of maintaining contact with existing clients, particularly ahead of renewals, before they simply accept an offer from their current lender.
The message from the panel was that lenders see considerable room for broker-channel growth in 2027, even without a strong recovery in home purchases. But capturing that business will increasingly depend on faster service, more flexible products and stronger customer relationships.
Visited 3 times, 3 visit(s) today
Anique Asher bmo Jamie Doolittle Katy Boshart lender panel Malik Yacoubi manulife bank Mary Putnam mortgage lender panel mortgage professionals canada Nesto Group scotiabank Scott Belton td bank
Last modified: October 21, 2026