Is MP Materials Stock Still a Buy After Its Recent Pullback?
MP Materials (MP -2.38%) has been a losing stock in 2026. After a stellar year in 2025, in which it was one of Wall Street’s hottest mining stocks, MP has tanked over 50% since last October.
And yet MP’s core strength hasn’t changed: It is still one of the few American companies capable of mining and refining rare earths, the critical materials used in everything from electric vehicles to electronics. It still enjoys support from the U.S. government, including a stunningly high price floor for its neodymium-praseodymium (NdPR) and a 10-year agreement to buy permanent magnets from its planned magnet factory (10X Facility).
Things are looking good in MP’s future, but does that mean the stock is a buy right now? Let’s take a look.
MP has celebrated big wins in 2026
MP Materials has long been America’s rare-earth champion. It owns Mountain Pass, the only active and scaled rare-earth mine and processing site in North America. MP used to sell much of its concentrate to China for processing, but with trade tensions escalating, it’s now aiming to become a fully integrated mine-to-magnet company.
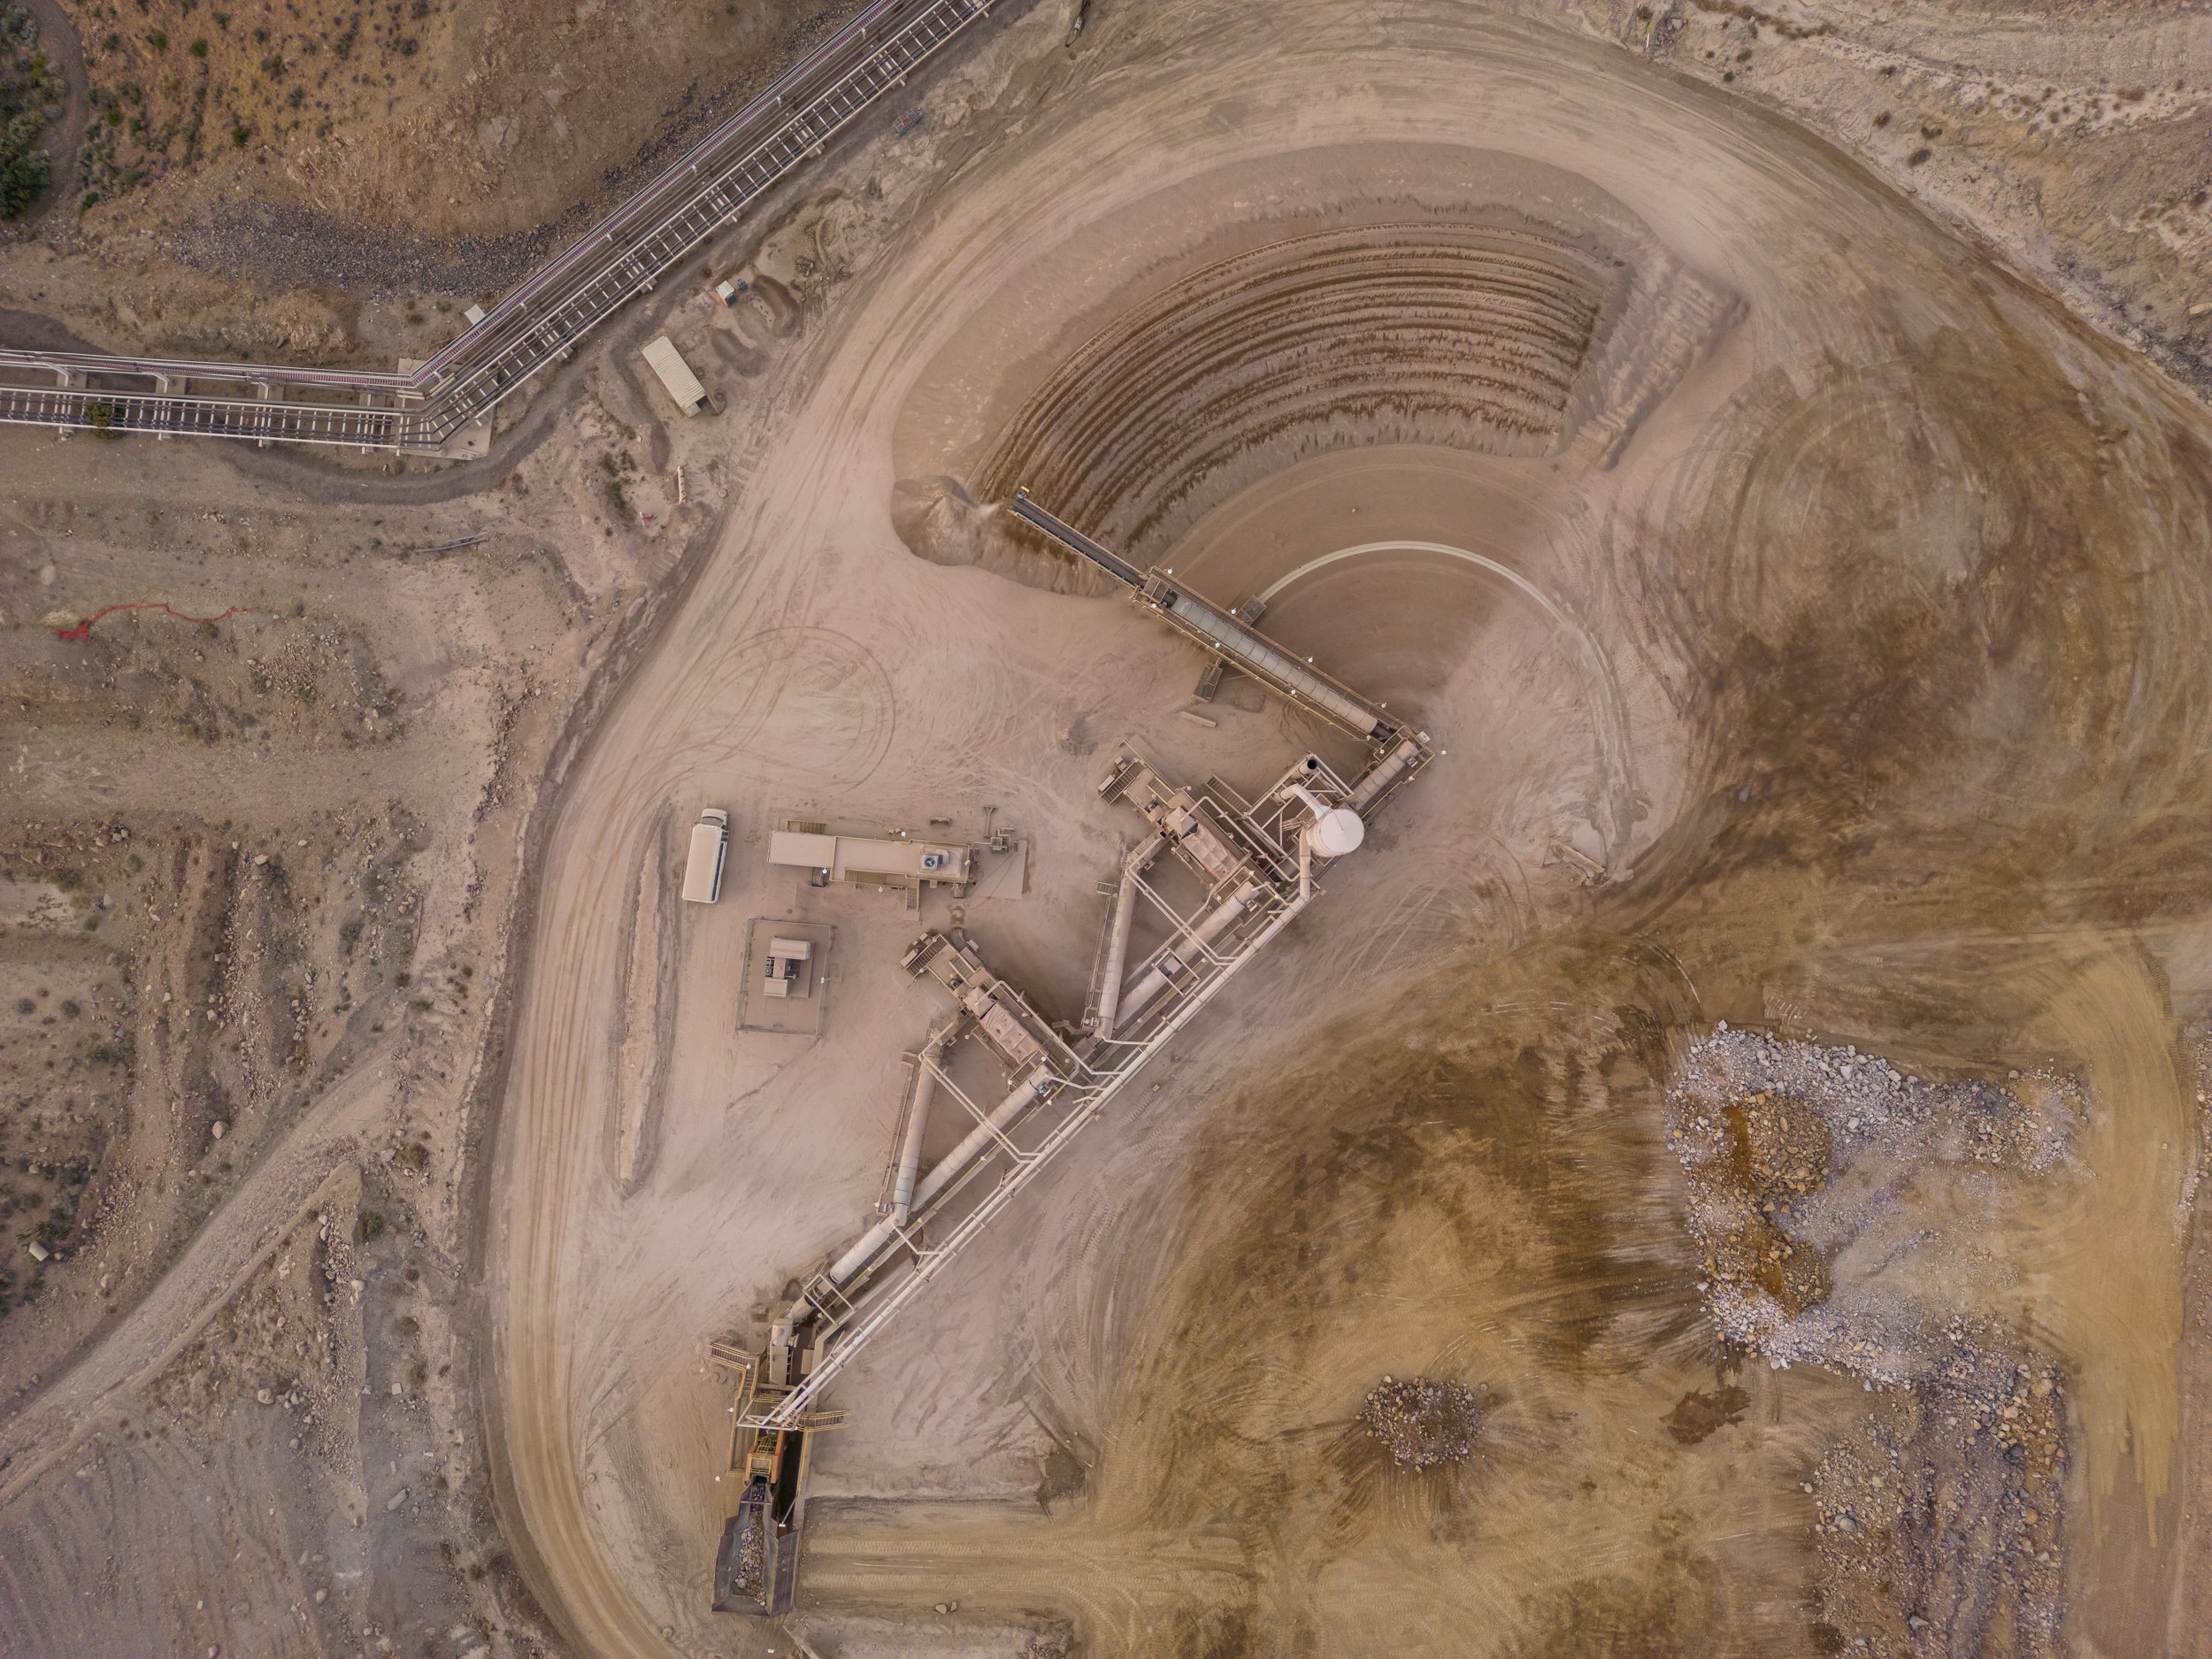
Image source: MP Materials.
It’s making impressive progress, too. In the second quarter, revenue surged 80% year over year to roughly $109 million, while sales volumes of refined NdPR more than doubled. At the same time, its magnet factory in Texas has been gearing up for commercial production, with first deliveries to General Motors expected in the fourth quarter. MP’s biggest magnet factory — 10X — is also expected to begin commissioning in 2028.
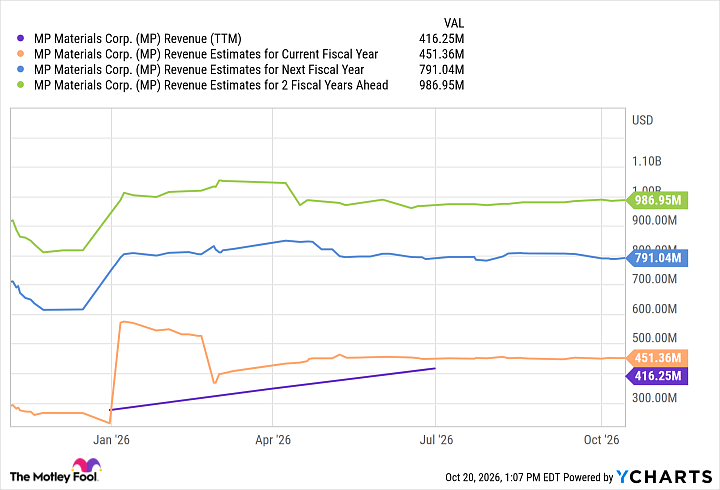
All in all, MP’s revenue is expected to more than double over the next two years, as the chart below shows.
Data by YCharts
Is MP Materials a buy right now?
MP Materials stock has fallen sharply from its 52-week high, even while the business has been improving. That doesn’t, however, mean that investors are missing something, or that the market is pricing the stock unfairly. Indeed, my suspicion is that MP Materials — like a slew of other speculative stocks that briefly caught fire last year — has faced a long-coming reckoning, that is, a re-evaluation of its fundamentals.
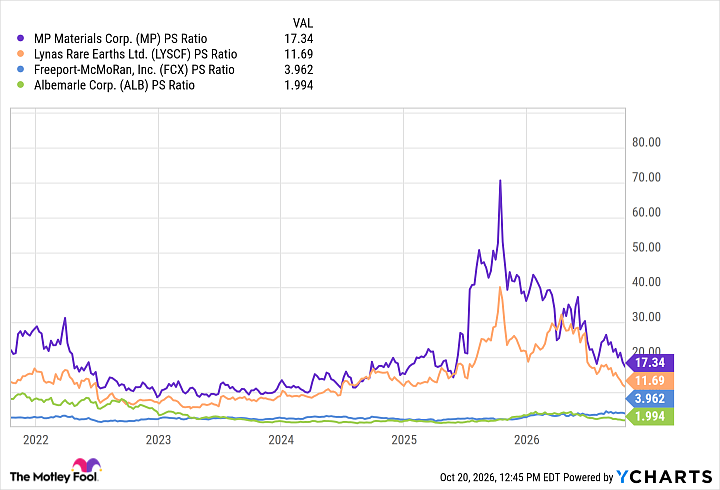
To put it plainly, MP has traded at a premium, and growth investors are simply not having it anymore. To illustrate what I mean, consider, for a second, the following chart.
Data by YCharts
This is a five-year history of MP’s price-to-sales ratio, a common metric for evaluating how expensive a stock is relative to the revenue it generates. As you can see, MP’s valuation has fallen dramatically, from about 70 times sales in late 2025 to around 17 today. As you can also see, a P/S reading of 17 is still higher than that of other mining stocks.
So, yes, MP stock may have experienced a setback, but that doesn’t mean it’s cheap. In fact, relative to the last five years, investors are still paying quite a lot for future growth.
That doesn’t mean MP isn’t a buy right now, only that the valuation will make it volatile in the short-term. This isn’t a stock I would recommend for money that you’ll need over the next half-decade. But if you can still invest long-term (five years or longer), picking up a few shares of MP at this price could produce a handsome gain.