Why Chase is rethinking workflows as AI adoption accelerates
Processing Content
- Key insight: JPMorganChase’s AI experience suggests that faster execution of individual tasks alone does not guarantee better business outcomes. Measuring progress and redesigning workflows are essential.
- What’s at stake: As AI agents take on greater responsibilities, banks must balance opportunities for productivity gains with the need for stronger governance and human oversight.
AI is helping software developers write code faster. But what happens when testing, documentation and deployment cannot keep up?
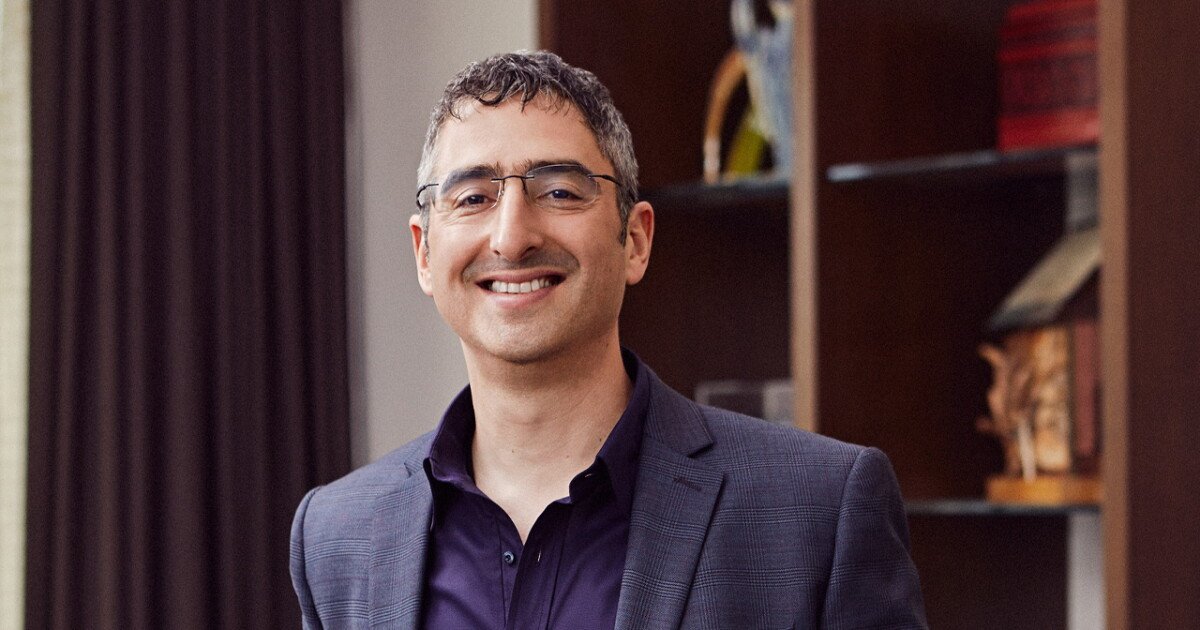
That is a priority for JPMorganChase as it expands AI adoption. In a recent interview,
His observations offer three lessons for banks seeking to translate AI capabilities into measurable business results.
Measure impact before expecting financial returns
Measuring AI’s contribution to business performance is more complicated than measuring how quickly it completes individual tasks. Software development provides an example. AI can help engineers write code faster, but testing, documentation, security reviews and deployment may take as long as they did before. Faster coding could simply move the bottleneck elsewhere. Chase is using AI to generate documentation when software is deployed and analyze sanitized production logs to help engineers resolve problems. These applications address activities surrounding software development rather than coding alone.
Haus also discussed opportunities to accelerate products that previously required years to complete, reduce maintenance burdens and improve incident resolution. These benefits matter, although their financial contribution may not be immediately apparent. Measuring employee productivity was difficult even before AI, he noted. Employees who save time may use that capacity to develop additional capabilities rather than reduce expenses. The nature of their contribution is changing as well. “We don’t hire engineers to write code. We hire engineers to know which code to write,” Haus said.
This is why I have
Redesign workflows rather than simply automate existing tasks
One implication of faster software development is that banks may need to rethink the entire development process. Accelerating coding offers limited benefits if subsequent activities cannot accommodate the increased output. Chase is looking at opportunities to apply AI throughout the software development lifecycle, including documentation and incident resolution, rather than treating individual applications as isolated productivity tools. The broader opportunity is to consider how work should be organized when AI can perform activities that previously required substantial human effort.
Haus offered another example involving robotic process automation, or RPA. Banks have long used RPA to automate repetitive activities across applications that were not necessarily designed to work together. One approach to adopting agentic AI would be to replace those automations with agents performing essentially the same tasks. But Haus questioned whether that would be the best use of the technology. AI could instead help modernize the underlying applications, potentially eliminating the need for some automated workarounds. “The magic isn’t automation. Automation we could do before,” he said. The opportunity lies in reimagining how activities are performed.
Strengthen governance as AI assumes greater responsibility
As AI moves from providing information and recommendations to executing actions, banks face a more consequential question:
The issue came into sharper focus during JPMorganChase’s third-quarter
The governance considerations are consistent with those raised by Gill Haus in our interview. Haus emphasized that agentic AI is still in its early stages and evolving rapidly, making it particularly important for banks to establish appropriate permissions and controls as the technology advances.
“RPA is deterministic,” Haus observed. “Agentic is not.” An AI agent may help develop better software, but that does not mean it should replace deterministic processes for financial transactions. Haus also highlighted the importance of trusted data sources, access permissions, continuous monitoring and mechanisms for escalating problems to human supervisors. As agents assume greater responsibility, banks need to define their authority, establish acceptable performance standards and determine when human intervention is required.
Human judgement therefore remains essential even as its role changes. With employee-facing applications, people may review individual recommendations before acting. As AI systems become more autonomous, human responsibilities increasingly involve setting objectives, establishing boundaries and evaluating performance. Governance becomes more consequential as AI adoption deepens, not because banks can eliminate risk, but because they must manage increasingly complex interactions between people and machines.
The experience at Chase illustrates how the three pillars of measuring, scaling and governing AI are connected. Measurement helps banks identify where AI is making a difference. Workflow redesign translates those improvements into broader impact across the organization. Governance enables banks to expand AI’s responsibilities while maintaining appropriate oversight. All three are necessary throughout adoption, although their relative importance changes as AI takes on more responsibility.
The long-term opportunity is not simply to deploy more AI applications or automate more tasks. It is to improve how people and AI work together, redesign the processes in which they operate and demonstrate that the resulting changes create value.