October MPC minutes: Rate cuts off table as members flag rising inflation | Finance News
With headline inflation projected to touch the upper tolerance limit of 6 per cent in the third quarter of the current financial year, the Reserve Bank of India’s (RBI) Monetary Policy Committee (MPC) has signalled that rate cuts are off the table in the near term. Minutes of its October meeting, released on Wednesday, show members increasingly concerned about inflation spreading beyond food and fuel. While all six members voted for a 25-basis-point hike in the repo rate to 5.50 per cent, Nagesh Kumar and Ram Singh opposed the shift in the monetary policy stance from neutral to calibrated tightening.
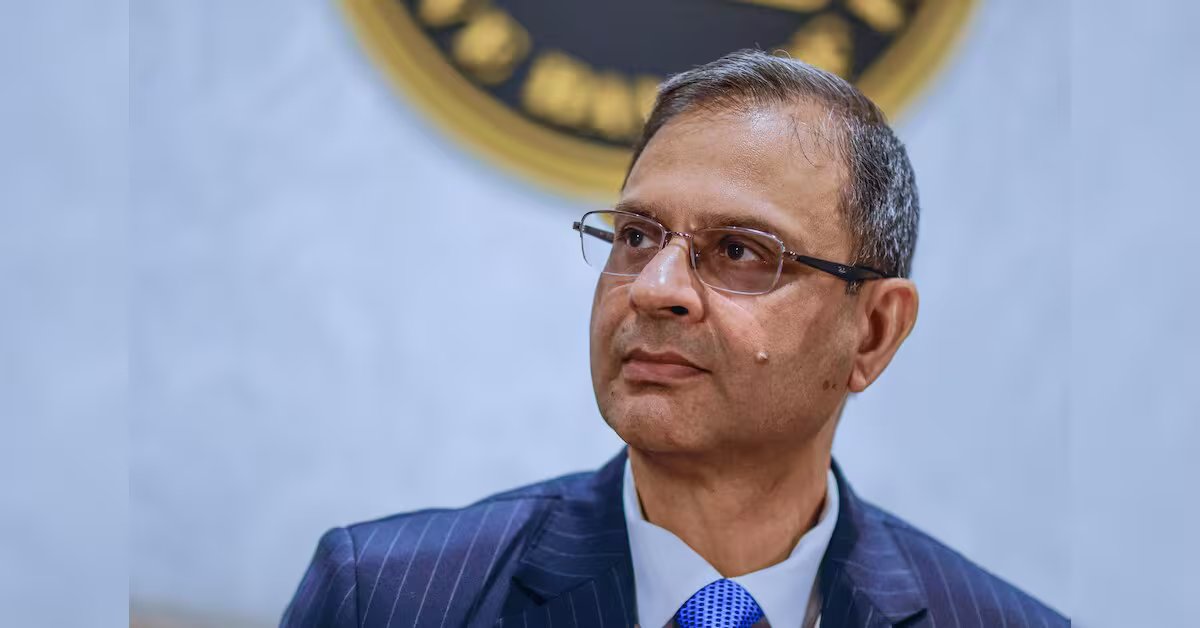
The minutes of the October 5-7 meeting show that the change in stance was intended to signal a shift in the policy outlook. RBI Governor Sanjay Malhotra said it conveyed that rate cuts were unlikely in the near term, leaving a rate hike or a pause as the possible next moves. The duration and extent of any tightening cycle would depend on underlying inflation, the spread of price pressures and the second-round effects of the supply shock, he said.
The case for raising rates rested on a change in the inflation outlook. Headline consumer price index (CPI) inflation rose to 4.8 per cent in August from 4.5 per cent in July, while core inflation increased to 4.2 per cent. The MPC projected inflation at 5.2 per cent for 2026-27, with the third quarter expected to see it touch 6 per cent, the upper end of the RBI’s tolerance band.
While members agreed on the need for a rate hike, they differed on the extent to which inflation had become broad-based and persistent. Saugata Bhattacharya said price pressures were getting entrenched, pointing to wholesale input prices rising close to 9 per cent and the pass-through of higher costs to consumers. He also questioned whether monetary conditions were too accommodative, arguing that current and projected real interest rates were not consistent with price stability.
“Too rapid a policy rate adjustment risks constricting growth and hence growth-led capital flows,” said Bhattacharya.
Indranil Bhattacharyya called for the MPC to move away from a cautiousness bias and act pre-emptively. He cited sharp increases in weighted median and trimmed-mean inflation, along with higher inflation expectations among urban and rural households.
“Inflation outlook merits greater attention, given supply side pressures from crude and food prices are unlikely to relent quickly,” said Bhattacharyya.
Singh also pointed to signs of inflation broadening, citing the RBI’s September household survey, which showed the median three-month-ahead inflation expectation rising to 9.9 per cent. He warned that the real repo rate could turn negative under the projected inflation trajectory. However, he favoured gradual and moderate rate increases rather than keeping rates high for an extended period. A tightening stance, he argued, could signal a prolonged rate-hike cycle and undermine the growth-supportive measures taken in recent months.
“Expectations of significant rate increases can undermine demand not only in interest rate-sensitive sectors but also drag on recent momentum in private investment,” singh said.
Kumar, however, maintained that inflation was largely driven by supply-side factors, with little evidence of overheating or a broad-based increase in prices. He argued that the neutral stance remained appropriate amid geopolitical and trade uncertainties.
“While inflation is driven largely by supply-side factors and does not show any signs of overheating of the economy nor of generalisation, it is important to manage inflationary expectations,” Kumar said.
Deputy Governor Poonam Gupta, who proposed the change in stance, said inflation was largely driven by external supply shocks and showed limited signs of becoming entrenched. However, she argued that the MPC could not wait for definitive evidence of second-round effects, given the lag with which monetary policy affects prices.
Referring to the post-pandemic inflation-targeting period, Gupta said the MPC had acted whenever inflation reached the tolerance limits, helping preserve the credibility of the framework. She added that a further increase in the policy rate might be needed, depending on incoming data on inflation, its spread across the basket and second-round effects.
“With projections indicating the likelihood of headline inflation hitting the upper tolerance limit of 6 per cent, one may not want to wait for more definitive evidence of generalisation, and instead be mindful of the fact that monetary policy works with a lag,” said Gupta.
The minutes also reflect concerns about the risks of excessive tightening. Bhattacharya said domestic financial conditions had already tightened significantly, reducing the need for large policy actions. The pace of further rate increases would need to be calibrated carefully, he said, warning that rapid adjustments could constrain growth and weaken the growth-led capital flows that India relies on.
He also flagged vulnerabilities in India’s balance of payments amid tight global financial conditions, noting the importance of maintaining an interest-rate differential with G7 economies to attract debt flows.
Global uncertainties featured in the committee’s assessment, including renewed tensions in West Asia, volatile crude oil prices and the US Federal Reserve’s 25-basis-point rate hike in September, amid elevated global bond yields.
The MPC’s next meeting is scheduled for December 2-4. By then, members will have two more inflation readings and a clearer assessment of how much of the supply shock is feeding through to domestic prices.