Failed UPI, ATM or card payment? Here’s when you’ll get ₹100 per day for a delayed refund — Key RBI rules explained
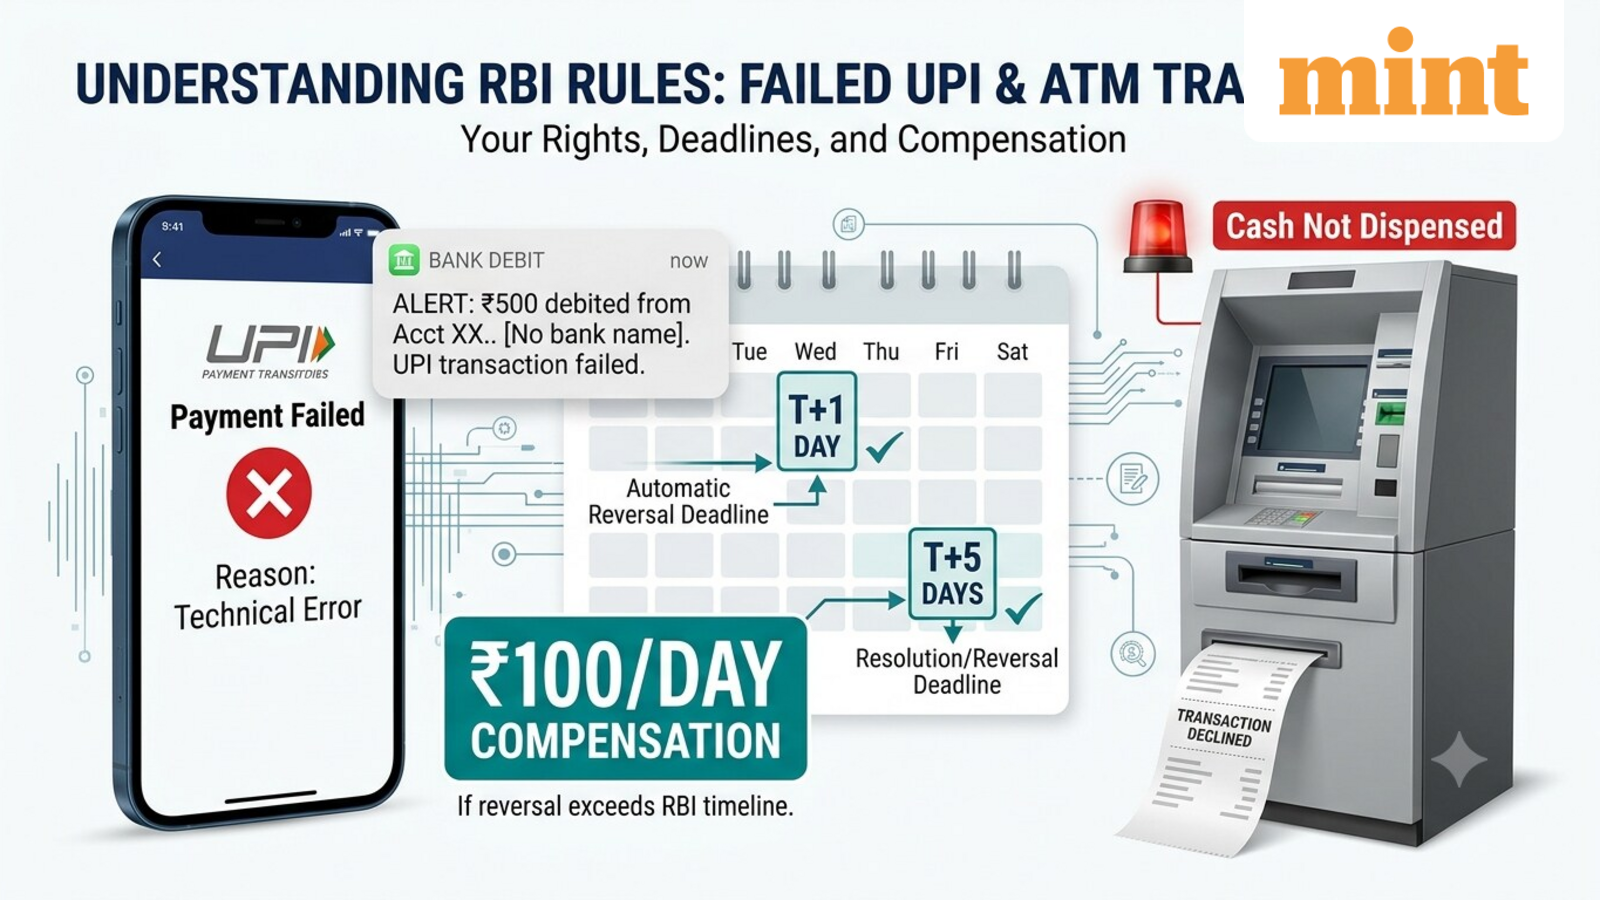
Suppose you make a UPI payment to a friend or merchant, or withdraw cash from an ATM, but the transaction fails even though your bank account is debited. If the money is not returned within the prescribed time, you may be entitled to compensation of ₹100 per day for the delay under Reserve Bank of India (RBI) rules.
The compensation depends on the type of transaction and the deadline prescribed for reversing the amount. Here is what customers need to know.
What is considered a failed transaction?
According to RBI’s circular, Harmonisation of Turn Around Time (TAT) and customer compensation for failed transactions using authorised Payment Systems, dated September 20, 2019, a failed transaction is one that is not completed for reasons not attributable to the customer.
These may include communication failures, an ATM running out of cash, a session timing out, or money not reaching the beneficiary’s account despite the sender’s account being debited. The framework also covers certain delays in crediting money or initiating a reversal.
The rules came into effect on October 15, 2019, and cover domestic transactions where both the sender and the beneficiary are in India. The term bank also includes authorised non-bank payment service providers, wherever applicable.
RBI states that the prescribed turnaround time is the outer limit for resolving a failed transaction. If compensation is payable, it must be credited automatically, without waiting for the customer to file a claim.
How many days do you get ₹100 per day for a delayed refund?
The deadline varies by payment method. For some transactions, the amount must be reversed by T+1 day, while others have a T+5-day deadline.
| Payment type | Example | Deadline for reversal or correction | Compensation for delay |
| ATM / micro-ATM | You withdraw ₹2,000, but the ATM gives no cash and debits your account. | Within T+5 days | ₹100 per day beyond T+5 |
| UPI P2P (person-to-person) transfer | You send money to a friend through UPI, they do not receive it and but your account is debited. | Within T+1 day | ₹100 per day beyond T+1 |
| UPI P2M (person-to-merchant) payment | You pay a shopkeeper by scanning a QR code, but the payment is not confirmed at the merchant’s end. | Within T+5 days | ₹100 per day beyond T+5 |
| Card-to-card transfer | You transfer money from one card to another, but the recipient does not receive it. | Within T+1 day | ₹100 per day beyond T+1 |
| Card payment at a shop (PoS), including cash at PoS | You pay by card at a shop, but the transaction is not confirmed. | Within T+5 days | ₹100 per day beyond T+5 |
| Online card payment (e-commerce) | You pay online, but the website does not confirm the payment. | Within T+5 days | ₹100 per day beyond T+5 |
| IMPS transfer | You send ₹5,000 through IMPS, but the recipient does not receive it. | Within T+1 day | ₹100 per day beyond T+1 |
| National Automated Clearing House (NACH) | A scheduled electronic payment is not credited, or a failed transaction is not reversed. | Within T+1 day by beneficiary bank | ₹100 per day beyond T+1 |
| NACH debit after mandate cancellation | You cancel an automatic debit instruction, but the bank still deducts money. | Customer’s bank is responsible; resolution within T+1 day | ₹100 per day beyond T+1, as specified in the RBI table |
| Prepaid cards and wallets — off-us | A wallet or prepaid card transaction is routed through UPI, IMPS or a card network. | Depends on the payment system used | The relevant payment system’s TAT and compensation rules apply |
| Prepaid cards and wallets — on-us | You make a wallet payment, but the recipient does not receive the money or the merchant does not receive confirmation. | Within T+1 day | ₹100 per day beyond T+1 |
Source: RBI’s circular, “Harmonisation of Turn Around Time (TAT) and Customer Compensation for Failed Transactions Using Authorised Payment Systems”. Wordings simplified for clarity and examples are added. T refers to the calendar date of the transaction.
What do T, T+1, and T+5 mean?
Under the RBI framework, T refers to the calendar date on which the transaction takes place. T+1 means the following day, while T+5 means five days after the transaction date.
For example, suppose a UPI transfer fails on October 18, and the sender’s account is debited, but the beneficiary’s account is not credited. The applicable deadline is T+1 day, meaning October 19. If the reversal is delayed beyond this prescribed deadline, compensation of ₹100 per day becomes payable for the delay.
For an ATM cash withdrawal that fails on October 18, the deadline is T+5, or October 23.
Are these calendar days or working days?
The September 2019 circular defines T by reference to the calendar date. A temporary COVID-19-related relaxation changed the applicable timeline to working days for a specified period. RBI’s May 21, 2021 circular extended that relaxation prospectively until December 30, 2021.
The temporary relaxation has expired. Therefore, the framework currently uses calendar days, rather than excluding weekends and bank holidays, for calculating the prescribed TAT.
What should customers do if the refund is delayed?
Customers should first check their transaction status and contact their bank or payment service provider if the amount is not reversed within the applicable deadline. Under RBI’s framework, eligible compensation must be credited automatically.
If the customer does not receive the required resolution, they can lodge a complaint under the RBI Integrated Ombudsman Scheme.
Disclaimer: This is for informational purposes only. Customers should refer to the applicable RBI directions and contact their bank for transaction-specific assistance.