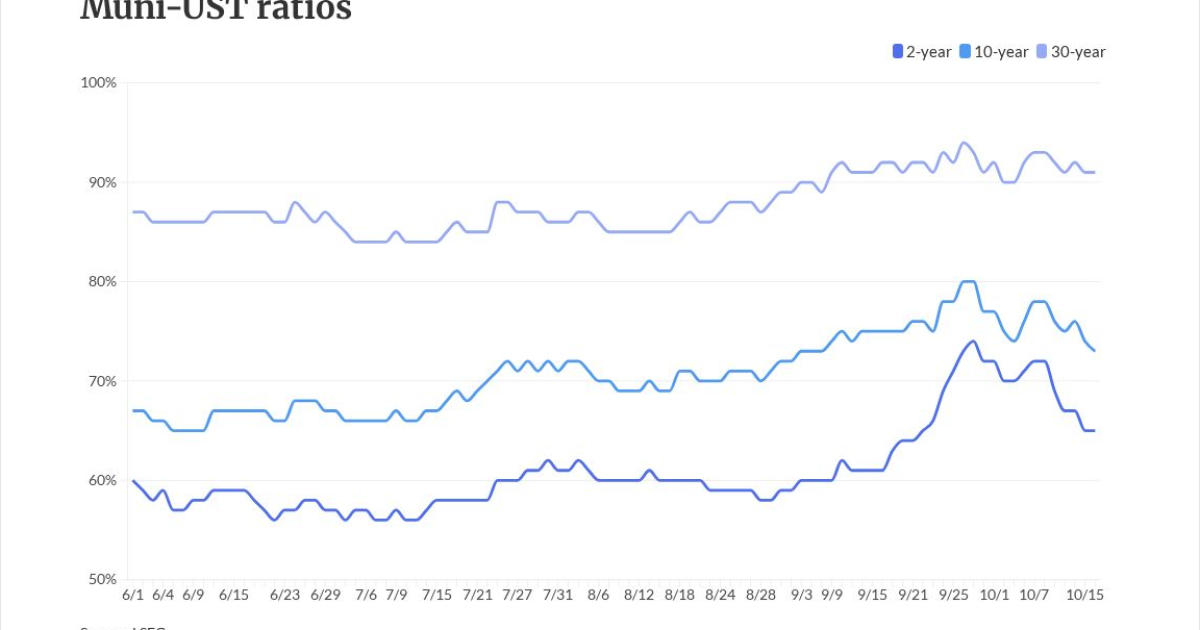
Munis steady after rally, USTs slightly weaker out long
Munis were little changed on Friday, as longer-term U.S. Treasuries cheapened and equities ended lower.
Processing Content
Muni yields richened by up to one basis point, depending on the scale. UST yields rose up to three basis points five years and out.
The October rally for USTs and lighter tax-exempt supply have driven munis’ recent overperformance, wrote J.P. Morgan analysts led by Peter DeGroot. Despite the “overwhelming backdrop of tax-trading,” the analysts wrote, munis’ value persists.
“The sizable rally in long-dated UST rates thus far in October has helped to reverse the tide of performance-related outflows just as tax-exempt supply moved to the sidelines,” the analysts wrote. “Amidst the seemingly all-encompassing backdrop of tax trading, long-horizon total return-driven buyers can find value in liquidity-starved, out-of-favor structures where spreads have widened including short-calls (calls in 2031 and shorter), odd-lot transaction size (sub $200,000), AMT (max-spread in 10-years and shorter), sub 5% coupon bonds, and pari municipal-corporate market credits (prepay, power, industrials).”
Primary to come
Issuance is an estimated $9.944 billion for the week of Oct. 19, with $5.786 billion of negotiated deals on tap and $4.158 billion of competitives, according to LSEG.
The Los Angeles Unified School District leads the negotiated calendar, with $1.4 billion of general obligation bonds.
The competitive calendar is led by the Dormitory Authority of the State of New York, with $1.74 billion of state personal income tax revenue bonds, to be sold across five series.